

 Emergency fund
 10 steps
Quick answer: how to build an emergency fund
- Add up your essential monthly expenses: housing, food, bills, transportation, health and minimum debt payments.
- Multiply by the number of months in your goal. Brazil's federal Investor Portal estimates 6 to 12 months of expenses; start with a first stage of 1 month.
- Pay yourself first: transfer a fixed amount on the day your money comes in, even if it's small.
- Keep it in a low-risk investment with daily liquidity and no lock-up: Tesouro Selic, Tesouro Reserva, a CDB with daily redemption or poupança.
- Use it only for real emergencies and put back what you take out.
What's your case?
How to build an emergency fund: 10 steps
1Work out your essential monthly expenses
- List what you can't stop paying: rent or mortgage, condo fees, food, electricity, water, gas, internet, transportation, medicine and health insurance.
- Include minimum debt payments and the expenses of anyone who depends on you.
- Leave out what you could cut in a crisis: delivery, subscriptions, leisure and shopping.
- Use your statements and bills from the last 3 months instead of guessing.
2Set the goal in months of expenses
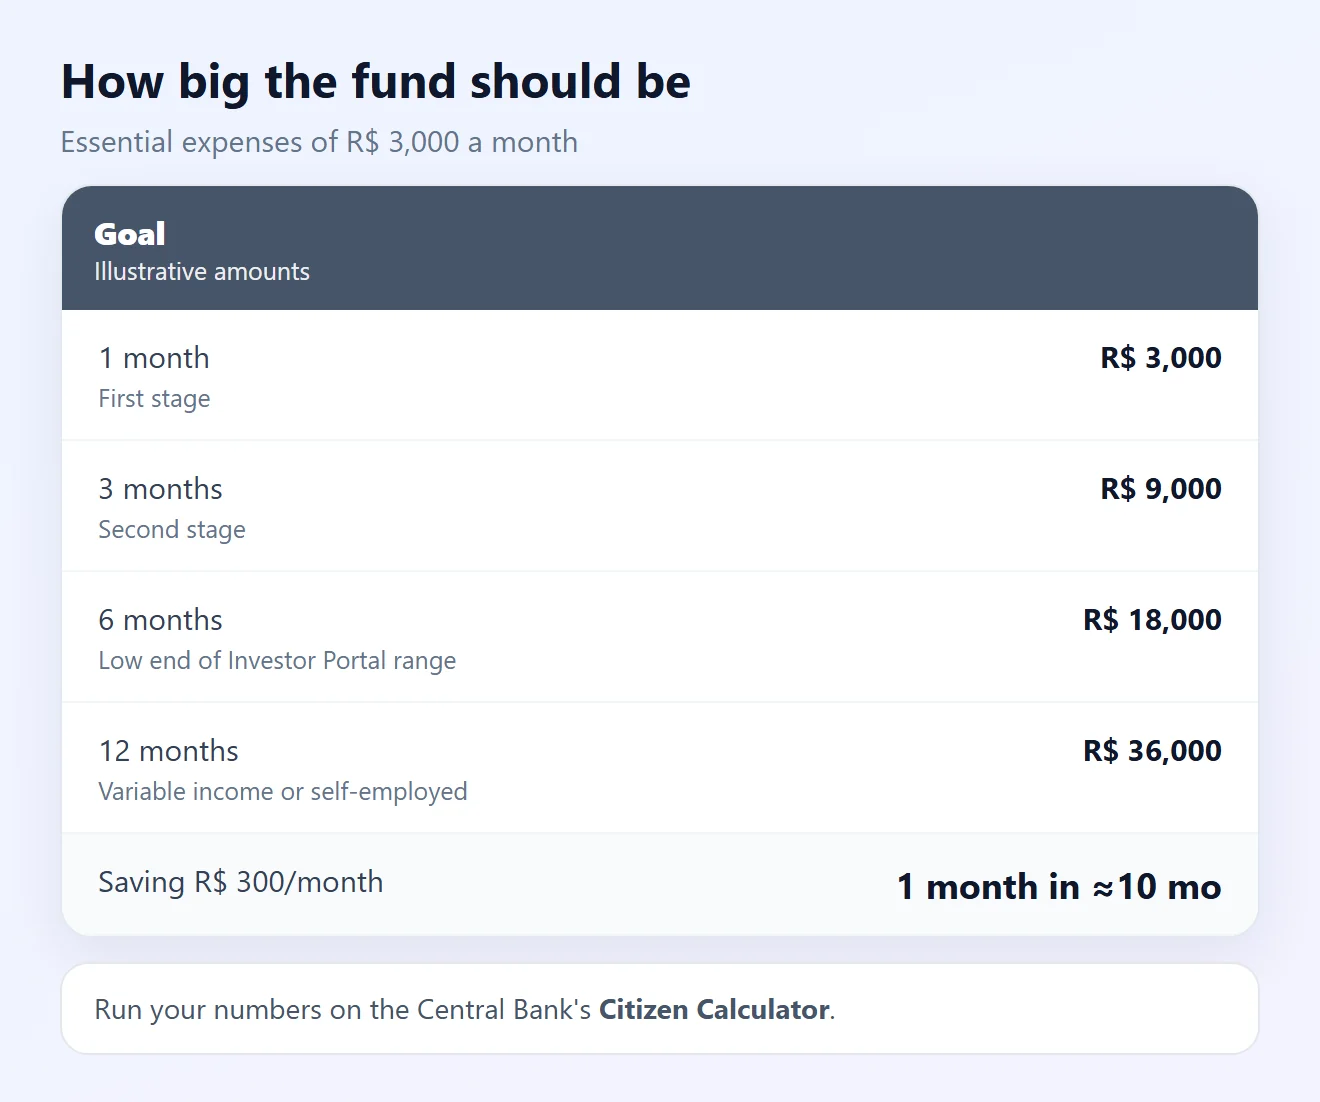
- The math: essential expenses × number of months. At R$ 3,000 a month, 6 months is R$ 18,000.
- The Investor Portal of Brazil's securities regulator (CVM) estimates the fund should hold between 6 and 12 months of expenses. The number depends on whether your income is fixed or variable, how stable your job is and how many people help pay the bills.
- Variable income, self-employed, MEI or the only income in the house: aim for the high end of the range.
- A big goal is intimidating. Split it into stages: 1 month, then 3, then 6. Each stage already protects you.
Self-employed? See emergency fund for the self-employed.
3Expensive debt? Start with a small fund
- Revolving credit card debt and overdrafts usually charge far more interest than any fund will earn.
- A common path: build a small fund (for example, 1 month of expenses) so the next emergency doesn't go back on the card, then focus on paying off or renegotiating the expensive debt.
- Once the debt is gone, send the old payment amount to the fund.
4Pay yourself first, even with little
- Brazil's Central Bank recommends setting savings aside as soon as income arrives, not waiting for what's left at the end of the month.
- Schedule an automatic transfer on payday to an account or savings “box” used only for the fund.
- Start with what fits: R$ 50 or R$ 100 a month already builds the habit. Increase it when a payment ends or you get a raise.
- To see how much is left and what the money earns, use the Central Bank's Citizen Calculator, under “Regular deposits”.
5Keep it low-risk with daily liquidity
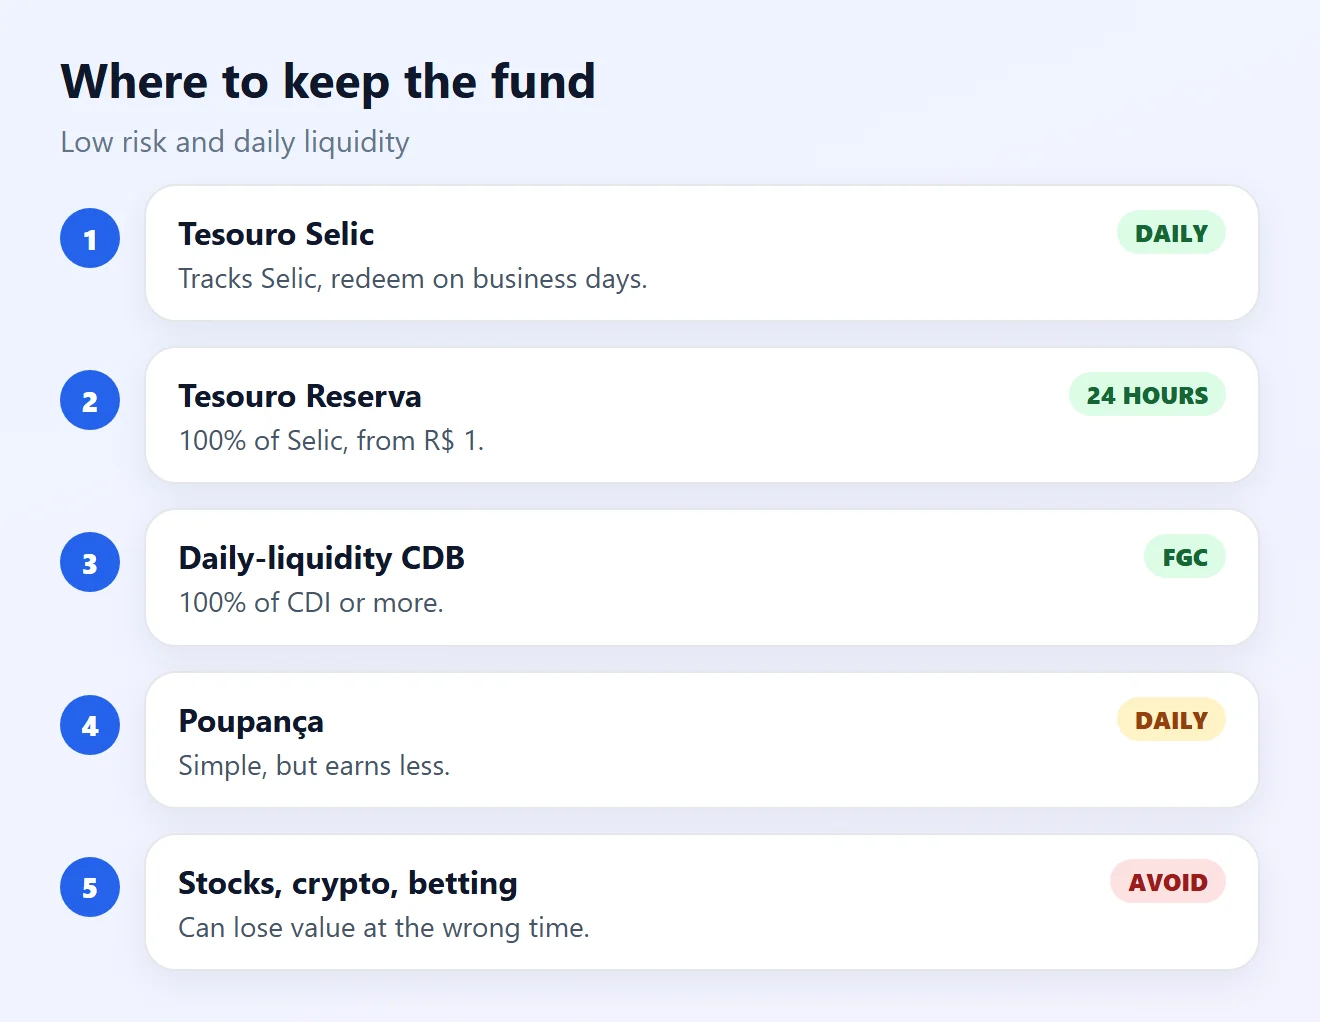
- According to the Investor Portal, the fund has no set deadline and needs high liquidity: the ideal is a low-risk investment with daily liquidity and no lock-up.
- Tesouro Selic: a government bond that tracks the Selic rate, with little day-to-day fluctuation; redeemable on business days.
- Tesouro Reserva: launched in May 2026, it pays 100% of Selic with no mark-to-market and lets you invest and redeem almost 24/7, from R$ 1. At launch, it was only available at Banco do Brasil.
- CDB with daily liquidity: prefer ones paying 100% of CDI or more. It's covered by the FGC guarantee up to R$ 250,000 per CPF per institution.
- Poupança: simple and FGC-covered, but it usually earns less and pays only on its monthly anniversary date.
- The fund's job is to be available, not to earn the most. Avoid stocks, crypto, funds with lock-ups and, of course, betting.
6Compare net returns: tax, IOF and fees
- Tesouro and CDBs pay regressive income tax on earnings: the longer the money stays, the lower the rate.
- Redemptions within 30 days may pay IOF tax on the earnings.
- Poupança for individuals is income-tax exempt.
- Check fees: on Tesouro Reserva, the B3 custody fee is 0.20% a year, waived for up to R$ 10,000 invested.
- Always compare what's left after tax and fees, not just the advertised percentage.
7Speed it up with extra money and cuts
- Send part of your 13th salary, tax refund, bonuses or sales of unused items to the fund.
- Pick two or three cuts you'll barely miss and send the difference straight to the fund.
- Track the balance every month and celebrate each stage.
8Know when to use it and when not to
- Use it for the unexpected: losing your job or income, health problems, urgent repairs to your home or work vehicle.
- Expenses you know are coming, such as IPVA, IPTU, school supplies and enrollment fees, are not emergencies: set money aside for them during the year.
- Trips, a new phone and sales aren't either. Create separate goals for those.
- Before using the fund, compare: it's almost always cheaper than a loan, credit card or overdraft.
See how to save money for a trip without touching the fund.
9Refill what you used and review the goal
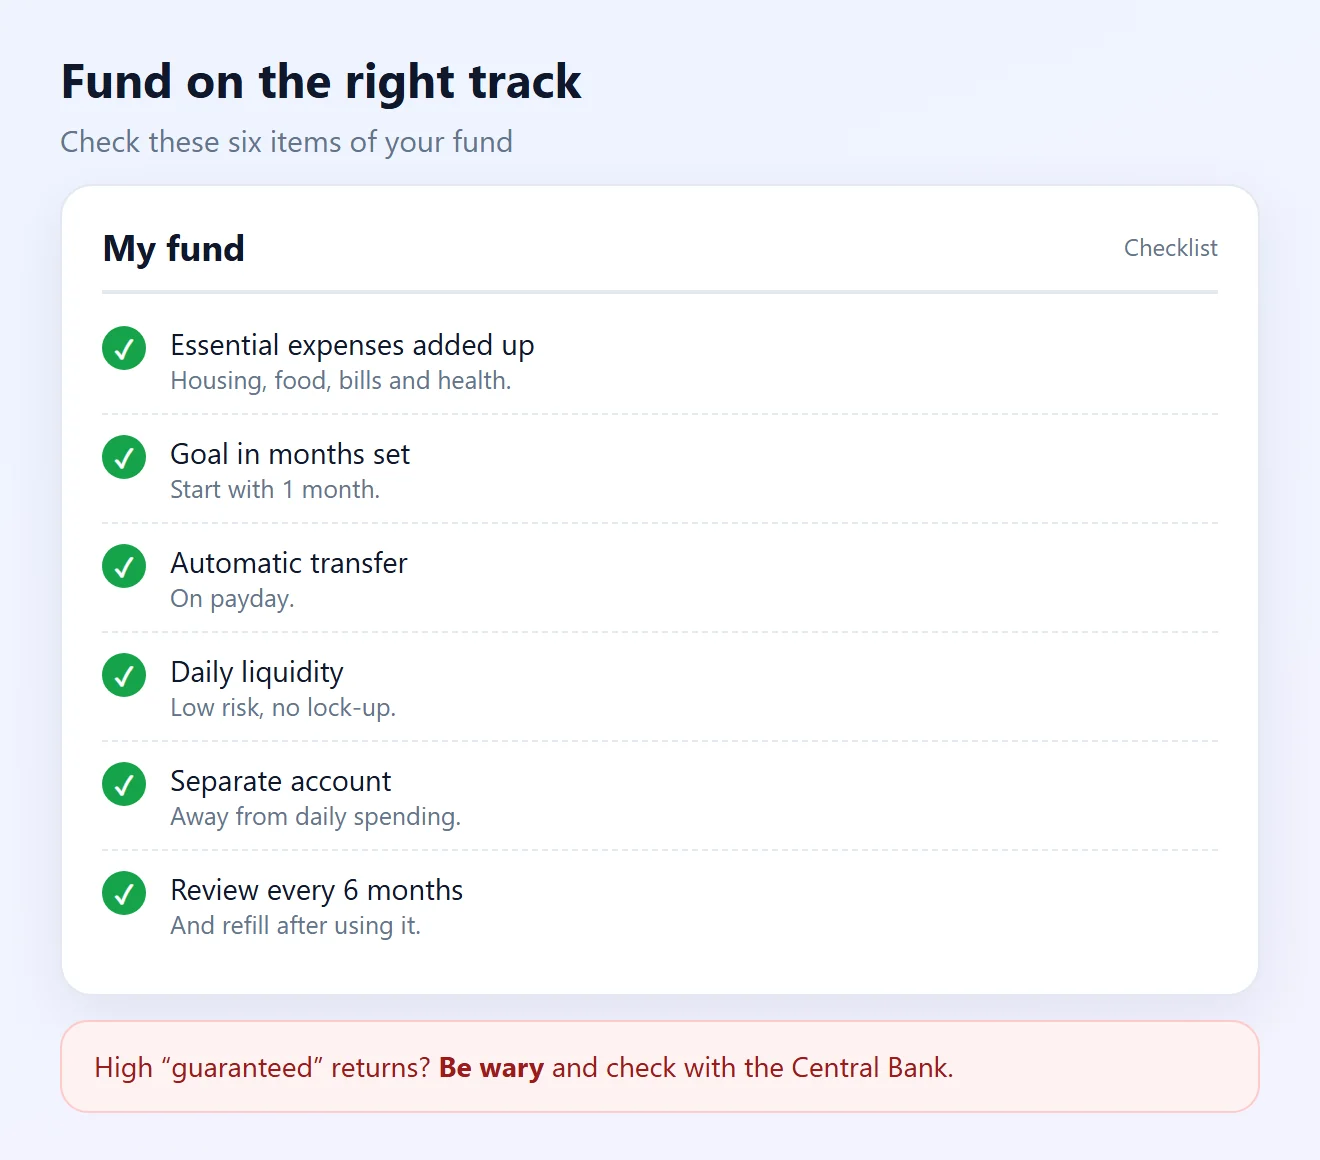
- Used the fund? Start saving again the next month until it's back to the full amount.
- Review the goal at least every 6 months and whenever something changes: rent, a child, job, income.
- Once you hit the goal, your monthly savings can go to longer-term goals.
10Avoid “safe investment” scams
- Be wary of high, guaranteed returns, pressure to deposit, Pix payments to individuals and invitations via WhatsApp or social media.
- Before investing, check that the institution is authorized by the Central Bank on its “Find an institution” page.
- A CDB outside an authorized bank has no FGC guarantee, and the guarantee never covers pyramids or unregistered “investment clubs”.
- Never give anyone your password, token or confirmation code.
Situation and what to do
| Situation | Likely cause | What to do |
|---|---|---|
| I don't know how much to save | Expenses not added up | Add essentials and multiply (steps 1 and 2) |
| Nothing is ever left | Saving only leftovers | Transfer on payday (step 4) |
| I pay card interest | Expensive debt | Small fund and pay off the debt (step 3) |
| Money sits in checking | Not invested | Tesouro Selic, Tesouro Reserva or daily CDB (step 5) |
| I used the fund for IPVA | Predictable expense | Refill and save for yearly costs (steps 8 and 9) |
| Offer of 3% a month guaranteed | Possible scam | Check with the Central Bank and don't deposit (step 10) |
Frequently asked questions
How many months of expenses should an emergency fund hold?
The CVM Investor Portal estimates 6 to 12 months of expenses. People with variable income or who are the only earner should aim closer to 12. Starting with 1 month as a first stage already helps.
How do I calculate the fund amount?
Add up your essential monthly expenses and multiply by the number of months in your goal. Example: R$ 3,000 × 6 months = R$ 18,000.
Where should I keep an emergency fund?
In a low-risk investment with daily liquidity and no lock-up, such as Tesouro Selic, Tesouro Reserva, a daily-redemption CDB from an authorized bank or poupança.
Is poupança good for an emergency fund?
It's safe, simple and income-tax exempt, but usually earns less than Tesouro Selic and CDBs paying 100% of CDI. It works for getting started.
What is Tesouro Reserva?
A government bond launched in May 2026 that pays 100% of Selic with no mark-to-market and can be bought and redeemed almost 24/7, from R$ 1. At launch, only Banco do Brasil offered it.
Should I pay off debt or build the fund first?
With expensive debt like revolving credit or overdraft, build a small fund and focus on paying off the debt. Then send the old payment amount to the fund.
How long does it take to build the fund?
It depends on how much you save each month. At R$ 300 a month, the first R$ 3,000 stage takes about 10 months. Extra money, like the 13th salary, shortens it.
Can I use the fund for IPVA or school fees?
Ideally not. They're predictable expenses that should be saved for during the year. The fund is for the unexpected.
Does the FGC protect my fund?
Poupança and CDBs from member institutions are covered by the FGC up to R$ 250,000 per CPF per institution, capped at R$ 1 million every 4 years. Tesouro bonds are federal government bonds and don't depend on the FGC.
I used the fund. Now what?
Start saving again the next month until it's refilled, and review the goal if your expenses changed.
Related content
More practical solutions in Emergency fund.
How to build an emergency fund when self-employed
Aprenda the montar a fund of emergency mesmo with income variável. Veja quanto guardar, as definir goals and onde manter the money for lidar with períodos of baixa demanda or unexpected events.
 15 minutes
Financial Education for Children: How to Teach It Early
Learn how to teach financial education to children and teenagers through practical examples, goals, conscious allowances, and healthy spending habits.
30 minutes
How to plan financially for retirement
Learn how to plan the retirement financial organizando objetivos, expenses future, sources of income and estratégias of longo term for build more safety financial.
30 minutes
Sources consulted
- Investor Portal (CVM): Emergencies and retirement (in Portuguese)
- Investor Portal (CVM): Planning and managing financial reserves (in Portuguese)
- Central Bank of Brazil: Financial Education Notebook, Module 5 – Active Saving and Investment (PDF, in Portuguese)
- Central Bank of Brazil: Citizen Calculator – Regular deposits (in Portuguese)
- National Treasury: Tesouro Reserva launch, May 2026 (in Portuguese)
- Tesouro Direto: Tesouro Reserva (in Portuguese)
- Tesouro Direto: Types of bonds (in Portuguese)
- FGC: About the guarantee (in Portuguese)
- Central Bank of Brazil: Find an institution (in Portuguese)
The images on this page are illustrations created by Fixfy. Amounts are examples. Product rules, taxes and fees can change: check with the institution before investing.