

 Debt
 10 steps
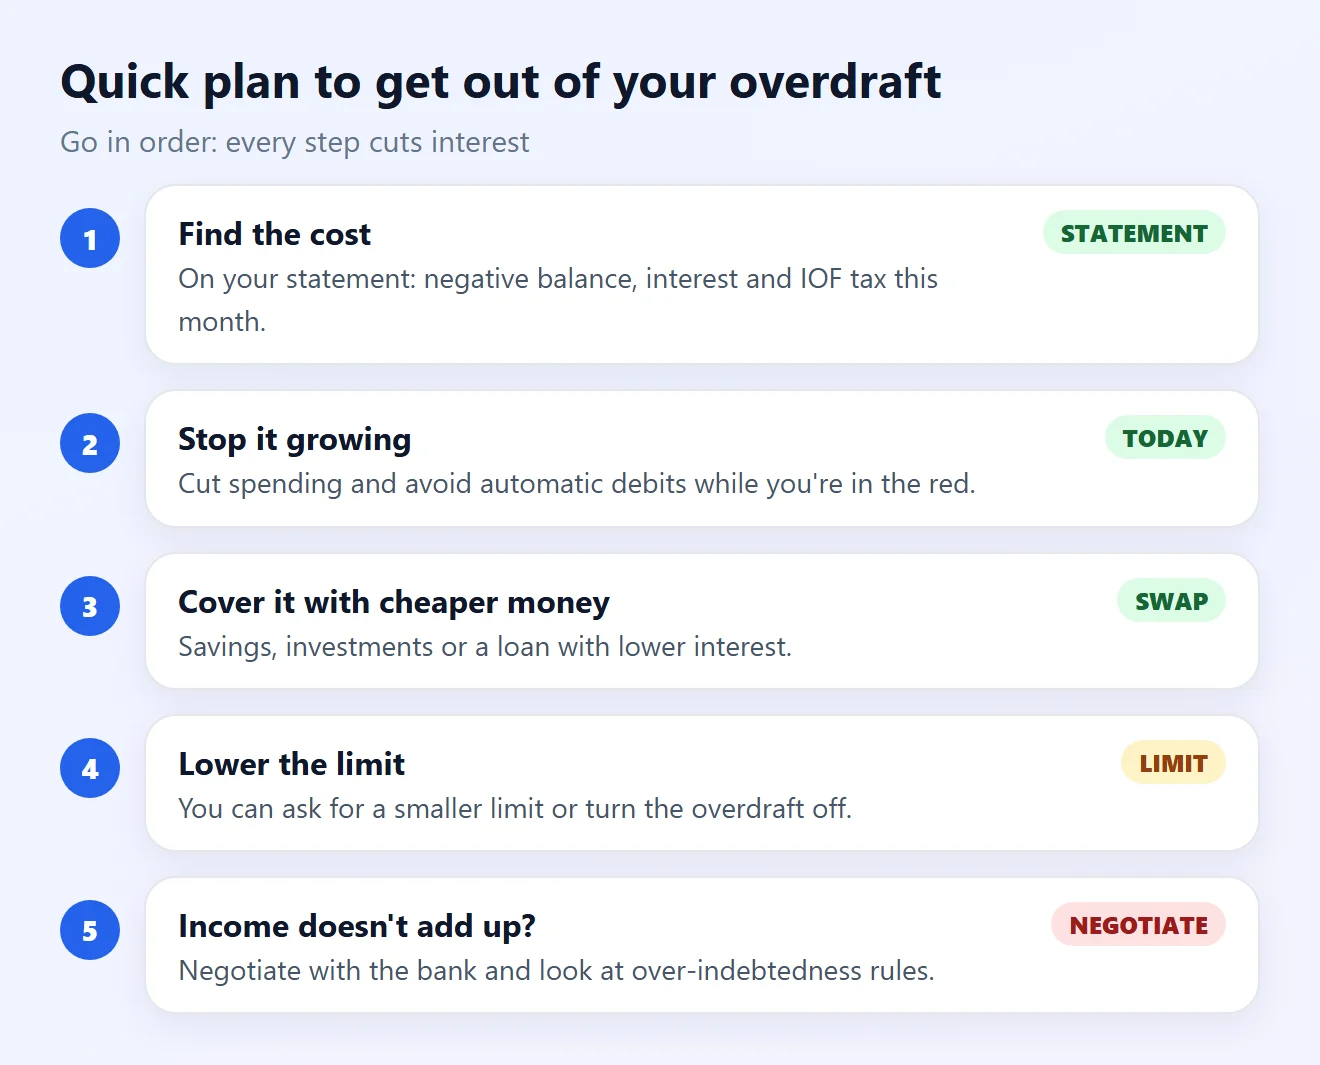
Quick answer: what to do now
- Open your statement and check how far below zero you are and how much you paid in interest and IOF tax this month.
- Stop the balance from growing: cut spending and move automatic debits to a later date.
- Pay it off with cheaper money: savings, investments or a loan with lower interest. Compare rates on the Central Bank's website.
- Ask the bank to lower or remove the limit. It can't raise your limit without your permission.
- Can't pay? Negotiate with the bank before the debt snowballs.
This guide follows the rules for the cheque especial, the overdraft on Brazilian checking accounts. The steps to get out of an overdraft work for any bank.
Which case is yours?
How to get out of your overdraft: 10 steps
1Find out how much you owe and what you're paying
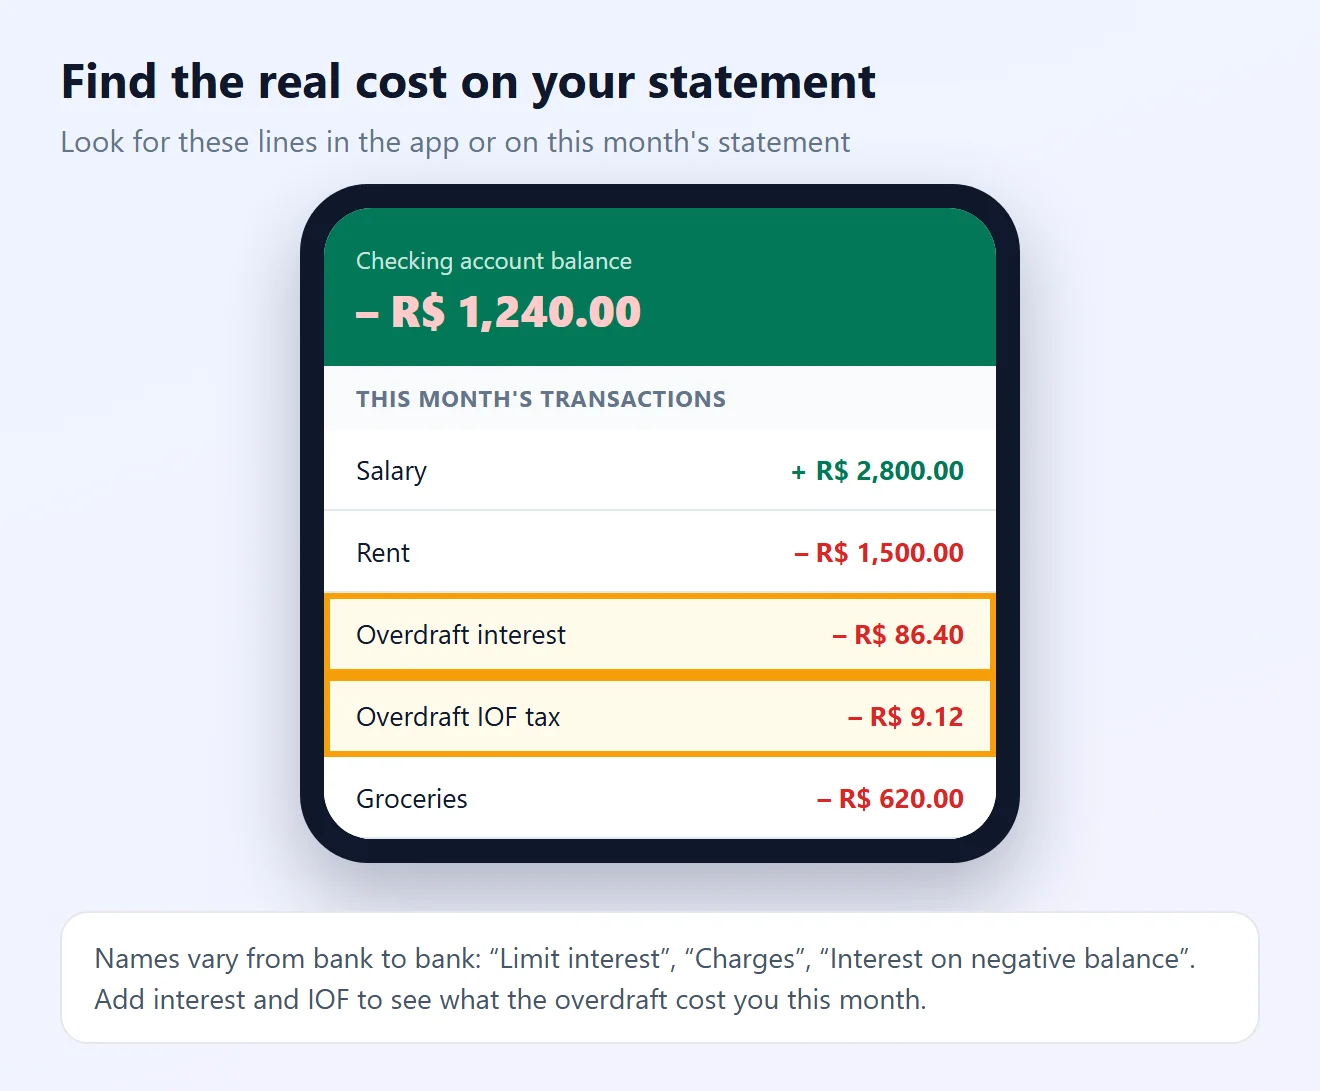
- Open your bank's app and check your account balance. If it's negative, that's what you owe on the overdraft.
- On this month's statement, look for the overdraft interest and IOF tax lines. Add them up: that's the monthly cost of the debt.
- Note the interest rate the bank charges. It's in your contract, the app or your monthly statement.
2Understand why the debt grows so fast
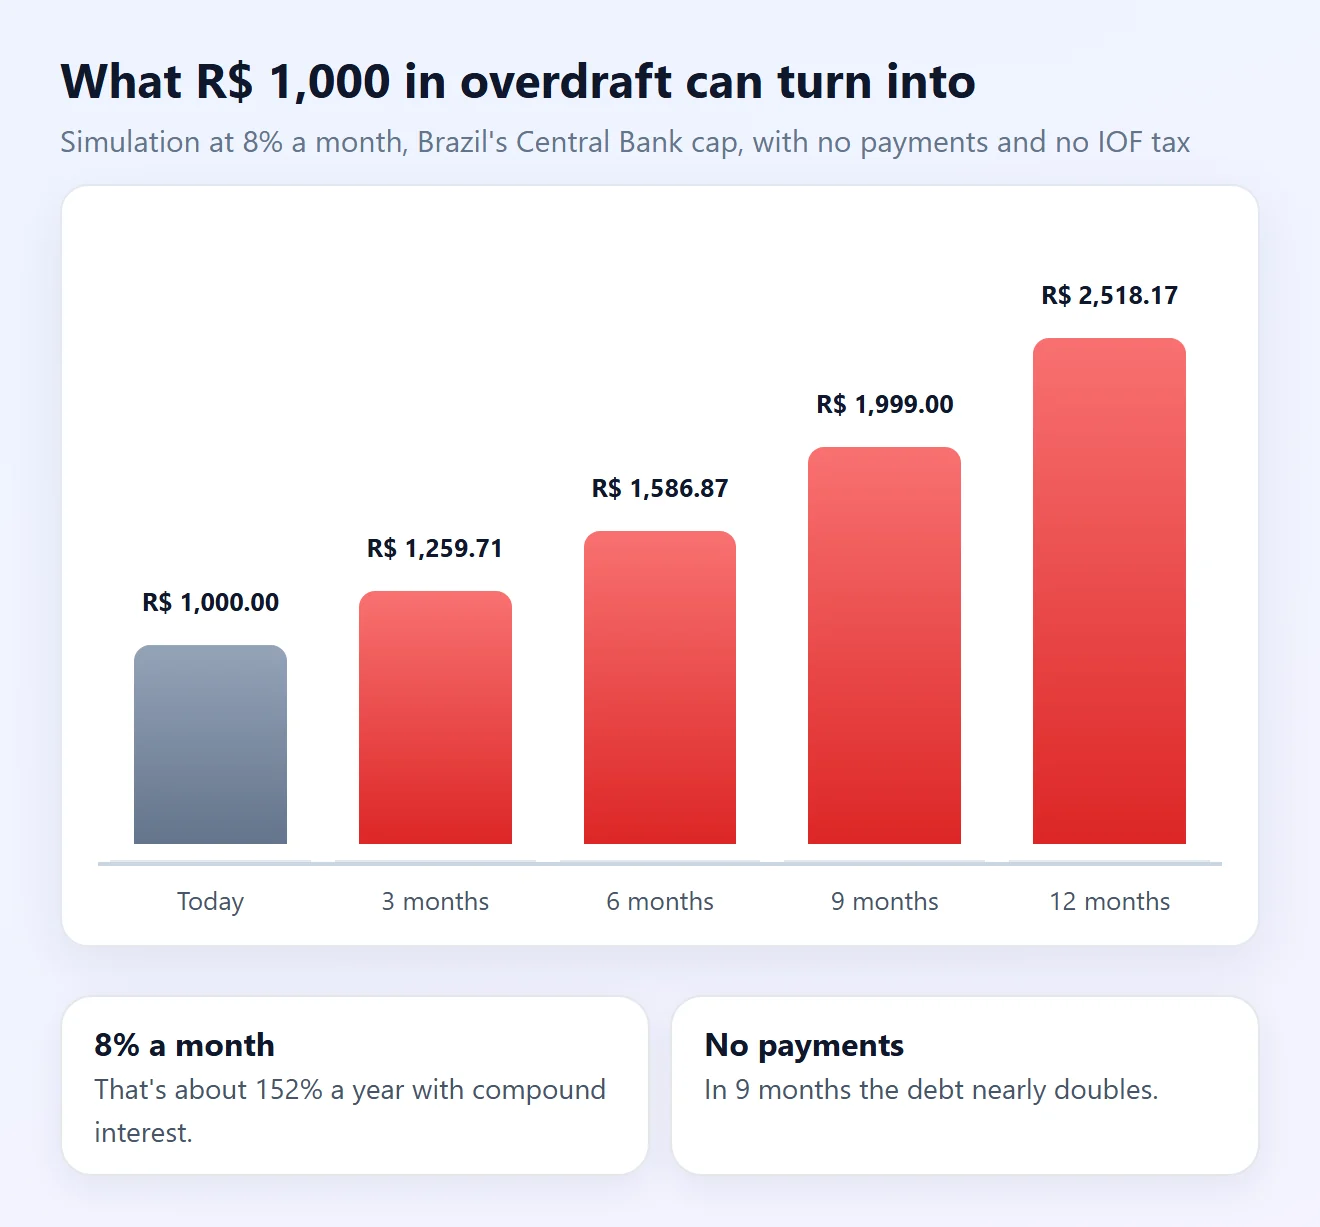
- Under Brazil's CMN Resolution 4,765, overdraft interest is capped at 8% a month on the amount used. It sounds small, but with compound interest that's about 152% a year.
- With no payments, R$ 1,000 becomes almost R$ 2,000 in 9 months and over R$ 2,500 in a year, before IOF tax.
- The fee just for having a limit was revoked and declared unconstitutional by Brazil's Supreme Court. Today the cost is interest and IOF on what you use.
Want to understand the math? See how compound interest makes debt grow.
3Stop the negative balance from growing
- For a few weeks, cut non-essential spending and only pay by debit or Pix when you have a positive balance.
- Check your automatic debits (bills, subscriptions, installments). Move them to just after payday or cancel what you don't use.
- Remember that money coming into the account covers the negative balance first. Plan your month with that in mind.
4Have money saved? Use it to pay off the overdraft
Savings accounts and conservative investments earn far less than 8% a month. Keeping money saved while your account is overdrawn usually costs you.
- Withdraw what you need and pay off the negative balance in one go.
- Then start saving every month again to rebuild your emergency fund.
- Investment with a lock-up period or early withdrawal penalty? Compare the penalty with the overdraft interest.
5Swap it for cheaper credit
If you can't pay it off with your own money, swap the expensive debt for a cheaper one:
- Open the Central Bank's Interest Rates page and compare the average for Cheque especial with payroll-deductible and regular personal loans, bank by bank.
- Ask for offers and compare the Total Effective Cost (CET), which includes interest, fees and taxes.
- Use the loan only to clear the overdraft, then lower the limit right away (step 7).
Don't swap your overdraft for revolving credit card debt: it's also among the most expensive kinds of credit. Learn more in how to refinance a debt.
6Ask the bank to turn the balance into installments
- Many banks offer to turn the overdraft balance into fixed installments with lower interest. Ask in the app, by phone or at a branch.
- Before accepting, compare the plan's CET with the other options in step 5.
- Pick an installment that fits your budget without pushing you back into the limit.
7Lower or remove the limit
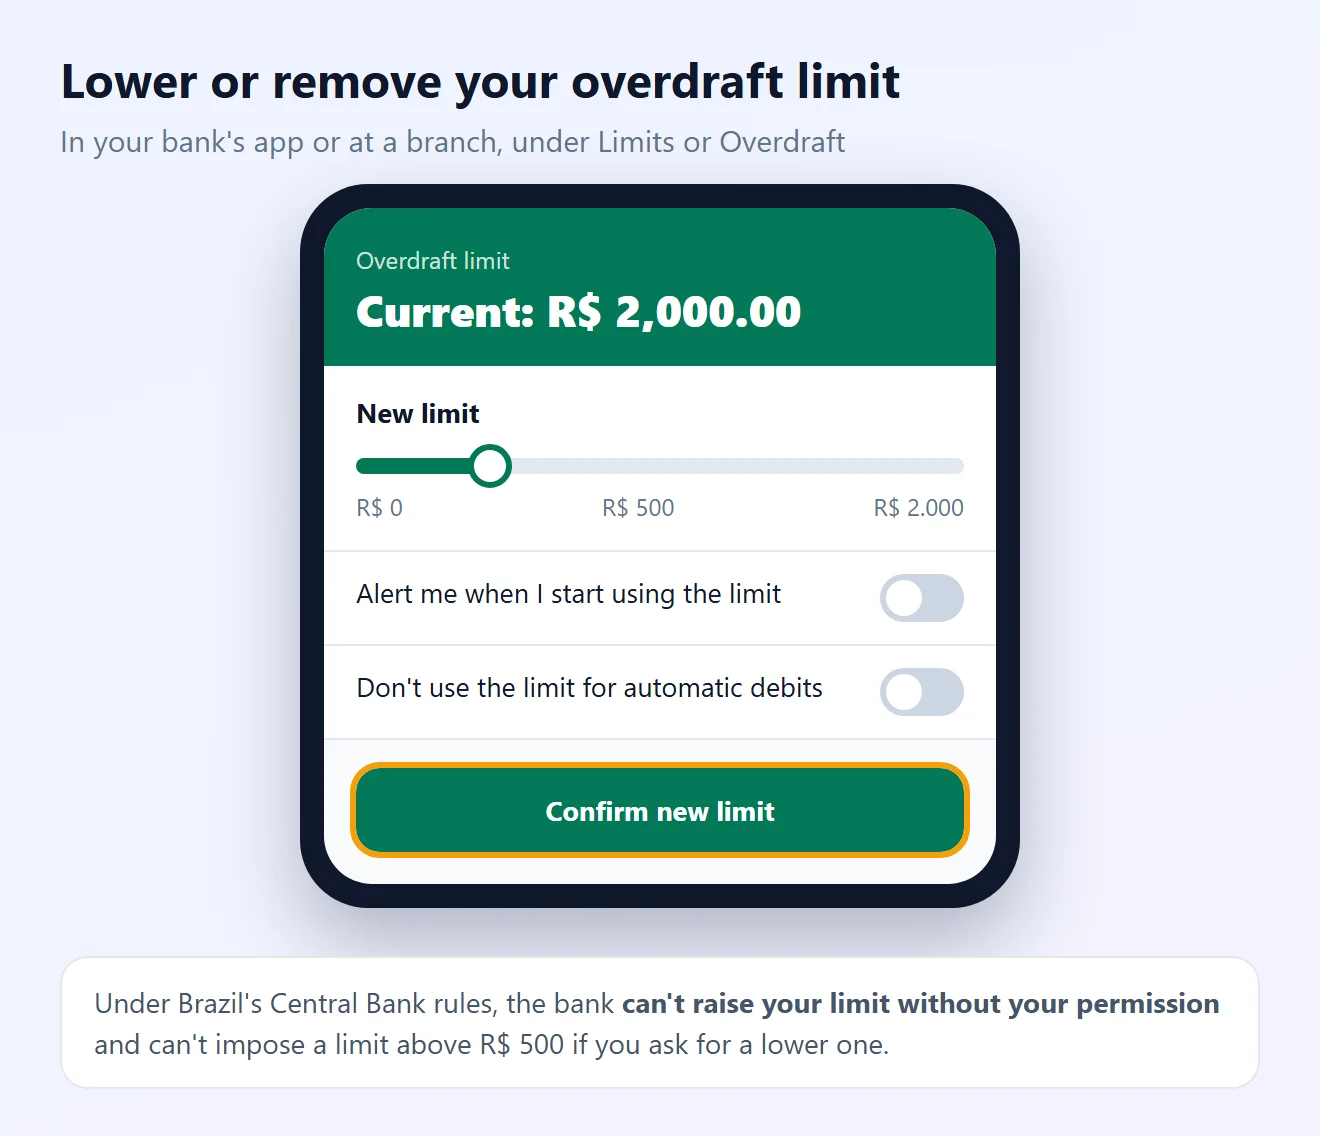
A high limit feels like money you have. CMN Resolution 4,765 guarantees that:
- The bank can't raise your limit without your permission, asked for each increase offer.
- If you ask for a lower limit, the bank can't impose a limit above R$ 500.
- If the bank lowers your limit on its own, it must give 30 days' notice, unless your credit risk has worsened. In that case, it must tell you by the time of the cut.
Look in the app for Limits or Overdraft, or ask customer service.
8Make a plan to get out and stay out
- List your monthly income and fixed costs. What's left is what you can put toward the debt.
- Set that amount aside as soon as your salary arrives, before other spending.
- Paid it off? Keep saving the same amount until you have an emergency fund. That's what keeps you out of the overdraft next time something comes up.
9See all your debts in Registrato
Registrato, from Brazil's Central Bank, shows free reports of your debts and loans at every bank. It helps you see whether the overdraft is your only debt and which one to pay first.
- Access it through Meu BC with a silver or gold gov.br account and two-step verification turned on.
- Always pay the debt with the highest interest first.
10Can't pay? Negotiate and know your rights
- Contact the bank before you fall behind on other bills and ask for a written offer. See how to negotiate debt with your bank.
- If the bank doesn't solve it, file a complaint at consumidor.gov.br or with the Central Bank.
- If your total debt doesn't fit your income even after cutting costs, read about over-indebtedness rules.
Be wary of anyone who promises to “clean up” your debts for an upfront payment. Negotiate only through your bank's official channels.
Situation and what to do
| Situation | Risk | What to do |
|---|---|---|
| Used it a few days, I have the money | Low | Cover the balance today (step 3) |
| I use the limit every month | Medium | Budget plan and lower the limit (steps 7 and 8) |
| I have savings or investments | Medium | Withdraw and pay off (step 4) |
| Negative for months | High | Swap for cheaper credit or installments (steps 5 and 6) |
| Several debts at once | High | Registrato and pay the most expensive first (step 9) |
| Income doesn't cover the debts | Very high | Negotiate and look at over-indebtedness rules (step 10) |
Frequently asked questions
What is an overdraft (cheque especial)?
It's a credit limit linked to your checking account. When the balance goes negative, the bank covers the difference and charges interest on the amount used until you put money back in.
What's the maximum overdraft interest in Brazil?
Under CMN Resolution 4,765, overdraft interest for individuals and MEI micro-entrepreneurs is capped at 8% a month on the amount used. IOF tax applies on top.
Can the bank charge a fee just for having an overdraft?
No. The fee for making the limit available was revoked by CMN Resolution 4,962 and declared unconstitutional by Brazil's Supreme Court in ADI 6,407.
Can the bank raise my limit without asking?
No. Under the Central Bank's rule, each limit increase needs your prior permission.
Can the bank lower my limit without notice?
It must give at least 30 days' notice. The exception is when your credit risk worsens: then the cut can be immediate, with notice by the time it happens.
How do I cancel or lower my overdraft?
Ask in the app, by phone or at a branch. If you ask for a lower limit, the bank can't impose a limit above R$ 500.
Should I use my savings to pay off the overdraft?
Usually, yes. Savings earn far less than overdraft interest. After paying it off, start saving again to rebuild your reserve.
Is a personal loan better than an overdraft?
It usually has lower interest, especially payroll-deductible loans. Compare rates on the Central Bank's Interest Rates page and the CET of each offer before signing.
Does using the overdraft hurt my credit?
Using the limit doesn't. But if the negative balance goes over the limit or stays unpaid, the debt can go to collections and to bad-credit registries.
How can I see all my bank debts?
In Registrato, from Brazil's Central Bank, accessed through Meu BC with a silver or gold gov.br account. The reports are free.
Related content
More practical solutions in Debt.
Compound Interest on Debt: How to Understand and Prevent Balance Growth
Entenda how to the compound interest aumentam the amount of a debt to the longo of the time, how to identify the encargos cobrados and quais atitudes helpm the reducesir the impact financial.
 15 minutes
How to Get Out of Debt: A Complete Guide to Reorganizing Your Finances
Learn how to sair of the debts with estratégias práticas of organization financial, negotiation of débitos, control of expenses and planning for recuperar your estabilidade financial.
30 minutes
Negative Credit Record in Brazil: How to Check and Resolve Outstanding Debts
Learn how to check for a negative credit record in Brazil, identify outstanding debts, negotiate with creditors, and track the regularization of your CPF safely.
15 minutes
Sources
- Central Bank of Brazil: CMN Resolution 4,765/2019 on overdrafts (in Portuguese)
- Central Bank of Brazil: Interest rates by product and bank (in Portuguese)
- Central Bank of Brazil: Registrato (in Portuguese)
- Consumidor.gov.br: complaints against companies and banks (in Portuguese)
The screens and chart in this guide are illustrations made by Fixfy. The simulation uses 8% a month with no payments and no IOF tax. This content is for information only and doesn't replace a review of your contract.