

 Debt
 10 steps
Quick answer: what to do now
- Check your CPF for free at Brazil's credit bureaus (Serasa, Boa Vista, SPC Brasil, Quod). Each one has its own list.
- For bank debts, also check the Central Bank's Registrato.
- Make sure each debt is yours and the amount is right. If it's wrong, ask for a correction.
- Negotiate directly with the creditor, get the deal in writing and keep the receipts.
- Once you've paid, the creditor has 5 business days to request your name's removal.
This guide follows Brazilian rules. A negative credit record (“nome negativado” or “nome sujo”) is not the same as an irregular CPF at the Federal Revenue. If you see “CPF pendente de regularização” or “suspenso”, it's a registration issue, not a debt: check your CPF status on the Receita Federal website.
Which case is yours?
How to clear a negative credit record: 10 steps
1Check your CPF for free at the credit bureaus
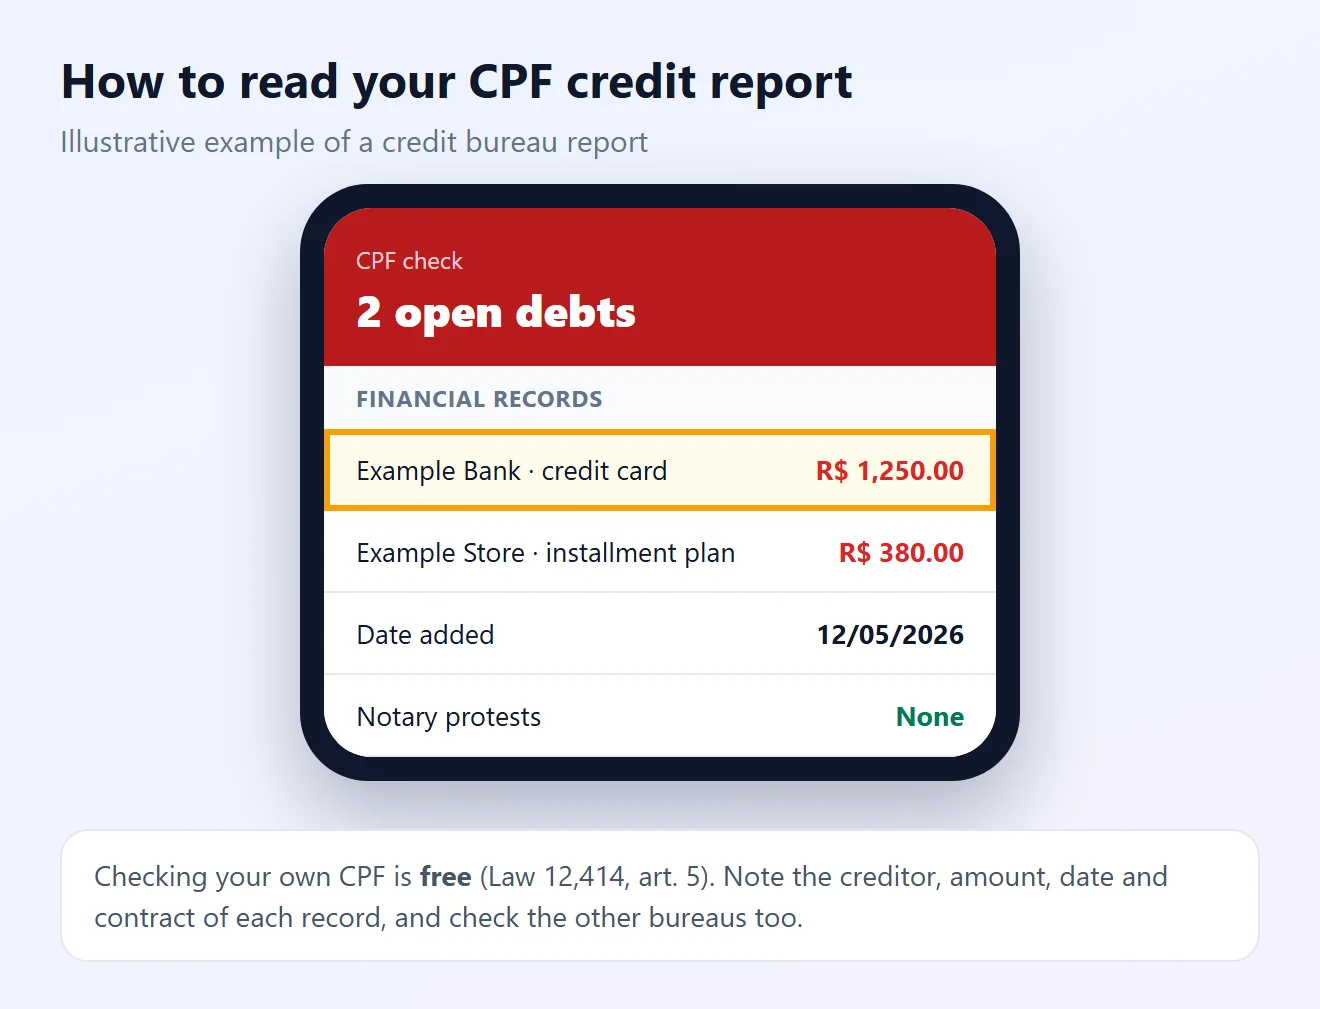
A negative record is an overdue debt listed in a credit default database. The main ones in Brazil are Serasa, Boa Vista, SPC Brasil and Quod.
- Check on the official website or app of each one: a debt may show up in one and not another.
- Checking your own CPF is free. Law 12,414 (art. 5) guarantees free access to your information, including your credit score.
- For each record, note the creditor, amount, date and contract number.
Nobody has to pay to find out whether they have a negative record. Be wary of websites that charge for it.
2See your bank debts in Registrato
Registrato, from Brazil's Central Bank, shows your loans, financing, credit cards and overdrafts at every bank for free, including what is overdue or was written off as a loss.
- Sign in through Meu BC with a gov.br silver or gold account.
- Registrato isn't a default list, but it helps you find forgotten bank debts and check amounts before negotiating.
3Check that the debt is yours and correct
- Under the Consumer Protection Code (CDC, art. 43, § 2), you must be notified in writing before being added. Under STJ Precedent 359, the database (the bureau) sends that notice.
- Wrong amount, date or details? Ask the bureau and the creditor for a correction. The CDC (art. 43, § 3) gives the database 5 business days to pass the correction on to whoever received the wrong data.
- Don't recognize the debt? It may be fraud using your data. Dispute it with the bureau and the creditor, file a police report and keep the protocol numbers.
If the creditor won't fix it, complain on consumidor.gov.br or to Procon. An improper record can lead to compensation in court.
4Organize your debts and choose the order
- Work out what's left each month after housing, food and basic bills.
- Prioritize essential services (power, water) and the highest-interest debts, such as credit cards and overdrafts.
- Check each debt's date: a negative record can't stay longer than 5 years (step 10).
Several debts at once? See how to get out of debt.
5Negotiate directly with the creditor
- Use the creditor's official app, website or customer service, or the negotiation platform of the bureau where the debt appears. Check that the offer also shows up in the creditor's official channel.
- Ask for the lump-sum discount and options with a down payment and installments. Older debts usually get bigger discounts.
- Compare the total paid, not just the installment.
Full guide in how to negotiate debt with a bank.
6Close the deal in writing
- Before paying, get an agreement with the total amount, installments, due dates and which debts it settles.
- Confirm in the agreement when the creditor will request removal of your name.
- Only pay a boleto or Pix generated in the official channel, with the creditor as payee, and keep every receipt.
7Don't pay for “name cleaning”
- A correct record only leaves with payment or a deal with the creditor, or after 5 years.
- Be wary of anyone charging upfront to “clean your name” without paying the debt, promising a court “injunction” or asking for passwords and codes.
- If the record is wrong, disputing it is free at the bureau, the creditor, Procon or consumidor.gov.br.
8Paid? Check that your name is removed
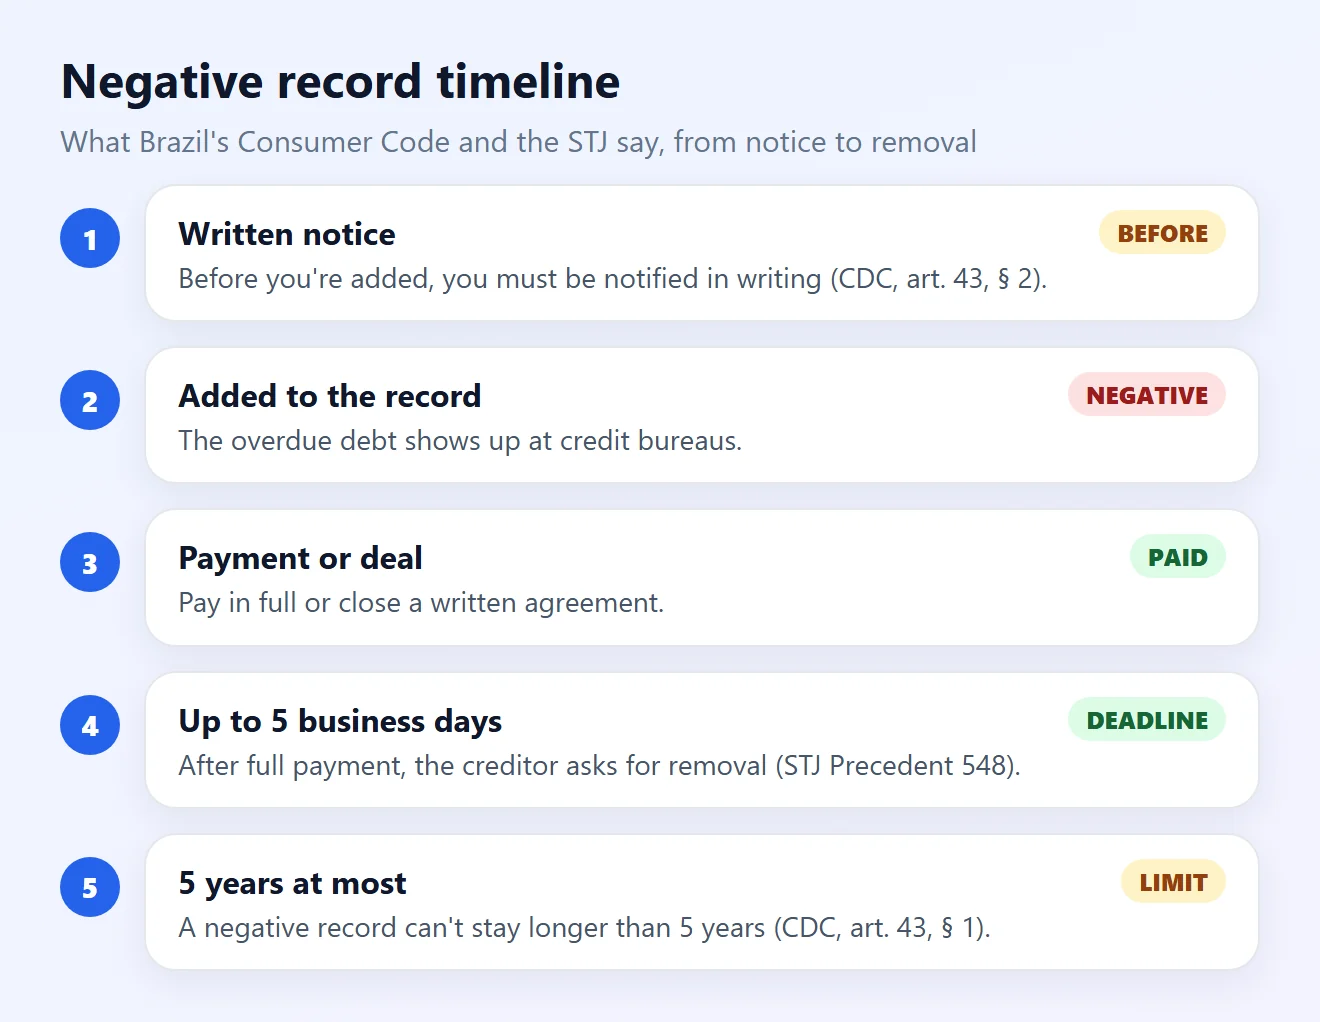
- Under STJ Precedent 548, after full payment the creditor must request removal within 5 business days.
- In an installment deal, follow the deadline written in the agreement.
- Check the bureaus again after that deadline. If your name is still there, send the receipt to the creditor, get a protocol number and, if that fails, complain to Procon or consumidor.gov.br.
Your credit score may take a little longer to rise. Paying bills on time helps.
9Notary protest? Cancel it at the notary
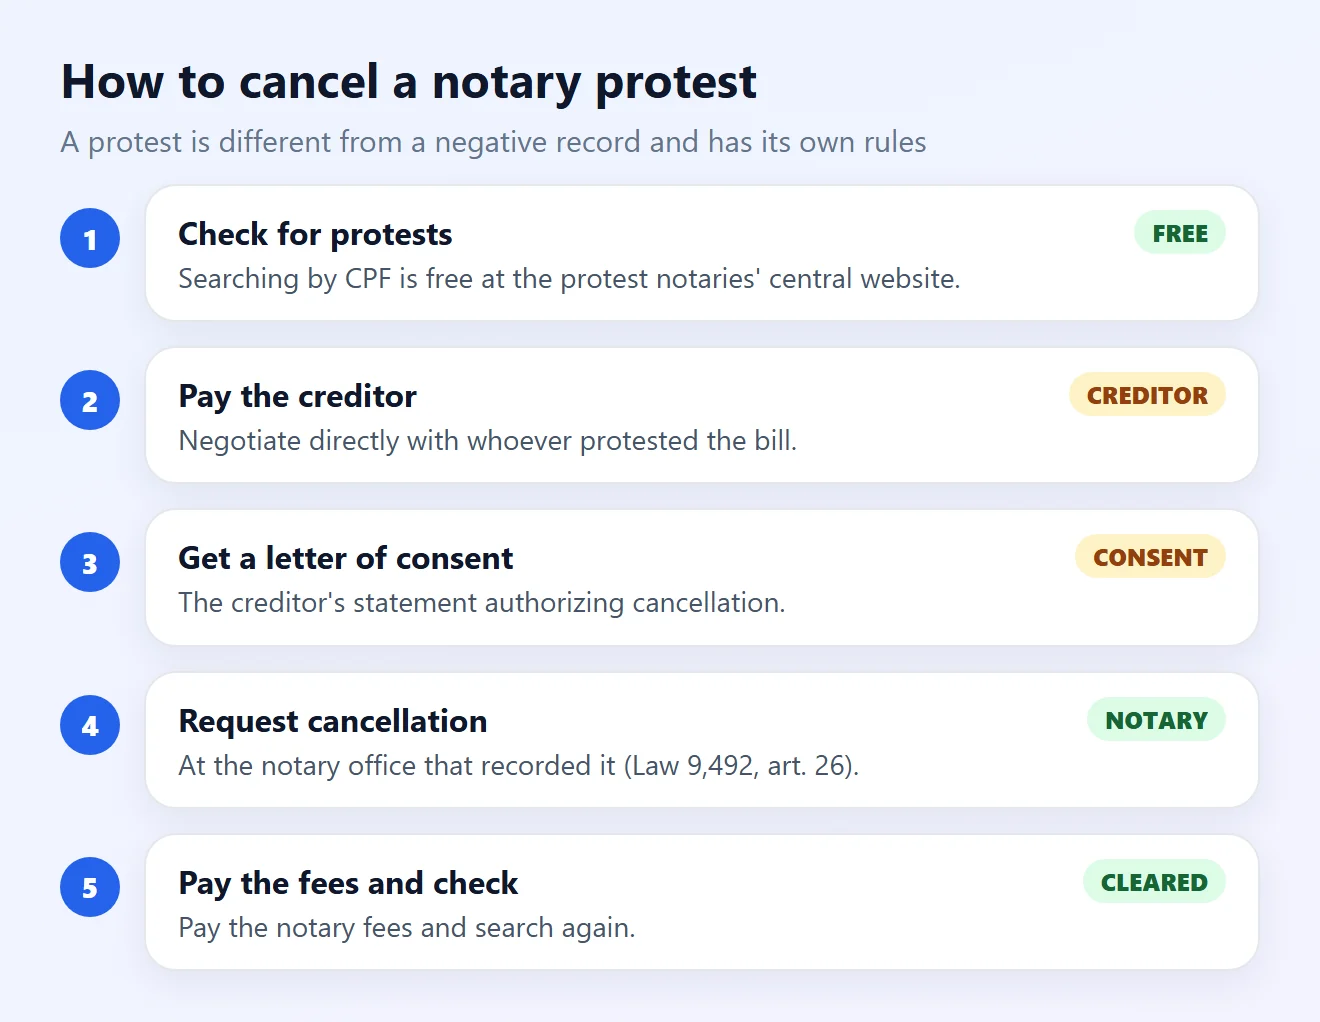
A protest is recorded at a protest notary office (tabelionato de protesto) and doesn't go away just by paying the creditor.
- Search for free by CPF at the protest notaries' central website (pesquisaprotesto.com.br).
- Pay or negotiate with the creditor and ask for a letter of consent (carta de anuência) authorizing cancellation.
- Request cancellation at the notary with the original bill or the letter of consent (Law 9,492, art. 26) and pay the notary fees.
10Understand the 5-year limit
- Under the CDC (art. 43, § 1), negative information can't stay in credit databases for more than 5 years.
- Once the right to collect is time-barred, databases can no longer report the debt in a way that blocks credit (CDC, art. 43, § 5). For contract debts, the limitation period is usually 5 years (Civil Code, art. 206, § 5, I).
- The debt doesn't disappear: the creditor may still offer a deal, and that bank may deny you new credit based on your history with it.
If your debts don't fit your income, learn about Brazil's over-indebtedness law.
Situation and what to do
| Situation | What to do | Step |
|---|---|---|
| Denied credit without knowing why | Check every bureau and Registrato | 1 and 2 |
| A debt that isn't yours | Dispute it, police report, Procon | 3 |
| Correct debt and money to pay | Ask for a lump-sum discount and a written deal | 5 and 6 |
| Paid, but the record is still there | Demand removal after 5 business days | 8 |
| Protested bill | Letter of consent and cancellation at the notary | 9 |
| Record older than 5 years | Ask the bureau to remove it | 10 |
Frequently asked questions
How do I know if I have a negative credit record in Brazil?
Check your CPF for free on the official website or app of each credit bureau: Serasa, Boa Vista, SPC Brasil and Quod. For bank debts, also check the Central Bank's Registrato.
Do I have to pay to check my CPF?
No. Law 12,414 guarantees free access to your information in credit databases, including your score.
How long does it take for my name to be removed after paying?
Under STJ Precedent 548, the creditor must request removal within 5 business days after full payment. In installment deals, the deadline in the agreement applies.
I was added without notice. Is that allowed?
No. The Consumer Protection Code requires written notice before you're added, and STJ Precedent 359 says the credit database must send it. If there was no notice, complain to the bureau and to Procon.
How long does a debt stay on Serasa?
Five years at most. The Consumer Protection Code (art. 43, § 1) bans negative information for longer than that.
Does the debt stop existing after 5 years?
No. The record leaves the databases, but the debt still exists. The creditor may offer a deal, and the bank may consider its internal history with you.
Are a negative record and a notary protest the same thing?
No. A negative record sits at the credit bureaus. A protest is recorded at a notary office and must be canceled there, with the bill or the creditor's letter of consent.
How do I cancel a notary protest?
Pay the creditor, get a letter of consent and request cancellation at the protest notary office, paying the fees. The rule is in art. 26 of Law 9,492.
Do “name cleaning” companies work?
A correct record only leaves with payment, a deal or after 5 years. Be wary of anyone charging upfront to clean your name without paying the debt. Disputing a wrong record is free.
Is a pending CPF at the Federal Revenue the same as a negative record?
No. A CPF that is pending regularization or suspended is a registration issue at the Receita Federal. A negative record is a debt listed at the credit bureaus.
Related content
More practical solutions in Debt.
Compound Interest on Debt: How to Understand and Prevent Balance Growth
Entenda how to the compound interest aumentam the amount of a debt to the longo of the time, how to identify the encargos cobrados and quais atitudes helpm the reducesir the impact financial.
 15 minutes
How to Get Out of Debt: A Complete Guide to Reorganizing Your Finances
Learn how to sair of the debts with estratégias práticas of organization financial, negotiation of débitos, control of expenses and planning for recuperar your estabilidade financial.
30 minutes
How to negotiate debt with a bank
Learn how to negotiate debt with a bank safely, compare offers, reduce interest, and organize installments without compromising your budget.
15 minutes
Sources
- Planalto: Consumer Protection Code, Law 8,078/1990, art. 43 (in Portuguese)
- Planalto: Law 12,414/2011 on credit databases, art. 5 (in Portuguese)
- Planalto: Law 9,492/1997 on protests, art. 26 (in Portuguese)
- Planalto: Civil Code, Law 10,406/2002, art. 206 (in Portuguese)
- STJ: creditor has five business days after payment to request removal, basis of Precedent 548 (in Portuguese)
- STJ: prior notice to the debtor, Precedents 359 and 404 (in Portuguese)
- Central Bank of Brazil: Registrato (in Portuguese)
- Consumidor.gov.br: complaints against companies and banks (in Portuguese)
The screens in this guide are illustrations made by Fixfy, with example names and amounts. This content is for information only and isn't legal advice.