

 Debt
 10 steps
Quick answer: is refinancing worth it?
- It's worth it when the new loan has a lower CET (total effective cost) and the total to pay doesn't grow, or when a smaller installment is what keeps you from falling behind.
- Just stretching the term at the same rate lowers the installment but makes the debt much more expensive.
- Credit portability is your right: another bank pays off your debt and you pay it instead, at lower interest and with no transfer cost.
- Before signing, ask for the CET and the calculation statement: the bank must show them (CMN Res. 4,881).
- Be careful when pledging your home or car as collateral: if you fall behind, you can lose it.
What's your case?
Refinancing debt: 10 steps to avoid paying more
1Gather your current loan details
- In the bank's app or customer service, ask for the updated outstanding balance and the contract number.
- Note the monthly interest rate, the CET, the installment amount and how many installments are left.
- Check for collateral (property, vehicle) or payroll deduction (payroll loan).
- See all your bank debts in Brazil's Central Bank Registrato, free, with a silver or gold gov.br account.
2Know the ways to refinance
- Refinance at the same bank: the contract is redone with a new term, new installment and sometimes a new rate.
- Portability: another bank pays off the debt at your bank and you pay it instead, on better terms (step 5).
- Debt consolidation: a cheaper loan pays off several expensive debts, such as credit card and overdraft (step 6).
- Secured or payroll loan: lower interest, but your home, car or salary is on the line (step 7).
3Do the math: a smaller installment isn't a smaller debt
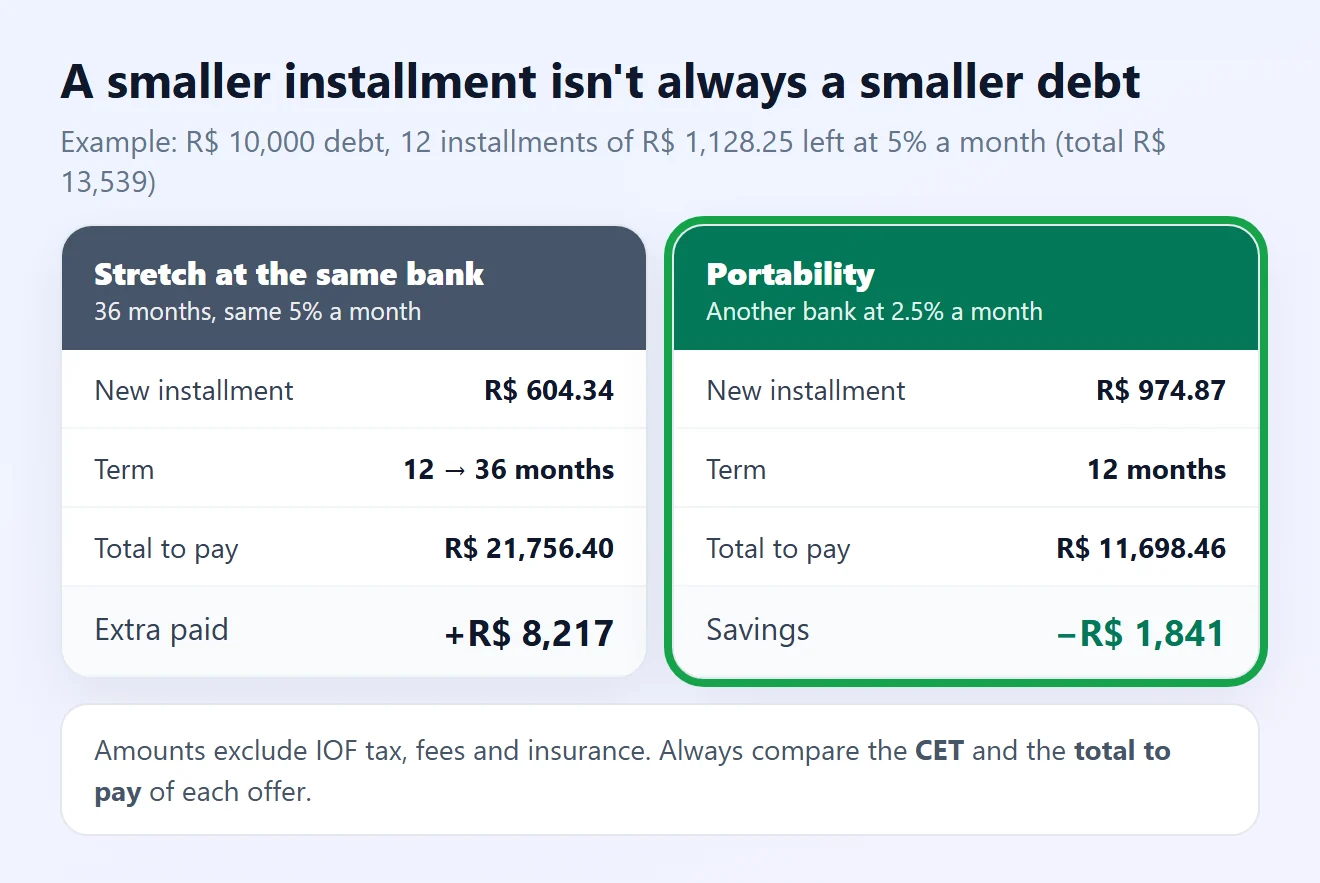
In the example, stretching the debt from 12 to 36 months at the same rate nearly halves the installment but makes you pay R$ 8,217 more. Switching to a lower rate reduces the installment and the total.
- Multiply the new installment by the number of installments and compare it with what you still owe today.
- Use the Central Bank's Calculadora do Cidadão to find the installment or rate of an offer.
- Check the average rate for each type of loan on the Central Bank's Interest Rates page to see if an offer is expensive.
4Compare offers by CET and total
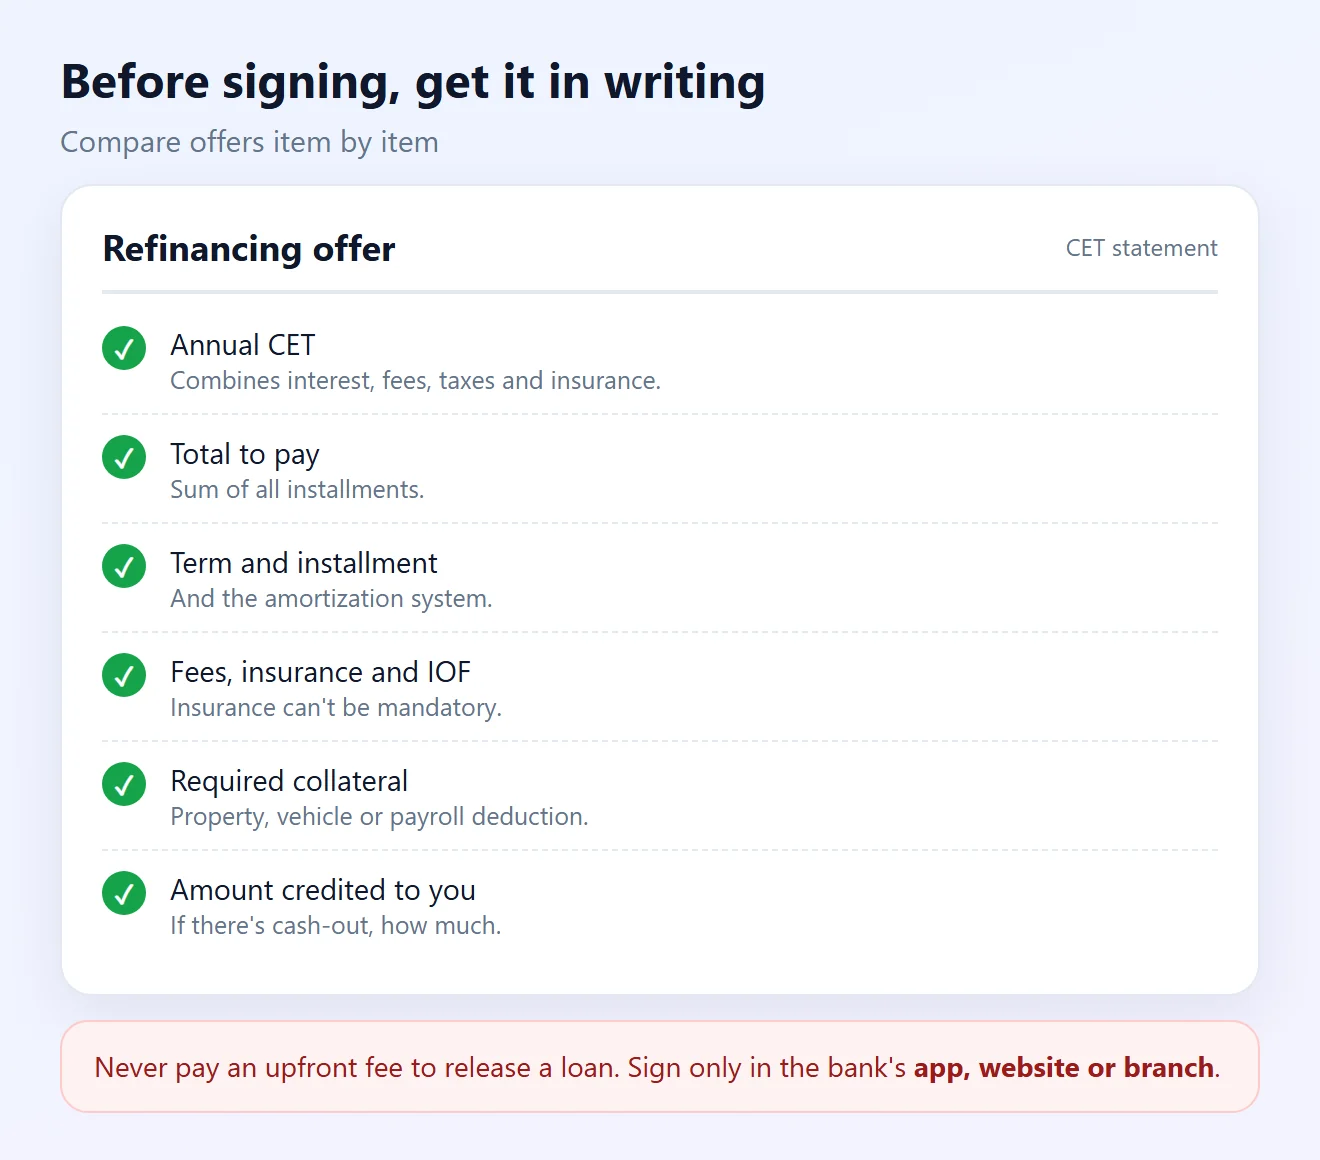
The CET (Custo Efetivo Total) is the annual rate that combines interest, fees, taxes, insurance and other loan costs (CMN Res. 4,881). That's why it compares offers better than the interest rate alone.
- The bank must tell you the CET before you sign and give you the calculation statement, with the amount in reais of each item and the total of the installments.
- Under the Consumer Code (CDC, art. 52), you have the right to know the effective annual rate, the number of installments and the total amount to pay.
- Insurance or another product can't be a condition for the loan: that's tying, banned by the CDC (art. 39, I).
5Request portability to another bank
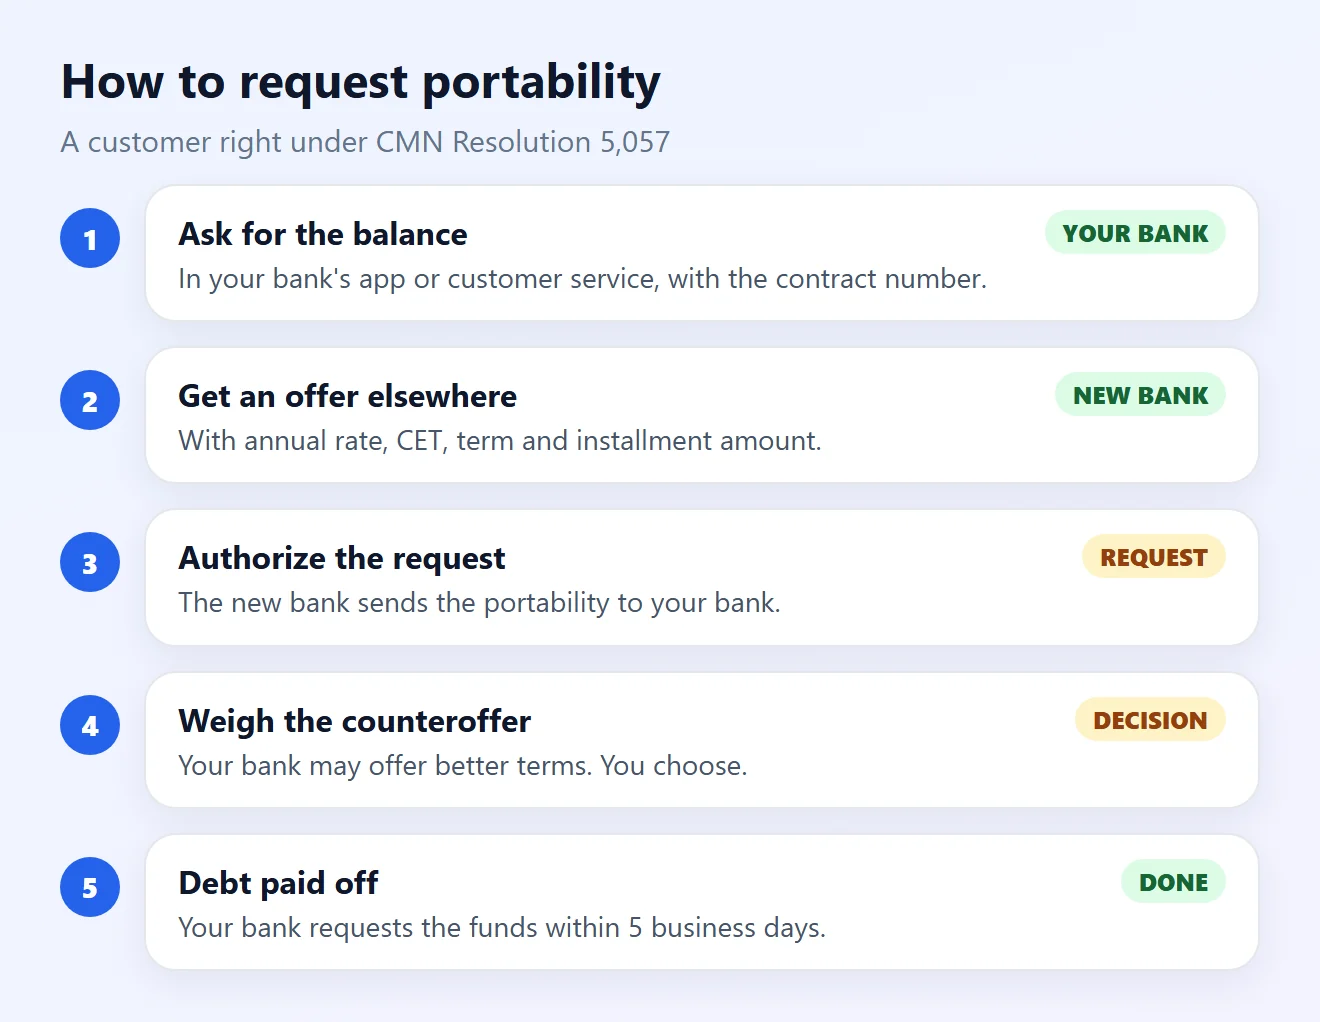
Portability is a customer right, and your current bank must accept it when you ask (CMN Res. 5,057). It covers loans, financing, overdraft and credit card bill balances.
- Ask the new bank for an offer: it must show the annual rate, CET, term, amortization system and installment amount.
- Formally authorize the request. The new bank sends it to your bank.
- Your bank has up to 5 business days (3 business days through Open Finance) to request the funds and settle the debt.
- The amount and term at the new bank can't exceed the outstanding balance and the remaining term (unless the loan type changes).
- If the new installment is higher, the new bank needs your formal agreement.
- The costs of exchanging information and transferring funds can't be charged to you.
Your bank may make a counteroffer to keep you. Compare the CET of both and choose. You can withdraw before the payoff.
6Swap expensive debt for cheaper debt
- Revolving credit card debt and overdrafts are among the most expensive types of credit. Paying them off with a lower-interest loan usually cuts the cost.
- Use the new money only to pay off those debts, directly to the creditor, and get a payoff receipt.
- Then lower your card and overdraft limits so you don't use them again.
Without discipline, consolidation becomes two debts: the new loan and the card back on revolving credit.
7Think twice before pledging collateral
Secured loans have lower interest because the bank takes less risk. You take the risk instead:
- Property as collateral (fiduciary lien): with an overdue installment, the registry office notifies you; without payment within 15 days, ownership passes to the creditor (Law 9,514/1997, art. 26).
- Vehicle as collateral: once default is proven, the creditor can seek repossession of the car (Decree-Law 911/1969).
- Payroll loan: the installment comes straight out of your salary or benefit, so you have less income every month.
It only makes sense to pay off much more expensive debts, with an installment that comfortably fits your budget.
8Beware of cash-out and offers by message
- Refinancing with cash-out releases extra money but raises the balance and restarts the term. Only accept it to pay off a more expensive debt.
- Sign only through the bank's app, website or branch. Don't use links received by WhatsApp, SMS or email.
- Never pay an upfront fee to “release” a loan or portability: it's a common scam.
9Pay off or prepay early when you can
- Under the CDC (art. 52, § 2), you can pay off the debt early, fully or partly, with a proportional reduction of interest and other charges.
- The bank can't charge a fee for early payoff (CMN Res. 3,516).
- When prepaying, ask to shorten the term: it usually saves more interest than lowering the installment.
10Use the breathing room to stay out of debt
- Save part of what the smaller installment frees up in an emergency fund.
- Set the due date right after payday.
- If installments still don't fit your income after refinancing, learn about Brazil's over-indebtedness law and contact Procon or the Public Defender's Office.
When refinancing makes sense
| Situation | Worth it? | What to do |
|---|---|---|
| Another bank offers a lower CET | Yes | Request portability (step 5) |
| Revolving card or overdraft debt | Usually yes | Consolidate into cheaper credit (step 6) |
| Installment doesn't fit and you'll fall behind | Can be | Stretch as little as possible and compare the total (step 3) |
| Only the term grows, same rate | Usually not | Negotiate a lower rate or seek portability |
| Requires home or car for a small debt | Risky | Consider other options (step 7) |
| Offer with cash-out, insurance and fees | Careful | Compare the CET without extras (steps 4 and 8) |
Frequently asked questions
Is refinancing debt worth it?
It is when the new loan's CET is lower and the total to pay doesn't rise, or when a smaller installment prevents late payments. Just stretching the term at the same rate greatly increases the total paid.
What's the difference between refinancing and portability?
In refinancing, the contract is redone, usually at the same bank. In portability, another bank pays off your debt and you start paying it, on better terms.
Can the bank refuse portability?
No. Under CMN Resolution 5,057, the original bank must guarantee portability when the customer asks. It can make a counteroffer, and you choose.
Does portability cost anything?
The costs of exchanging information and transferring funds between banks can't be passed on to you. Check whether the new offer includes fees or insurance in the CET.
How long does portability take?
After the request, the original bank has up to 5 business days (3 business days through Open Finance) to request the funds from the new bank. For mortgages, the steps include registration at the registry office.
Can I extend the term with portability?
Not within the same loan type: the term and amount can't exceed the remaining term and outstanding balance. If portability moves to another loan type, the term limit doesn't apply.
What is the CET and why should I check it?
It's the annual rate that combines interest, fees, taxes, insurance and loan costs. The bank must disclose it before you sign, along with the calculation statement.
Do I have to buy insurance to refinance?
No. Making the loan conditional on buying another product is tying, a practice banned by the CDC (art. 39, I). Ask for the offer without insurance and compare.
If I pay off early, do I pay less interest?
Yes. The CDC guarantees early payoff, in full or in part, with a proportional reduction of interest, and the bank can't charge a fee for it.
Can I refinance with a negative credit record?
It depends on each bank's assessment. With a negative record, offers usually require collateral or payroll deduction. First, see how to negotiate your debt with the bank.
Related content
More practical solutions in Debt.
Compound Interest on Debt: How to Understand and Prevent Balance Growth
Entenda how to the compound interest aumentam the amount of a debt to the longo of the time, how to identify the encargos cobrados and quais atitudes helpm the reducesir the impact financial.
 15 minutes
How to Get Out of Debt: A Complete Guide to Reorganizing Your Finances
Learn how to sair of the debts with estratégias práticas of organization financial, negotiation of débitos, control of expenses and planning for recuperar your estabilidade financial.
30 minutes
Negative Credit Record in Brazil: How to Check and Resolve Outstanding Debts
Learn how to check for a negative credit record in Brazil, identify outstanding debts, negotiate with creditors, and track the regularization of your CPF safely.
15 minutes
Sources
- Central Bank of Brazil: CMN Resolution 5,057/2022 (credit portability, in Portuguese)
- Central Bank of Brazil: what credit portability is (in Portuguese)
- Central Bank of Brazil: CMN Resolution 4,881/2020 (total effective cost, in Portuguese)
- Central Bank of Brazil: CMN Resolution 3,516/2007 (no early payoff fee, in Portuguese)
- Planalto: Consumer Protection Code (Law 8,078/1990), arts. 39 and 52 (in Portuguese)
- Planalto: Law 9,514/1997 (fiduciary lien on property), art. 26 (in Portuguese)
- Planalto: Decree-Law 911/1969 (fiduciary lien on movable assets, in Portuguese)
- Central Bank of Brazil: interest rates by loan type (in Portuguese)
- Central Bank of Brazil: Calculadora do Cidadão, fixed-installment financing (in Portuguese)
- Central Bank of Brazil: Registrato (in Portuguese)
The screens and simulation in this guide are illustrations created by Fixfy. The simulation uses fixed installments (Price table) and doesn't include IOF tax, fees or insurance; the rates in your offer may differ. This content is informational and doesn't replace legal or financial advice.