

 Emergency fund
 10 steps
Quick answer: how to teach children about money
- Talk about money at home and let your children take part in simple family budget decisions.
- Start early with coins and a piggy bank; once they're in school, give an allowance with agreed rules.
- Teach them to split money into spend, save and give and to tell needs from wants.
- Help your child turn a dream into a goal, with an amount, a deadline and a celebration at each stage.
- Protect and teach online: purchase approval in apps, care with ads and scams, and betting banned for under-18s.
What's your case?
Financial education for children: 10 steps
1Talk about money at home and set the example
- Brazil's Central Bank notes that families don't usually sit down together to build a budget. Change that: explain, in age-appropriate language, where money comes from and where it goes.
- Include children in simple choices: the weekend outing, the grocery list, what to cut back on to afford a trip.
- Your example teaches more than talk: comparing prices, waiting before buying and saving are habits children copy.
- You don't need to reveal your salary or worry them about debts; the goal is to show that money is limited and requires choices.
2Young children: coins, piggy bank and waiting
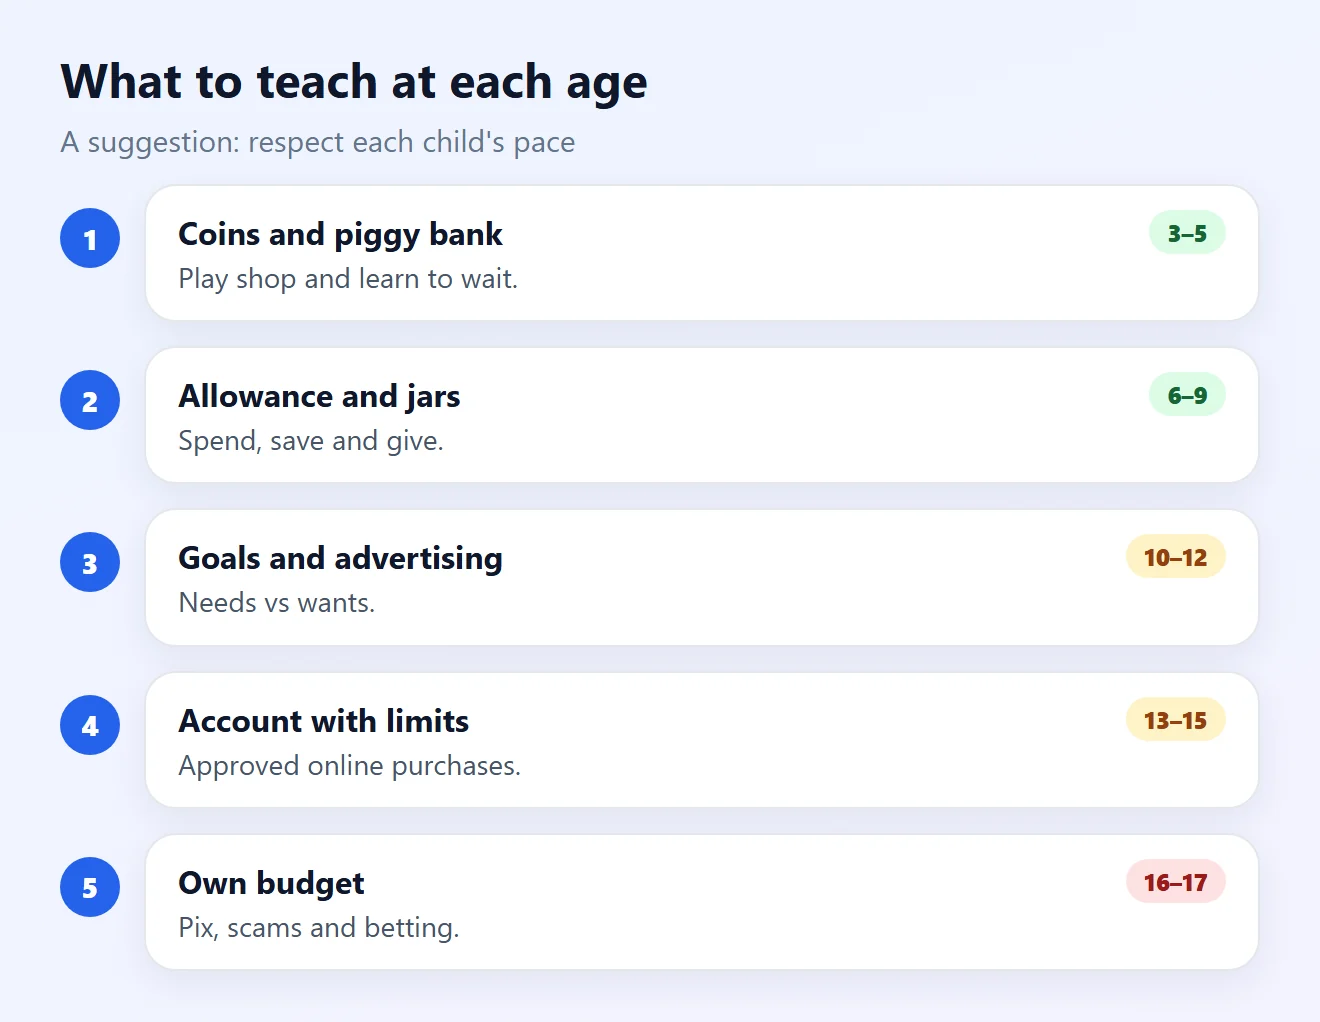
- Show coins and bills and play shop: children learn that everything has a price.
- A clear piggy bank lets them watch the money grow, which helps them see the value of saving.
- Practice waiting: “let's save up and buy it in two weeks” teaches that not everything happens right away.
- The age ranges in the image are a suggestion; respect each child's pace.
3Give an allowance with agreed rules
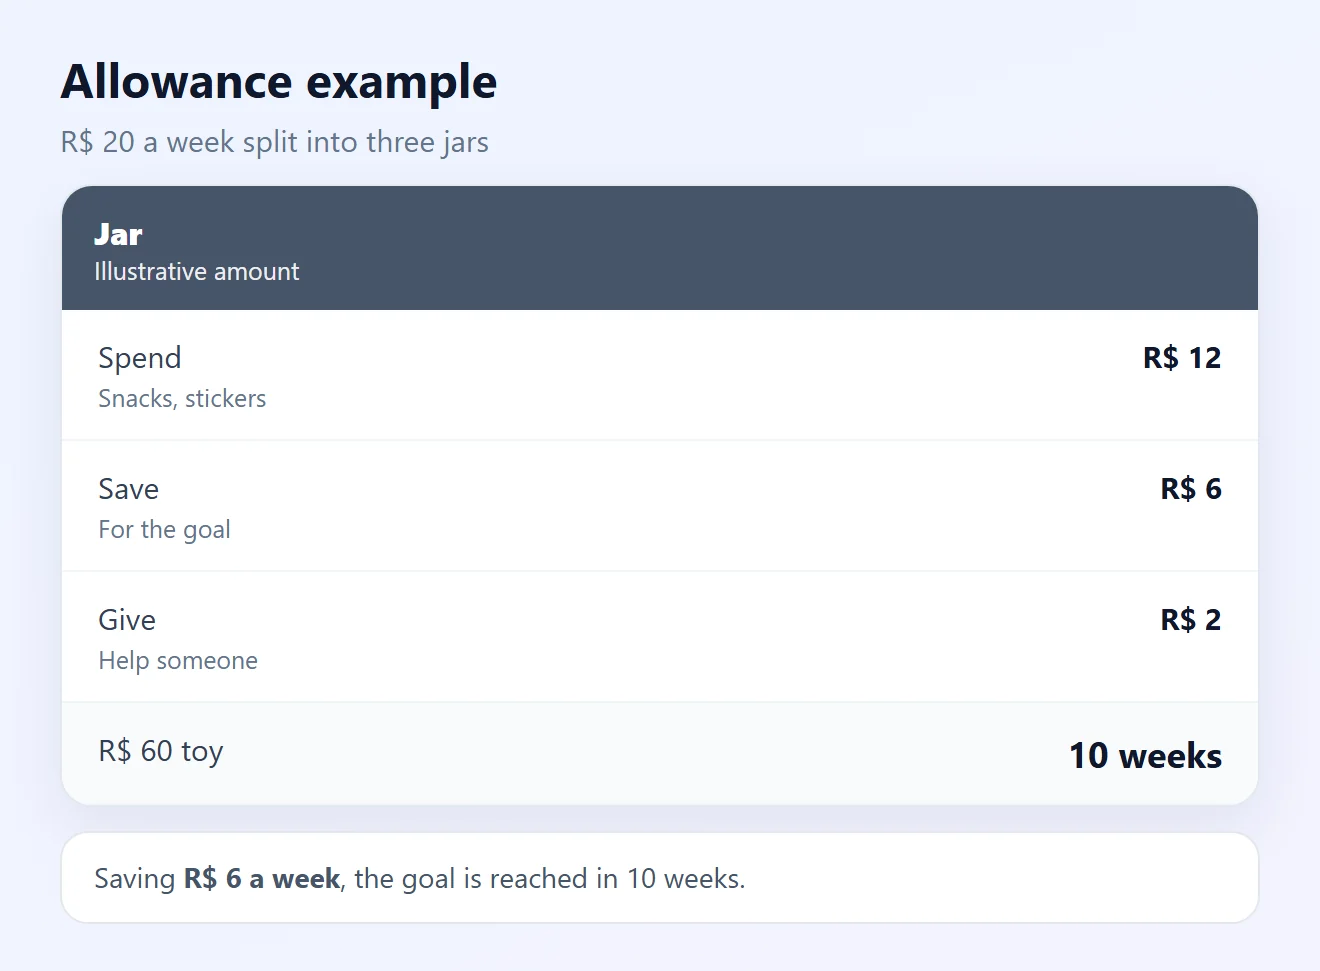
- Pick an amount that fits the family budget and agree on what the allowance covers (snacks, stickers, an outing).
- Pay it on the same day every time, weekly for younger children and monthly for older ones, like a salary.
- Ran out early? Don't pay the next one in advance: feeling the shortfall teaches planning.
- Avoid using the allowance as a punishment or a reward for grades: it's a tool for learning to manage money.
4Split money into spend, save and give
- Use three jars or envelopes: spend (now), save (for a goal) and give (to help someone).
- It's the kids' version of the Central Bank's advice to “give your money a name” and to pay yourself first: set the saving part aside as soon as the money arrives.
- Let your child decide what to do with the spending jar, even if they get it wrong: small mistakes today prevent costly ones later.
5Teach the difference between needs and wants
- A need is what we must have (food, school supplies); a want is what we'd like (the trendy toy). The Central Bank treats this distinction as the basis of conscious consumption.
- When your child asks for something, ask back: “do you need it or want it?”, “how long will you use it?”, “what would you give up instead?”.
- Talk about opportunity cost: spending on one thing means not having that money for another.
- Wants aren't forbidden: they can become a goal (step 6).
6Turn the dream into a goal
- The Central Bank teaches how to turn a dream into a project: know exactly what you want, set an amount and deadline, keep the goal in sight (a photo on the wall), create stages and celebrate each one.
- Example: a R$ 60 toy with R$ 6 saved per week is reached in 10 weeks. Make a chart to color in each week.
- Show the trade-off over time: waiting and saving costs less than buying now on installments, which charge interest.
- If the family has a goal (a trip, for example), show everyone the progress.
See also how to set a financial goal.
7Take the lesson to the supermarket
- The Central Bank recommends agreeing in advance with children on what will be bought and calls it a chance to teach them about money.
- Write the list together and give them a task: compare two brands or find the cheapest product per kilo.
- Point out that children's products sit at children's eye level on purpose, to catch their attention.
8Ads, games and in-app purchases
- Talk about advertising: ads, influencers and unboxing videos want to sell. Brazil's Consumer Protection Code considers advertising that takes advantage of a child's lack of judgment and experience abusive.
- “Free” games sell coins, skins and items: agree on a limit and explain that it's real money.
- iPhone/iPad: turn on “Ask to Buy” in Settings > Family > your child's name. Every purchase or download needs your approval.
- Android: in the Google Play app, tap your profile picture > Payments and subscriptions > Purchase verification, and require authentication for all purchases. Accounts supervised with Family Link also have content and purchase controls.
- Don't keep a saved card on a phone or console your child uses without a purchase password.
9Teenagers: account, card, Pix and scams
- Many banks offer accounts or cards for minors linked to a parent's account. Check the fees and controls in the bank's app before opening one.
- Pay the allowance into the account and let your teen build their own monthly budget.
- Adjust the Pix limit and notifications in the bank's app to keep track of spending.
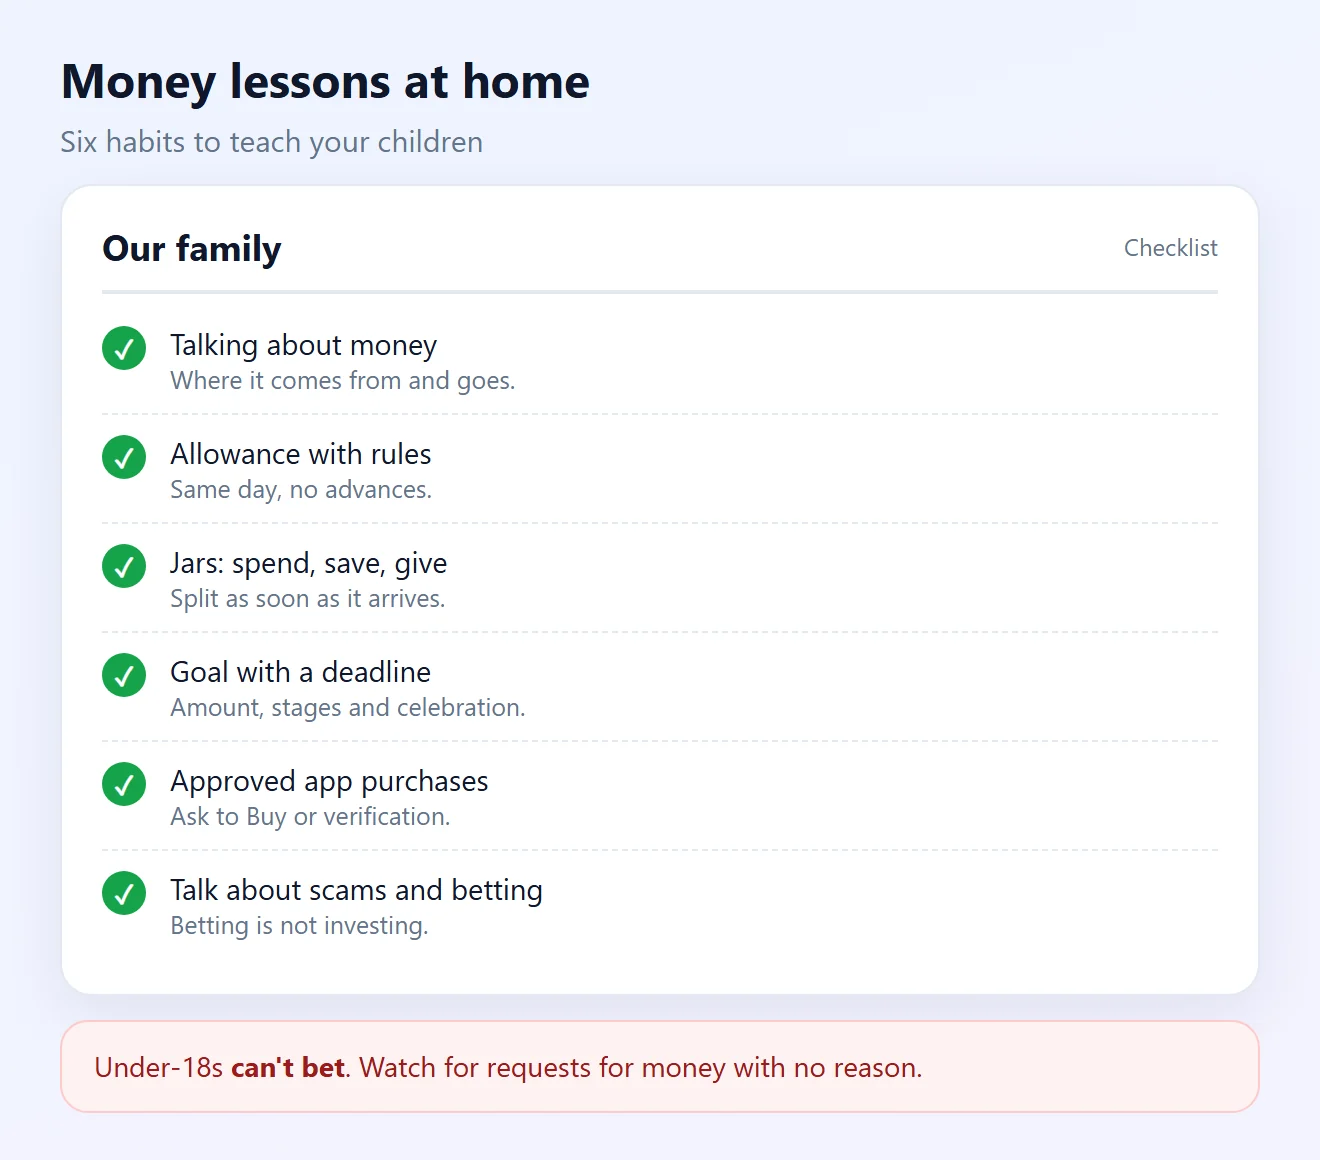
- Teach the golden rules against scams: never share a password or a code received by SMS, and distrust prizes, “easy jobs” and requests for money from friends by message.
- Explain credit and interest before the card arrives: installments don't make anything cheaper.
10Talk about betting: it's not an investment
- Law 14,790/2023 bans under-18s from betting on betting sites, and ads must carry an age-restriction warning.
- On 25/09/2026, Provisional Measure 1,394 banned offering and advertising fixed-odds betting in Brazil; it still has to be reviewed by Congress. Even so, illegal sites keep popping up.
- The Central Bank reminds that betting and lotteries are not investments: they depend on luck and can take all the money.
- Watch for signs: requests for money with no reason, use of your card, secrecy with the phone, influencer “tips” about games that pay out.
- Ask whether your child's school takes part in Aprender Valor, a free Central Bank program that brings financial education to public schools.
Situation and what to do
| Situation | Likely cause | What to do |
|---|---|---|
| Asks for everything | Can't tell needs from wants | Ask “need or want?” (step 5) |
| Spends the allowance on day one | No split and no goal | Jars and no advances (steps 3 and 4) |
| Tantrums at the supermarket | Shopping without agreement | Make the list together first (step 7) |
| In-game purchases without permission | Saved card, no approval | Ask to Buy or purchase verification (step 8) |
| Wants something expensive now | Want without a plan | Turn it into a goal with stages (step 6) |
| Interest in betting or “games that pay” | Ads and influencers | Talk and track spending (step 10) |
Frequently asked questions
At what age should financial education start?
Early. Around ages 3 to 5, children can already play with coins, use a piggy bank and learn to wait. The content grows with age.
How much allowance should I give?
There's no official amount. Choose one that fits the family budget and covers what the allowance is meant for, and review it as your child grows.
Weekly or monthly allowance?
Weekly works better for younger children, who can't plan long periods yet. For teenagers, a monthly allowance teaches budgeting.
Should I cut the allowance as a punishment?
It's best not to mix them. The allowance is for learning to manage money; using it as a reward or punishment shifts the focus.
How do I teach my child to save?
Help them choose a concrete goal, set the saving part aside as soon as they receive money and track progress on a chart, celebrating each stage.
How do I stop purchases in games and apps?
On iPhone and iPad, turn on “Ask to Buy” in Family Sharing. On Android, require verification for all purchases on Google Play or use Family Link.
Can a teenager have a bank account?
Many banks offer accounts or cards for minors linked to a parent. Rules and fees vary, so check directly with the bank.
Can minors bet on betting sites in Brazil?
No. Law 14,790/2023 bans bettors under 18, and in September 2026 a provisional measure banned fixed-odds betting in the country.
Do schools teach financial education?
Many public schools in Brazil use Aprender Valor, a Central Bank program with financial education projects linked to school subjects. Ask your child's school.
Do I need to tell my children my salary?
No. What matters is showing that money is limited, that the family makes choices and that saving is part of the plan.
Related content
More practical solutions in Emergency fund.
How to Build an Emergency Fund From Scratch
Learn how to build an emergency fund from scratch, estimate a realistic target, save consistently, and keep the money available for unexpected essential expenses.
 20 minutes
How to build an emergency fund when self-employed
Aprenda the montar a fund of emergency mesmo with income variável. Veja quanto guardar, as definir goals and onde manter the money for lidar with períodos of baixa demanda or unexpected events.
15 minutes
How to plan financially for retirement
Learn how to plan the retirement financial organizando objetivos, expenses future, sources of income and estratégias of longo term for build more safety financial.
30 minutes
Sources consulted
- Central Bank of Brazil: Financial Education Notebook, Module 1 – Our Relationship with Money (PDF, in Portuguese)
- Central Bank of Brazil: Financial Education Notebook, Module 4 – Planned and Conscious Consumption (PDF, in Portuguese)
- Central Bank of Brazil: Financial Education Notebook, Module 5 – Active Saving and Investment (PDF, in Portuguese)
- Central Bank of Brazil: Aprender Valor program (in Portuguese)
- Planalto: Consumer Protection Code (Law 8,078/1990), art. 37 (in Portuguese)
- Planalto: Law 14,790/2023 on fixed-odds betting (in Portuguese)
- Federal Senate: Provisional Measure 1,394/2026 (in Portuguese)
- Apple Support: Ask to Buy
- Google Play Help: Purchase verification
- Google Play Help: Content restrictions and Family Link
The images on this page are illustrations created by Fixfy. The allowance amounts and age ranges are examples, not official recommendations. The legal status of betting may change once Congress votes on the provisional measure.