

 Emergency fund
 10 steps
Quick answer: how to set a financial goal that works
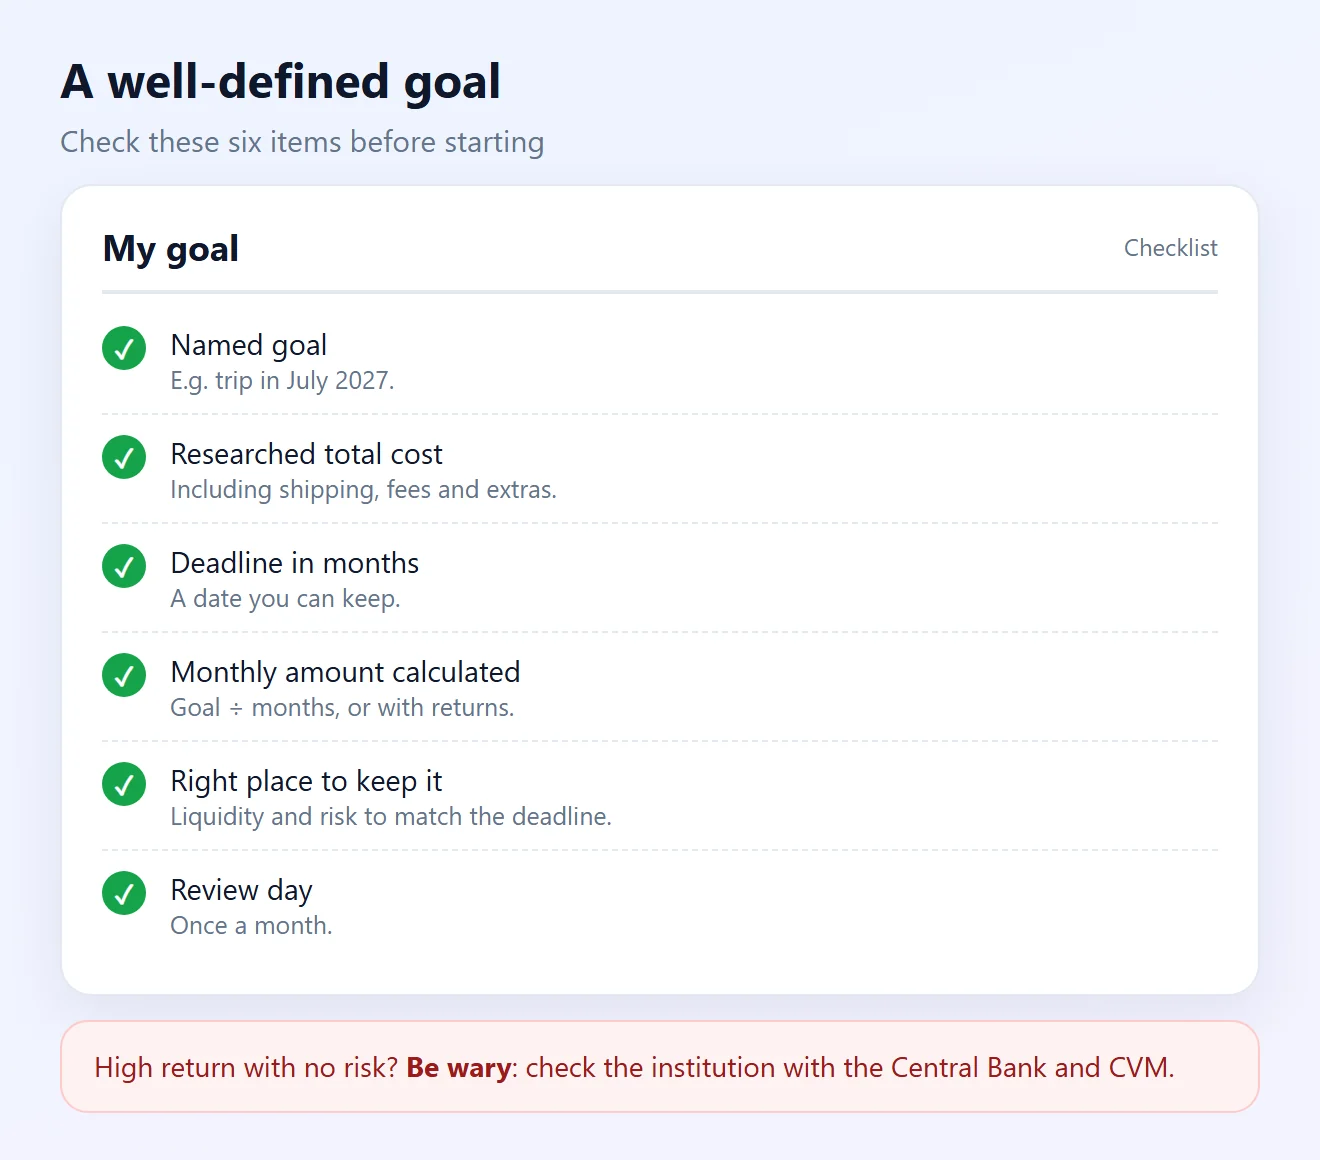
- Give your money a name: pick a concrete goal (trip, car, course, paying off a debt) and write it down.
- Work out how much it costs (including extras) and in how many months you want to get there.
- Divide the amount by the months to know how much to save each month; the Central Bank of Brazil's Citizen Calculator does the math with returns.
- Pay yourself first: set aside the goal amount the day your salary arrives, not at the end of the month.
- Keep it somewhere that matches the deadline: money needed soon calls for high liquidity and low risk. Review the goal every month.
What's your case?
How to set a financial goal: 10 steps
1Choose the goal and give your money a name
- The Central Bank of Brazil recommends “giving your money a name”: knowing what and when you'll spend it helps you choose where to keep it.
- Swap “I want to save money” for something concrete: “beach trip in July”, “new laptop”, “car down payment”.
- Write the goal down and keep it visible: on your phone, the fridge, or as the name of a bank account or savings “box”.
- Personal goals work better when the family takes part in the decision.
2Find out what the goal really costs
- Research the real price in more than one place, not a guess.
- Add costs that are often left out: shipping, paperwork, insurance, fees, lodging and food on a trip.
- For long goals, remember prices rise with inflation: review the amount every year.
- Goal too big? Split it into stages (for example, the down payment first, then the rest).
3Set the deadline in months
- Pick a date: “by December 2027” becomes 13 months, and a number of months lets you do the math.
- The deadline decides where to save: a trip in six months needs a highly liquid investment, while a home takes years, the Central Bank explains.
- A deadline that's too short means monthly amounts that don't fit, and people give up. Choose one you can keep.
4Get the order right: emergency fund first
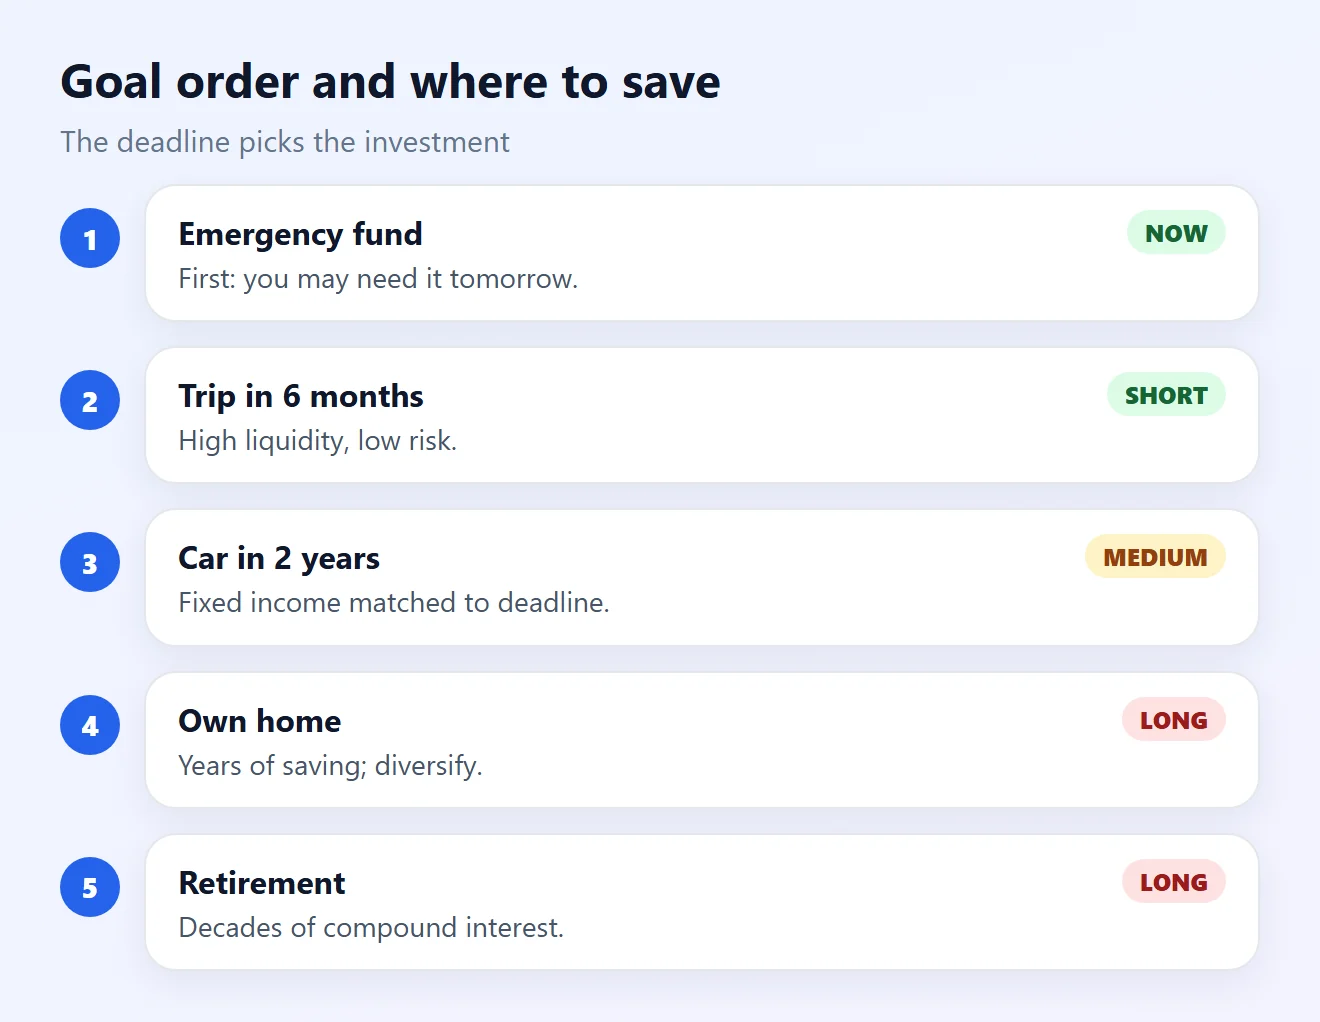
- Before other goals, build an emergency fund. Without it, any surprise makes you dip into the goal money or your overdraft.
- Have high-interest debt (credit card, overdraft)? Paying it off is usually the most worthwhile goal.
- With several goals, keep each one in a separate place and decide how much goes to each.
5Work out how much to save each month
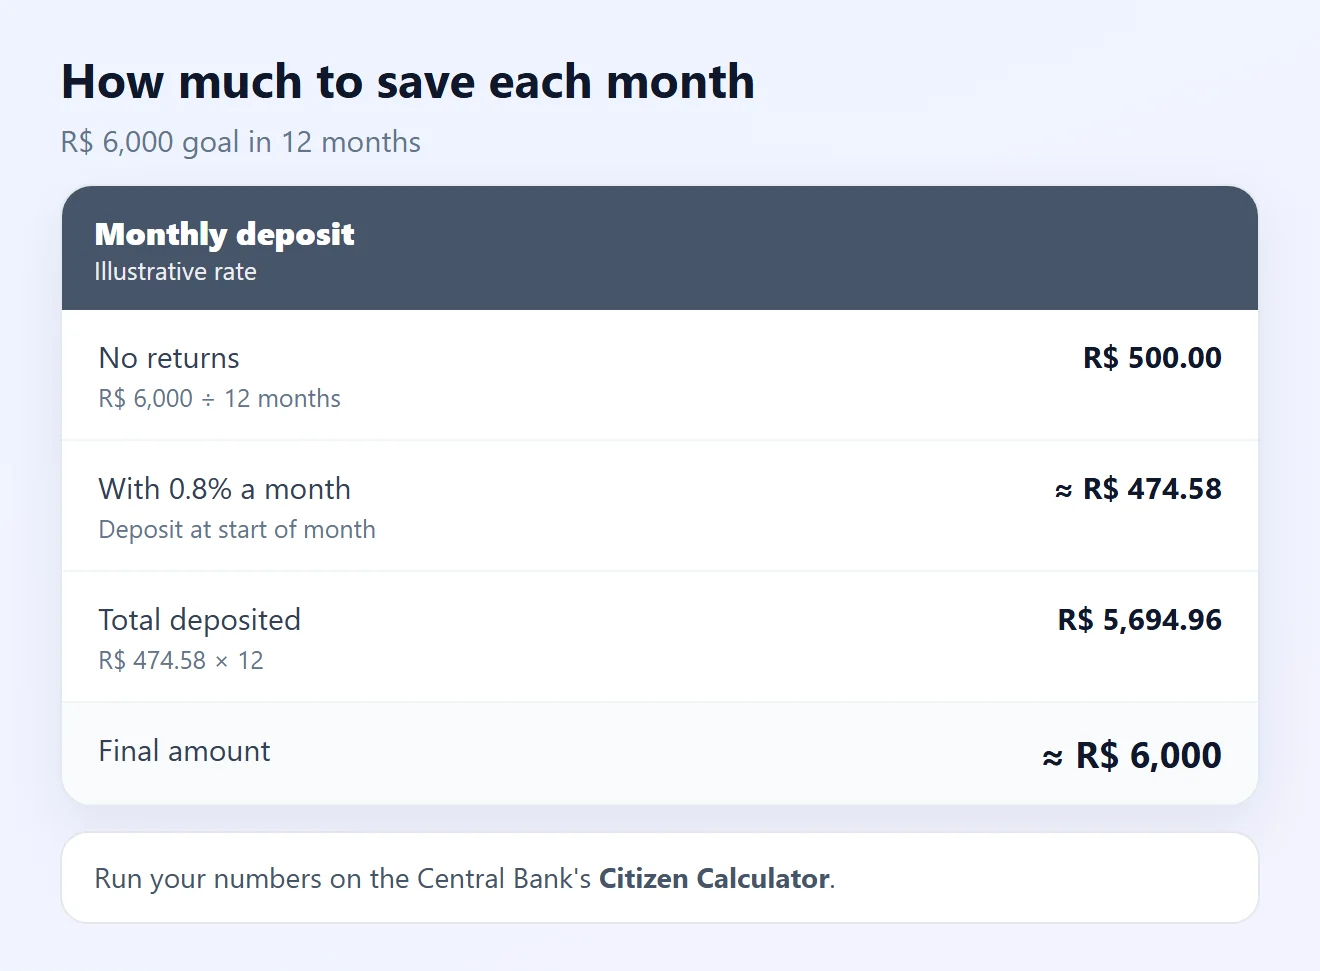
- Simple math: goal amount ÷ number of months. R$ 6,000 in 12 months = R$ 500 a month.
- With investment returns, the monthly deposit is a bit lower. The Central Bank's Citizen Calculator does this under “Investment with regular deposits”: enter the months, monthly rate and final amount.
- Use a conservative rate and remember net returns depend on fees and taxes.
6Fit the goal into your budget
- Write down income and spending for the month to see what's really left.
- If the monthly amount doesn't fit, cut spending that matters little to you or extend the deadline.
- Extra money (13th salary, tax refund, side jobs) can bring the goal forward.
7Pay yourself first
- The Central Bank recommends setting savings aside as soon as your salary comes in, rather than waiting for what's left at month-end.
- Schedule an automatic transfer for payday: you don't have to remember or decide again.
- Treat the goal amount as a fixed bill, like rent or electricity.
8Choose where to keep it based on the deadline
- Every investment has liquidity (how fast it turns into cash), risk and return. The three are never all great at once, the Central Bank warns.
- Short goals or an emergency fund: prefer high liquidity and low risk, such as a savings account (caderneta de poupança), Tesouro Selic or a CDB with daily redemption.
- In Brazil, savings, CDB, LCI and LCA are covered by the FGC or FGCoop up to R$ 250,000 per taxpayer ID per institution.
- Tesouro Direto government bonds are low risk if held to maturity; selling early can mean a loss.
- Compare net returns: management fees, custody fees and tax change the result.
9Protect the goal from promises and gambling
- Distrust high returns with no risk: high liquidity, low risk and high return never come together in a serious investment.
- Before investing, check that the institution is authorized by the Central Bank and, for funds and stocks, registered with the CVM.
- Betting and lotteries are not investments: they depend on luck and can take all your money.
- Cryptocurrencies are neither issued nor guaranteed by the Central Bank and swing a lot: they don't suit money with a deadline.
10Track it monthly and adjust
- Set a day each month to check how much you've saved and how much is left.
- Fallen behind? Adjust the monthly amount, the deadline or the size of the goal, but keep saving.
- Had to use the money? Restart with a smaller amount and pick up the pace again.
- Celebrate each milestone (25%, 50%, 75%): seeing progress keeps you motivated.
For travel goals, see also how to save money for travel.
Situation and what to do
| Situation | Likely cause | What to do |
|---|---|---|
| I save but the money disappears | Goal with no name or separate place | Name it and separate it (steps 1 and 8) |
| Nothing left at month-end | Saving only what's left over | Pay yourself first (step 7) |
| Monthly amount doesn't fit | Short deadline or tight budget | Extend the deadline or cut spending (step 6) |
| An emergency wiped out the goal | No emergency fund | Build the fund first (step 4) |
| Money earns little | Wrong investment for the deadline | Compare net returns (step 8) |
| Offer of high guaranteed returns | Possible scam | Check Central Bank and CVM (step 9) |
Frequently asked questions
What is a financial goal?
It's a money objective with a set amount and deadline, such as saving R$ 6,000 in 12 months for a trip. With those three pieces you know how much to save each month.
How do I work out how much to save each month?
Divide the goal amount by the number of months. To include returns, use the Central Bank of Brazil's Citizen Calculator, under “Investment with regular deposits”.
Should I build an emergency fund before other goals?
It's the safest choice. Without one, any emergency forces you to withdraw the goal money or use expensive credit.
Where should I keep money for a short-term goal?
In high-liquidity, low-risk options such as a savings account, Tesouro Selic or a CDB with daily redemption. The Central Bank recommends this kind of investment for money you'll need soon.
What does “pay yourself first” mean?
Setting aside the goal amount as soon as your salary comes in, before other spending, instead of saving only what's left at month-end.
Is my money in savings or a CDB guaranteed?
In Brazil, savings, CDB, LCI and LCA, among others, are covered by the FGC or FGCoop up to R$ 250,000 per taxpayer ID per institution, according to the Central Bank.
Can I have more than one goal at a time?
Yes. Keep each one in a separate place, choose the investment by each goal's deadline and decide how much goes to each one monthly.
What if I can't save the full amount one month?
Save what you can and adjust the deadline or monthly amount. What matters is keeping the habit and reviewing the goal.
Can betting or crypto get me there faster?
They're not advisable. The Central Bank points out that betting and lotteries aren't investments and that cryptocurrencies have no guarantee and swing a lot.
How can I tell if an institution is trustworthy?
Check that it's authorized by the Central Bank of Brazil and, for funds and stocks, registered with the CVM. Distrust high returns with no risk.
Related content
More practical solutions in Emergency fund.
How to Build an Emergency Fund From Scratch
Learn how to build an emergency fund from scratch, estimate a realistic target, save consistently, and keep the money available for unexpected essential expenses.
 20 minutes
How to build an emergency fund when self-employed
Aprenda the montar a fund of emergency mesmo with income variável. Veja quanto guardar, as definir goals and onde manter the money for lidar with períodos of baixa demanda or unexpected events.
15 minutes
Financial Education for Children: How to Teach It Early
Learn how to teach financial education to children and teenagers through practical examples, goals, conscious allowances, and healthy spending habits.
30 minutes
Sources
- Central Bank of Brazil: Financial Education Notebook, Module 5 – Active Saving and Investment (PDF, in Portuguese)
- Central Bank of Brazil: Citizen Calculator – Investment with regular deposits (in Portuguese)
- Central Bank of Brazil: Financial Citizenship (in Portuguese)
- National Treasury: Tesouro Direto (in Portuguese)
The images on this page are illustrations created by Fixfy. The 0.8% monthly rate in the example is illustrative and not an investment recommendation.