

 Emergency fund
 10 steps
Quick answer: emergency fund for the self-employed
- Add up your essential expenses and find your average income over the last 12 months and your weakest month.
- Aim for a fund of 6 to 12 months of expenses: variable income calls for the high end of the range.
- Separate work and personal accounts and pay yourself a fixed “salary” every month.
- From every payment, set aside taxes and INSS first, then a fixed percentage for the fund; in good months, save more.
- In weak months, top up your salary from the fund and refill it in strong months.
What's your case?
Emergency fund for the self-employed: 10 steps
1Add up your personal essential expenses
- Housing, food, household bills, transportation, health, school and minimum payments: what you can't stop paying.
- Leave out work costs (materials, tools, office rent). They belong in the business cash reserve, in step 8.
- Use recent statements instead of guessing.
2Find your average income and weakest month
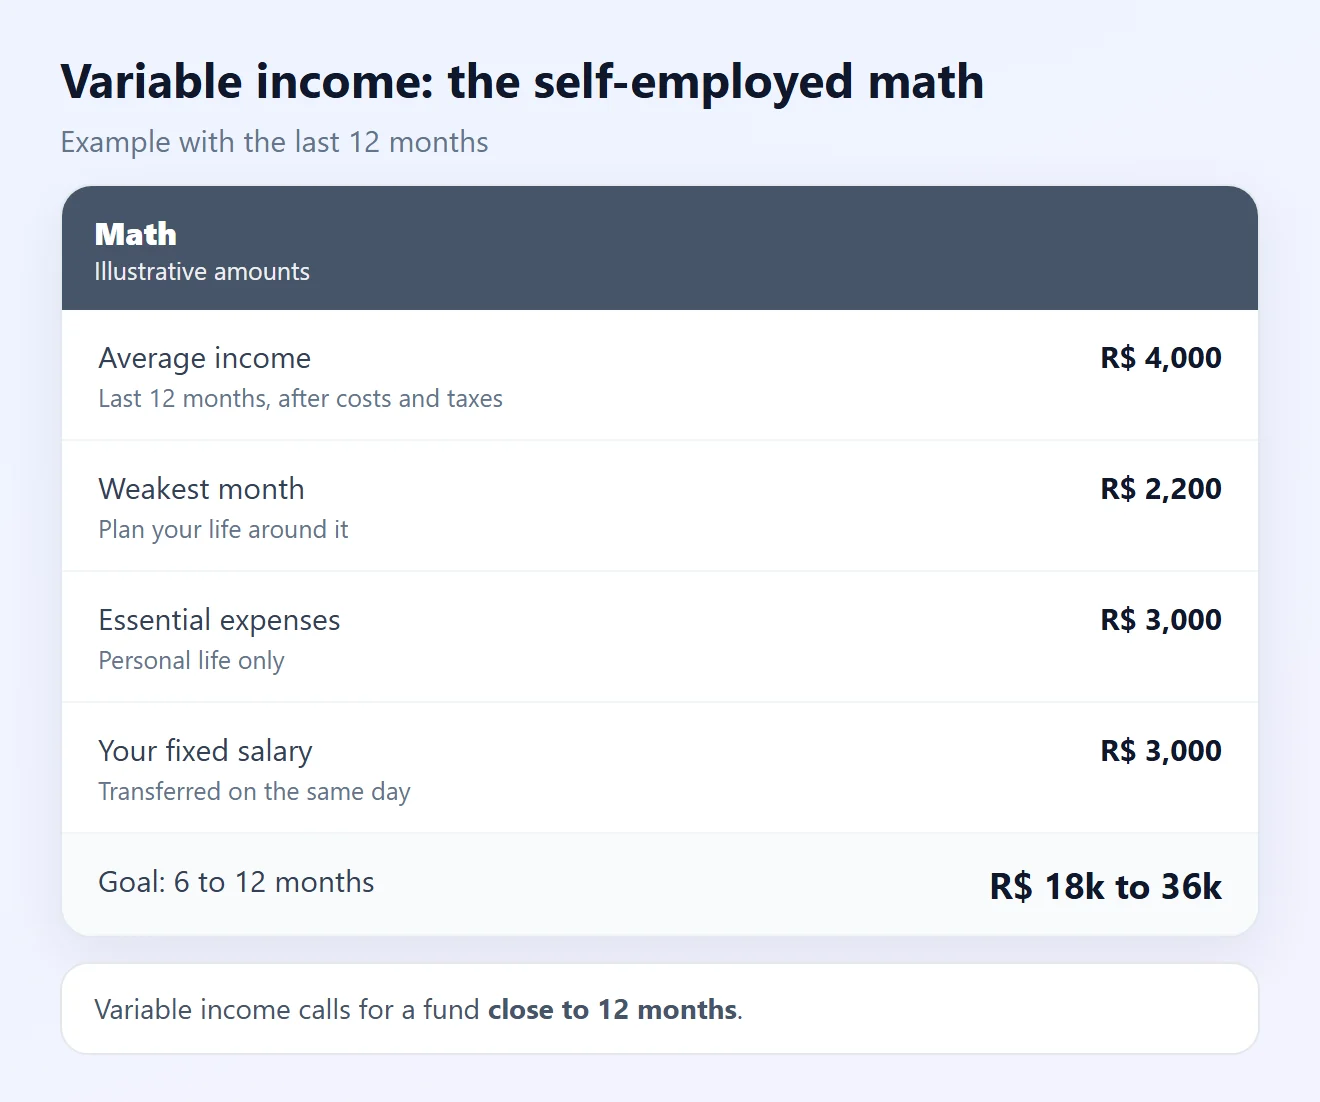
- Add up what actually came in over the last 12 months, after work costs and taxes, and divide by 12.
- Note your weakest month and when it usually happens (holidays, year-end, off-season).
- Plan your life on the lowest income, not on your best month.
3Set the goal: 6 to 12 months of expenses
- The Investor Portal of Brazil's securities regulator (CVM) estimates the fund at 6 to 12 months of expenses and says it depends on whether income is fixed or variable and on how stable your work is.
- Self-employed people have no FGTS or unemployment insurance: the more your income swings and the fewer clients you have, the closer to 12 months.
- With R$ 3,000 of essential expenses, the goal is between R$ 18,000 and R$ 36,000. Start with the first stage: 1 month.
See how to build an emergency fund step by step.
4Separate accounts and pay yourself a fixed salary
- Keep an account just for work, where all client payments go, and another for your personal life.
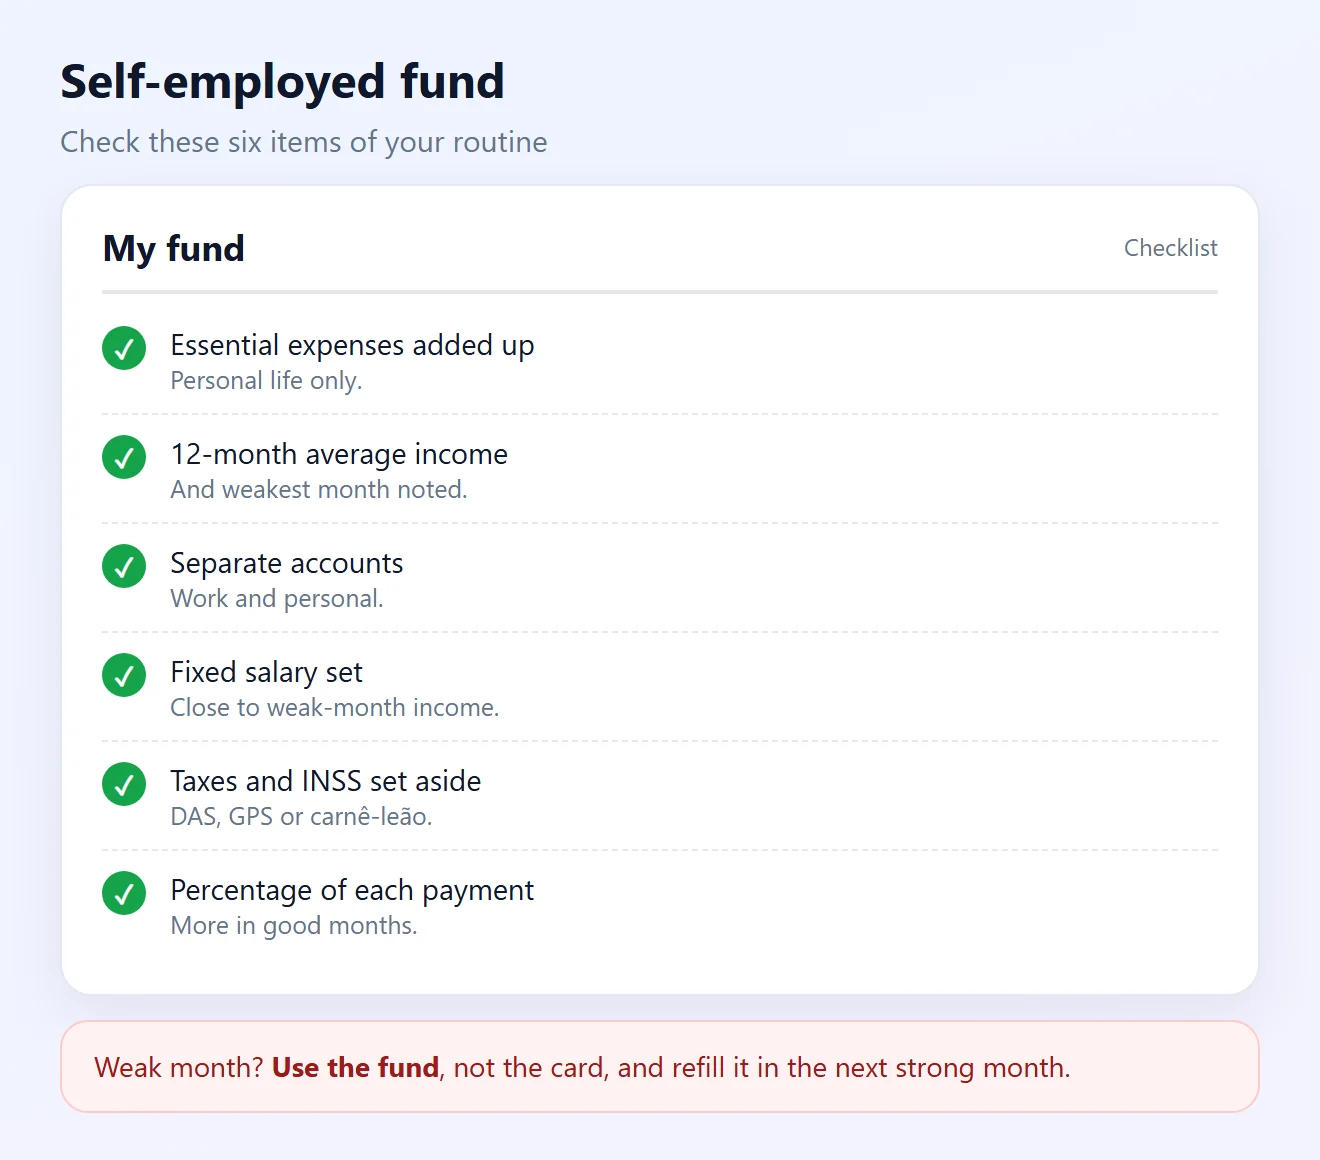
- Set a fixed “salary”, ideally close to your weak-month income, and transfer it on the same day every month.
- What's left in the work account isn't free money: it's taxes due, business costs and the fund.
5Save a percentage of every payment
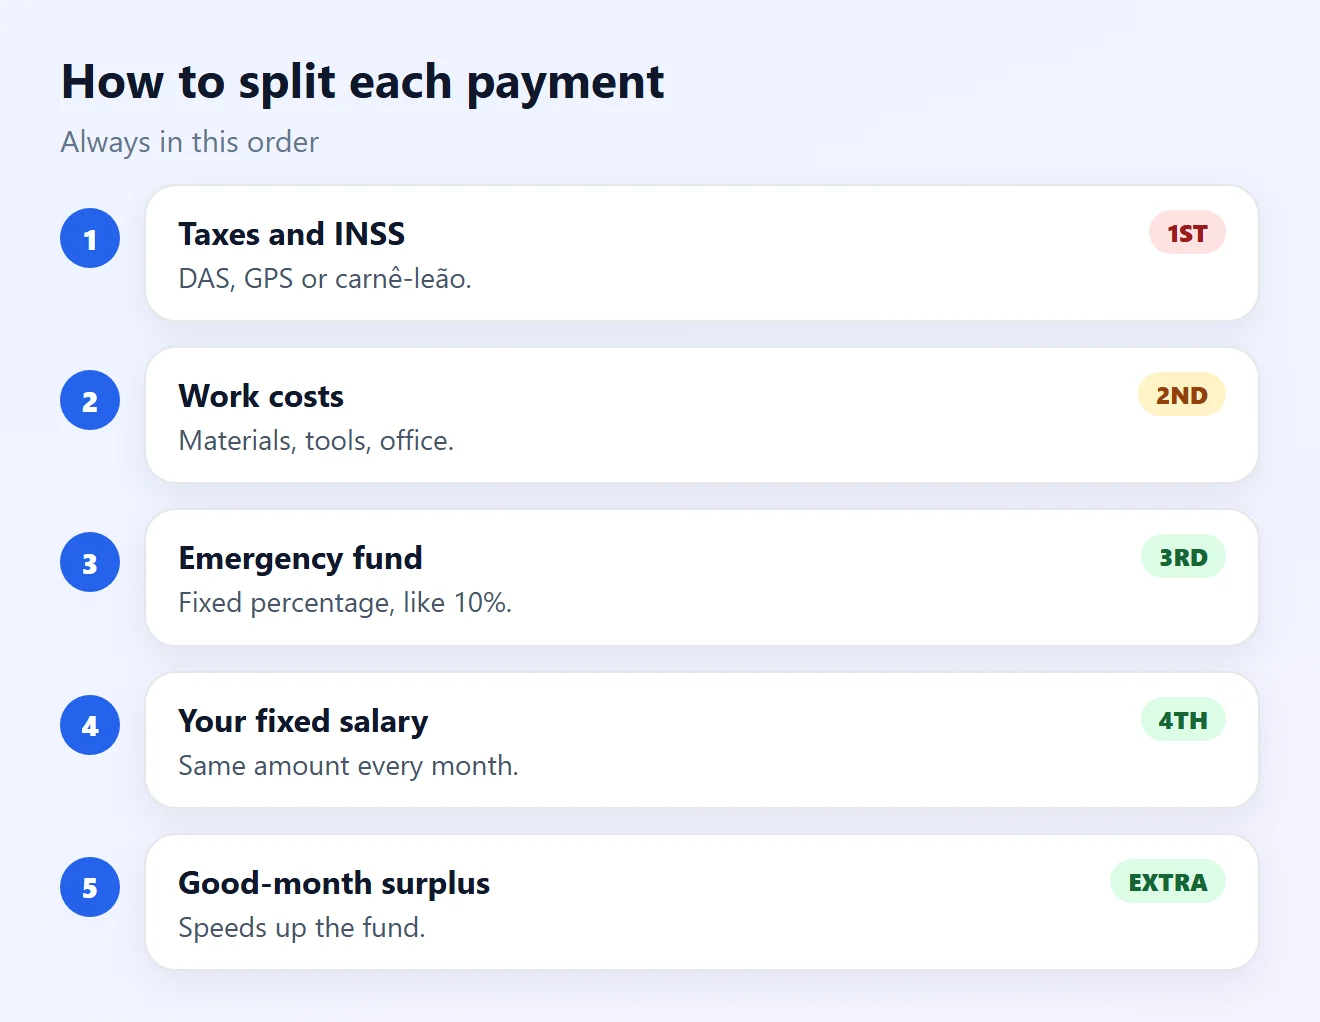
- Every time a client pays, immediately set aside a fixed percentage for the fund, for example 10%. With irregular income, a percentage works better than a fixed amount.
- Always follow the same order: taxes and INSS → work costs → fund → your salary.
- Month above average? The surplus goes to the fund, not to your lifestyle.
6Set aside taxes and INSS before anything else
- MEI: the 2026 DAS is R$ 81.05 for INSS (5% of the minimum wage), plus R$ 5 of ISS and/or R$ 1 of ICMS depending on the activity. It's due on the 20th of every month.
- Self-employed individual contributor: pays the INSS slip (GPS) by the 15th of the following month. The rate is 20%; under the simplified plan (for those who don't serve companies), 11% of the minimum wage, which doesn't count toward retirement by contribution time (to count it, you must pay an extra 9%).
- Paid by individuals? You may have to pay carnê-leão (monthly income tax) every month, deducting expenses recorded in your cash book.
- Late taxes become debt with interest: they're not an emergency fund.
7Keep it low-risk with daily liquidity
- The fund must be available the day a weak month arrives: low risk and daily liquidity, no lock-up.
- Options: Tesouro Selic, Tesouro Reserva, a daily-liquidity CDB from an authorized bank (FGC guarantee up to R$ 250,000 per CPF per institution) or poupança.
- Keep the fund in an account separate from your work and everyday accounts.
8A personal fund isn't business cash
- The personal fund pays for your life when income drops. Business cash pays for materials, equipment and work bills.
- If you have fixed work costs, build a cash reserve with a few months of those costs too.
- Equipment broke? Use the business cash, not the family's fund.
9Keep INSS up to date for protection
- With contributions up to date and the qualifying period met, INSS gives access to disability benefit, maternity pay, retirement and a pension for the family.
- Without contributing, a long illness depends only on your fund. Both together protect you better.
- Check on Meu INSS that your contributions show up on your statement (CNIS).
10Use it in weak months, refill it in strong ones
- Month below your fixed salary? Top up the difference from the fund, without credit card or overdraft.
- In the next above-average month, refill what you took before any extra spending.
- If the fund shrinks several months in a row, it's no longer a swing: review prices, clients and expenses.
- Review the goal every 6 months or when your income or family changes.
Situation and what to do
| Situation | Likely cause | What to do |
|---|---|---|
| I don't know my monthly income | Untracked variable income | Work out the 12-month average (step 2) |
| I spend it all in good months | Mixed accounts | Separate accounts and pay yourself (step 4) |
| Nothing is left to save | Fund comes last | Percentage of each payment (step 5) |
| DAS or INSS overdue | Taxes not set aside | Set taxes aside first (step 6) |
| I used the fund on equipment | No business cash | Refill and build business cash (step 8) |
| Weak month on the credit card | No fund | Use the fund and refill in strong months (step 10) |
Frequently asked questions
How many months of savings should a self-employed person have?
The CVM Investor Portal estimates 6 to 12 months of expenses, and people with variable income should aim for the high end. Start with 1 month as a first stage.
How do I calculate the fund with variable income?
Add up your personal essential expenses and multiply by the months in your goal. To know how much you can save, use your average income over the last 12 months and plan around your weakest month.
How much should I set aside from each payment?
A fixed percentage, such as 10%, after setting aside taxes, INSS and work costs. In above-average months, save the surplus.
How do I pay myself a salary when self-employed?
Send all payments to a work account and transfer a fixed amount to your personal account on the same day each month, ideally close to your weakest month's income.
How much does an MEI pay per month in 2026?
R$ 81.05 for INSS (5% of the R$ 1,621 minimum wage), plus R$ 5 of ISS and/or R$ 1 of ICMS depending on the activity. The DAS is due on the 20th.
Do self-employed people have to pay INSS?
People who work on their own account are mandatory contributors. The slip is due on the 15th of the following month. The rate is 20%, or 11% of the minimum wage under the simplified plan, which doesn't count toward retirement by contribution time.
What is carnê-leão?
It's the monthly income tax for people paid by individuals or from abroad. Work expenses recorded in the cash book can be deducted.
Where should a self-employed person keep the fund?
In a low-risk, daily-liquidity investment such as Tesouro Selic, Tesouro Reserva, a daily-redemption CDB or poupança, separate from work and everyday accounts.
Can I use the fund for my business?
Ideally, keep separate business cash. The personal fund is for paying your life when income drops.
I used the fund in a weak month. Now what?
Refill it in the next above-average month, before any extra spending. If it shrinks several months in a row, review prices, clients and expenses.
Related content
More practical solutions in Emergency fund.
How to Build an Emergency Fund From Scratch
Learn how to build an emergency fund from scratch, estimate a realistic target, save consistently, and keep the money available for unexpected essential expenses.
 20 minutes
Financial Education for Children: How to Teach It Early
Learn how to teach financial education to children and teenagers through practical examples, goals, conscious allowances, and healthy spending habits.
30 minutes
How to plan financially for retirement
Learn how to plan the retirement financial organizando objetivos, expenses future, sources of income and estratégias of longo term for build more safety financial.
30 minutes
Sources consulted
- Investor Portal (CVM): Emergencies and retirement (in Portuguese)
- Federal Revenue (Simples Nacional): MEI amounts due in 2026 (in Portuguese)
- INSS: contribution calendar for MEIs and the self-employed (in Portuguese)
- INSS: Simplified plan (in Portuguese)
- INSS: What you need to know about MEI retirement (in Portuguese)
- Federal Revenue: Carnê-leão (in Portuguese)
- Tesouro Direto: Tesouro Reserva (in Portuguese)
- FGC: About the guarantee (in Portuguese)
The images on this page are illustrations created by Fixfy. Amounts and the 10% figure are examples. DAS, INSS and tax amounts change every year: check on PGMEI, Meu INSS and the Federal Revenue.