

 Household economy
 10 steps
Quick answer: how to stop impulse buying
- Wait before paying: leave the item in the cart and decide the next day. The urge of the moment usually passes.
- Leave home (or open the app) knowing what you'll buy and how much you can spend. If it's many items, write a list.
- Look at the total price, not the installment, and write down the installments already due in the coming months.
- Distrust “today only”, “last units” and a crossed-out old price: these are sales techniques described by Brazil's Central Bank itself.
- Bought online and regret it? In Brazil you have 7 days to cancel and get your money back (Consumer Code, art. 49).
What's your case?
How to avoid impulse buying: 10 steps
1Find out what triggers the urge to buy
- The search for instant pleasure is one of the main obstacles to planning, according to the Central Bank of Brazil's Financial Education Notebook: we pay more or use money set aside for something else.
- For two weeks, write down when and how you bought without planning: time, place, app, how you were feeling.
- Common patterns: late-night phone shopping, after a hard day, out of boredom or as a reward (“retail therapy”).
- Once you know the trigger, swap the purchase for another action: go for a walk, call someone, close the app.
2Recognize sales tactics
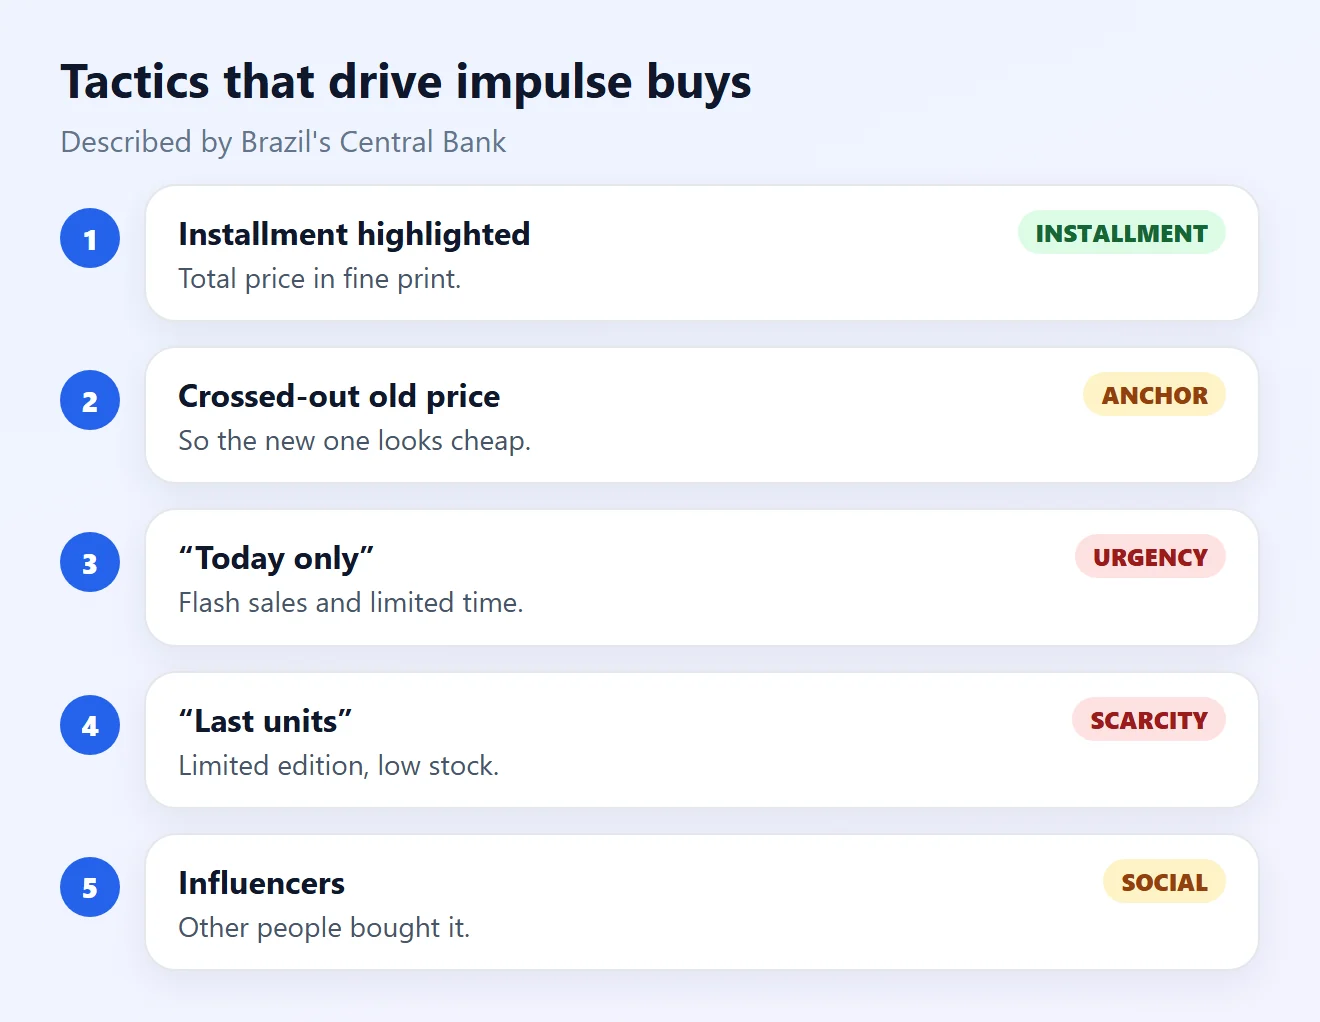
- Installment in big letters and the total in small print, or a “per day” price instead of the monthly cost.
- Crossed-out old price, and an expensive product next to a cheaper one so the second looks like a bargain.
- Urgency (“today only”, “flash sale”, “free shipping for a limited time”) and scarcity (“last units”, “limited edition”).
- Influencers and other people's reviews to boost trust and haste.
- At the supermarket: products by the checkout, expensive items at eye level, and butcher and bakery at the back of the store. The Central Bank lists all of these tactics.
3Use the waiting rule
- Leave the product in the cart or wish list and wait at least 24 hours. For bigger purchases, wait a week.
- When you come back, ask: do I need it or just want it now? Do I already have something similar? Where will I use it?
- If you still want it and it fits the budget, buy it guilt-free: the point is that the decision is yours, not the ad's.
4Go out with a list and a spending cap
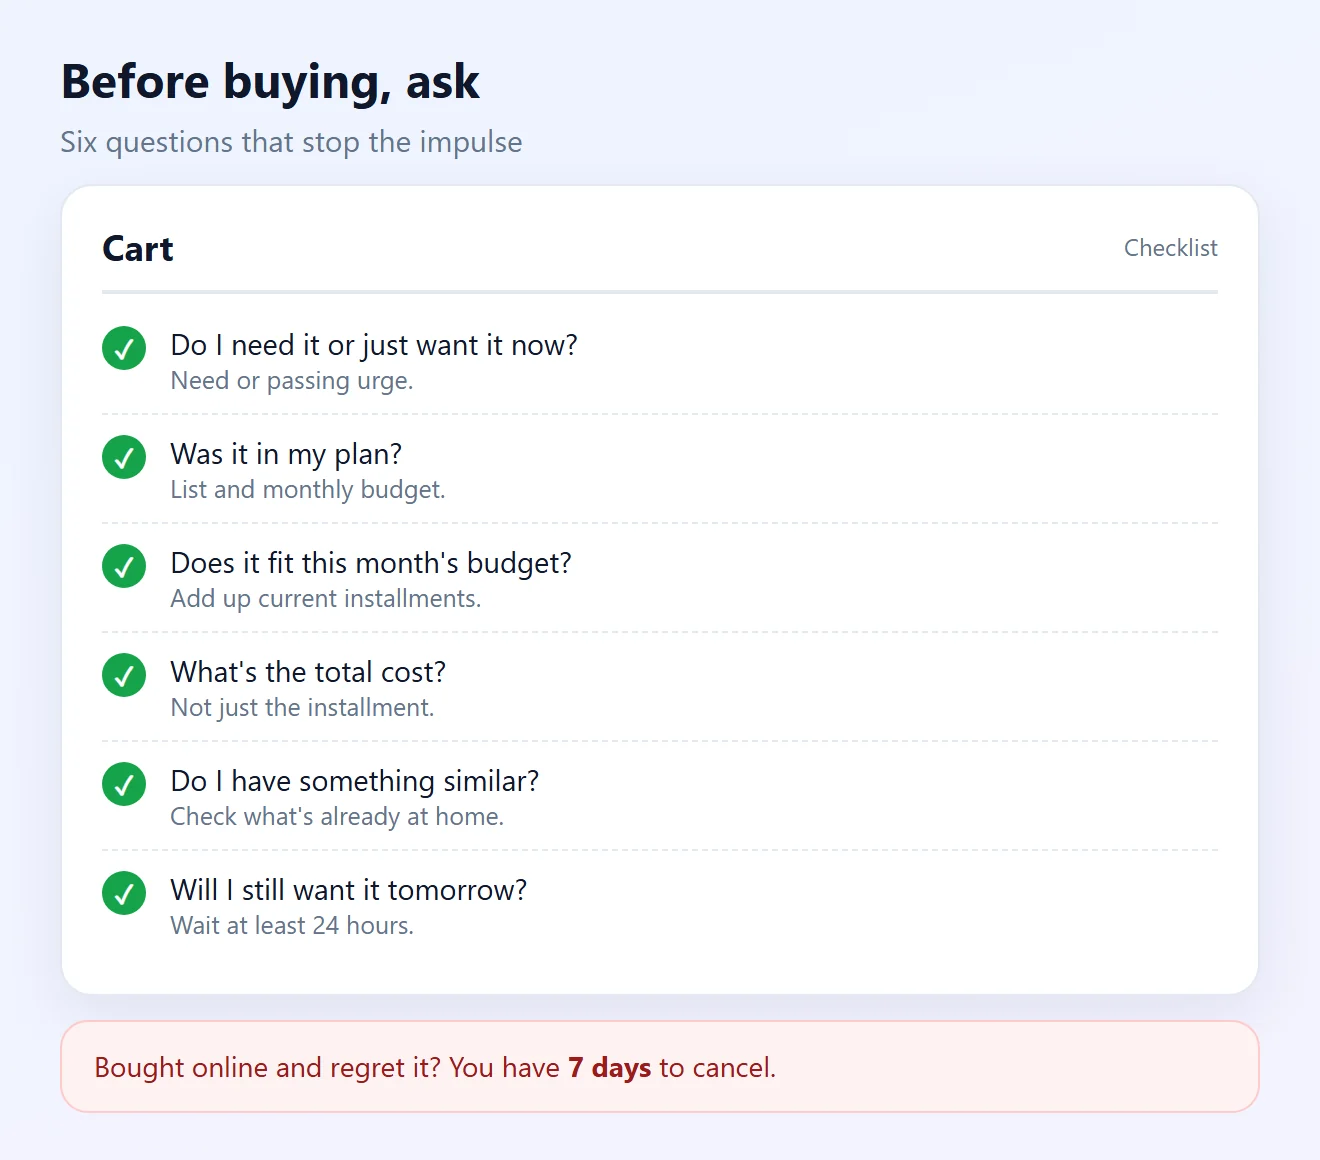
- Before leaving, decide what you'll buy and how much you plan to spend; with many items, write a list, the Central Bank recommends.
- Go shopping after eating: people who shop hungry buy more on impulse.
- Taking children? Agree in advance on what you'll buy.
- Carry only the cash or card you need for that purchase.
5Look at the total price and track installments
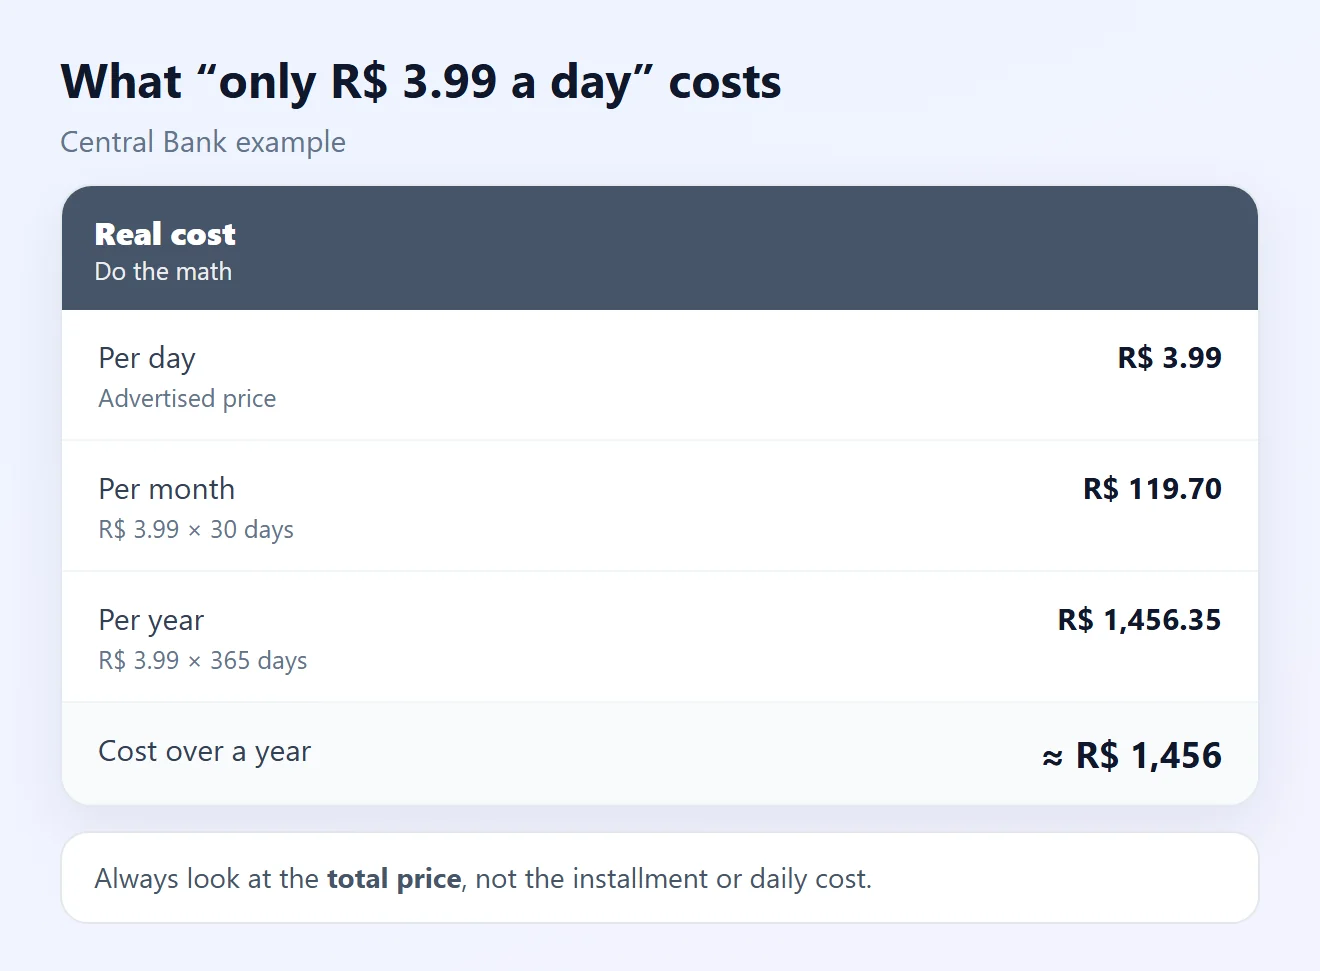
- Do the math on “per day” ads: R$ 3.99 a day is R$ 119.70 a month and almost R$ 1,500 a year (Central Bank example).
- For financed purchases, the store must state the cash price, interest, number of installments and total amount to pay (Consumer Code, art. 52). Credit offers must show the Total Effective Cost (CET).
- Write down installments for the coming months: you'll see how much of your income is already committed and avoid over-splitting.
- Small installments add up. Before a new one, add up those already on your card bill.
6Prefer paying in full and ask for a discount
- Saving first and paying in full avoids interest and may earn a discount, the Central Bank points out.
- Ask for the price with Pix or cash: Brazilian law allows different prices by payment method (Law 13,455/2017).
- Paying with money that leaves your account right away also helps you feel the expense, unlike a card that only hits next month.
7Distrust “unmissable” deals
- On dates like Black Friday, prices may be inflated beforehand just to fake a discount, the Central Bank warns.
- Check the price in other stores and the product's price history before deciding.
- “Take 2” only pays off if you were going to buy it anyway and will use it all.
- Deals on products close to expiry: make sure you'll have time to use them.
8Cut the triggers on your phone
- Turn off notifications from shopping apps and leave mailing lists and deal groups.
- Don't save your card on sites and apps: typing the details again creates a pause before paying.
- Unfollow accounts that live off showing products.
- In your bank app you can lower your Pix limit, including at night. Lowering takes effect right away; raising it goes through a review and isn't immediate, according to the Central Bank.
9Bought outside a store? Use your right to cancel
- Purchases made outside the store (online, by phone, catalog, at home) can be canceled within 7 days of purchase or delivery, without giving a reason (Brazil's Consumer Code, art. 49).
- The money must be refunded immediately and adjusted for inflation.
- Online stores must clearly explain how to cancel and accept the request through the same channel used to buy. They must also notify the card issuer so the charge doesn't appear or is refunded (Decree 7,962/2013, art. 5).
- Make the request in writing, keep the protocol number and, if the store doesn't solve it, complain to Procon or on consumidor.gov.br.
10If you've lost control, get help
- Warning signs: hiding purchases, often maxing out your limit, paying only the card minimum or shopping to relieve distress.
- Distrust easy credit: in Brazil it is forbidden to offer loans “with no credit check”, hide the risks or pressure consumers to sign up (Consumer Code, art. 54-C).
- With debts your income can't cover, see the over-indebtedness route and contact Procon.
- If the urge to buy feels impossible to control, talk to a health professional. In Brazil's SUS, care starts at your local primary health unit (UBS).
See also paying in full or in installments and how to save money on groceries.
Situation and what to do
| Situation | Likely cause | What to do |
|---|---|---|
| I shop when sad or anxious | Seeking instant relief | Identify the trigger and swap the action (step 1) |
| Card bill full of small installments | Looking only at the installment | Add up and track installments (step 5) |
| Bought on sale and never used it | Urgency and scarcity | Waiting rule (steps 3 and 7) |
| Late-night phone purchases | Notifications and saved card | Cut the triggers (step 8) |
| I regret an online purchase | Purchase outside a store | Cancel within 7 days (step 9) |
| Debts bigger than income | Easy credit and piled-up purchases | Procon and over-indebtedness (step 10) |
Frequently asked questions
Can I cancel an online purchase?
Yes. Under art. 49 of Brazil's Consumer Code, purchases made outside the store, such as online or by phone, can be canceled within 7 days of purchase or delivery, with an immediate refund.
Does the right to cancel apply in a physical store?
Not by law. Art. 49 covers purchases made outside the store. In a physical store, returns for regret depend on the store's policy, so ask before paying.
I paid by card and canceled. What happens to the charge?
The store must notify the card issuer so the purchase isn't billed or is refunded, under Decree 7,962/2013.
How long should I wait before buying?
There's no official rule. Waiting 24 hours for small purchases and a week for bigger ones helps separate need from a passing urge.
How can I tell if a deal is real?
Compare prices in other stores and check the product's price history. The Central Bank warns that on dates like Black Friday prices may be inflated beforehand to fake a discount.
Are interest-free installments always good?
Only if the purchase was planned and the installments fit your budget along with the ones you already have. Also ask for the cash price: there may be a discount.
Can I limit Pix so I don't spend at night?
Yes. In your bank app you can lower your Pix limits, including at night. Lowering takes effect right away; raising goes through the bank's review.
Are “no credit check” loans allowed?
No. Art. 54-C of Brazil's Consumer Code forbids advertising credit as granted without checking credit bureaus or the consumer's financial situation.
Is impulse buying an illness?
Buying on impulse now and then is common. If the urge feels impossible to control and causes distress or debt, see a health professional.
Where can I complain if the store refuses to cancel?
To your city's Procon or on consumidor.gov.br, which is free. Keep the cancellation request, protocol number and proof of purchase.
Related content
More practical solutions in Household economy.
How to Compare Prices Online Safely and Save More
Learn how to compare prices online safely, calculate the total purchase cost, reduce scam risk, and find better value before placing an order.
 15 minutes
How to save cooking gas and reduce household expenses
Learn simple habits to save cooking gas, increase food-preparation efficiency, and reduce monthly expenses without compromising meal quality.
15 minutes
How to save on your electricity bill: tips to reduce energy consumption
Learn how to save in the bill of luz with habits simples, use eficiente of eletrodomésticos and estratégias for reduce the consumption of energy electric without perder conforto.
15 minutes
Sources
- Central Bank of Brazil: Financial Education Notebook, Module 4 – Planned and Conscious Consumption (PDF, in Portuguese)
- Planalto: Consumer Protection Code (arts. 49, 52, 54-B and 54-C, in Portuguese)
- Planalto: Decree 7,962/2013 (e-commerce, in Portuguese)
- Planalto: Law 13,455/2017 (price by payment method, in Portuguese)
- Central Bank of Brazil: Pix Management Report (day and night limits, PDF, in Portuguese)
- Gov.br: complaining on consumidor.gov.br (in Portuguese)
The images on this page are illustrations created by Fixfy.