

 Financial budget
 10 steps
Quick answer: pay in full or in installments?
- Add up all the installments and compare with the upfront price. In credit sales, the store must disclose both.
- Ask for a discount to pay with Pix or cash: Brazilian law allows different prices depending on how you pay.
- If there's an upfront discount, “interest-free” has hidden interest. Work it out with Brazil's Central Bank calculator.
- Hidden interest higher than what your money earns? Pay upfront, as long as it doesn't come from your emergency fund.
- Splitting it? Only if the installment fits comfortably alongside the ones you already have, ideally interest-free.
What's your case?
How to decide between paying in full or in installments: 10 steps
1Compare the upfront price with the sum of the installments
- Multiply the installment by the number of installments and compare with the upfront price. Include any down payment, shipping and insurance.
- In credit or financed purchases, Brazil's Consumer Defense Code (art. 52) requires the store to disclose the total amount payable, with and without financing.
- If the installment total equals the upfront price and there's no discount, interest-free installments cost nothing extra.
2Ask for a discount to pay upfront
- Law 13,455/2017 allows different prices depending on the payment term or method. So stores can give a discount for Pix, cash or debit.
- When there's a discount by payment method, the store must show it in a visible place and format.
- No discount shown? Ask: “How much with Pix?”. Many stores negotiate, especially on larger purchases.
3Find the interest hidden in “interest-free”
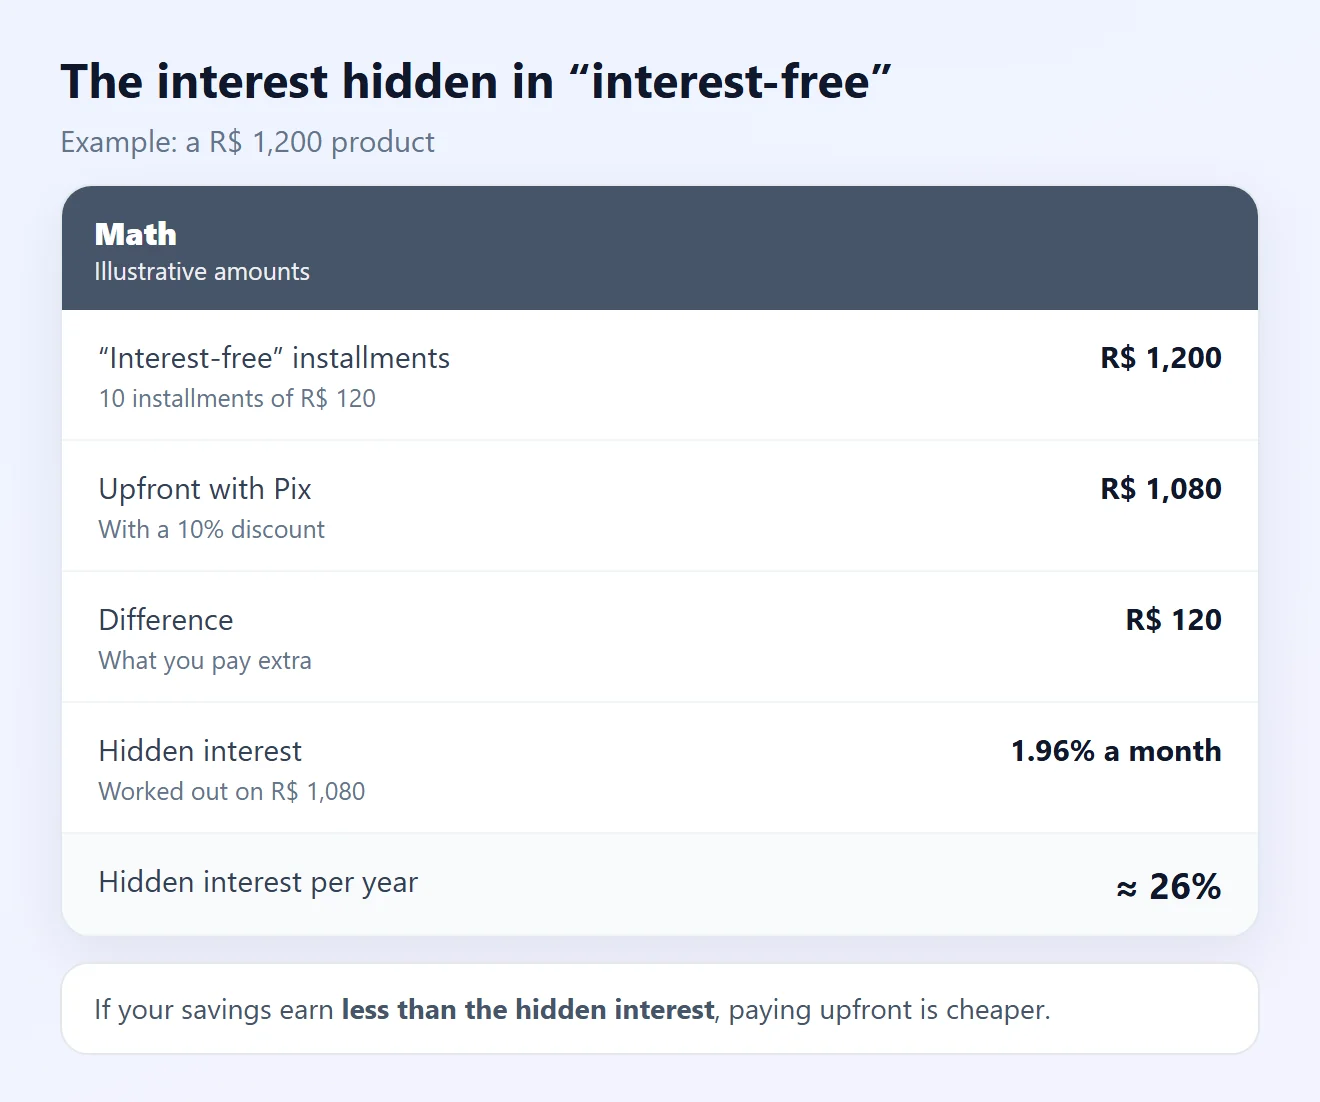
- If the upfront price is lower, “interest-free” installments carry hidden interest: you pay extra for the time.
- Use the Central Bank's Calculadora do Cidadão (in Portuguese), “Financiamento com prestações fixas”: fill in the number of months (Nº de meses), the installment (Valor da prestação) and, as the financed amount (Valor financiado), the upfront price. Leave the rate blank and click Calcular.
- In the example, R$ 1,080 upfront or 10 × R$ 120 gives 1.96% a month, about 26% a year. The calculator assumes the first installment isn't paid at purchase.
4Compare the hidden interest with what your money earns
- Check in your banking app what your savings earn per month, after tax.
- If the hidden interest is higher than that return, paying upfront is cheaper.
- If there's no upfront discount, paying in interest-free installments and keeping the money invested can pay off, as long as you pay every installment on time.
5Don't drain your emergency fund
- The fund is for emergencies, like losing income or an urgent repair. Using it to get a small discount leaves you unprotected.
- If paying upfront empties the fund, it's better to wait and save or split it into small interest-free installments.
- Paying upfront makes sense with money saved for this purchase, separate from the fund.
6Check the installment fits with the ones you already have
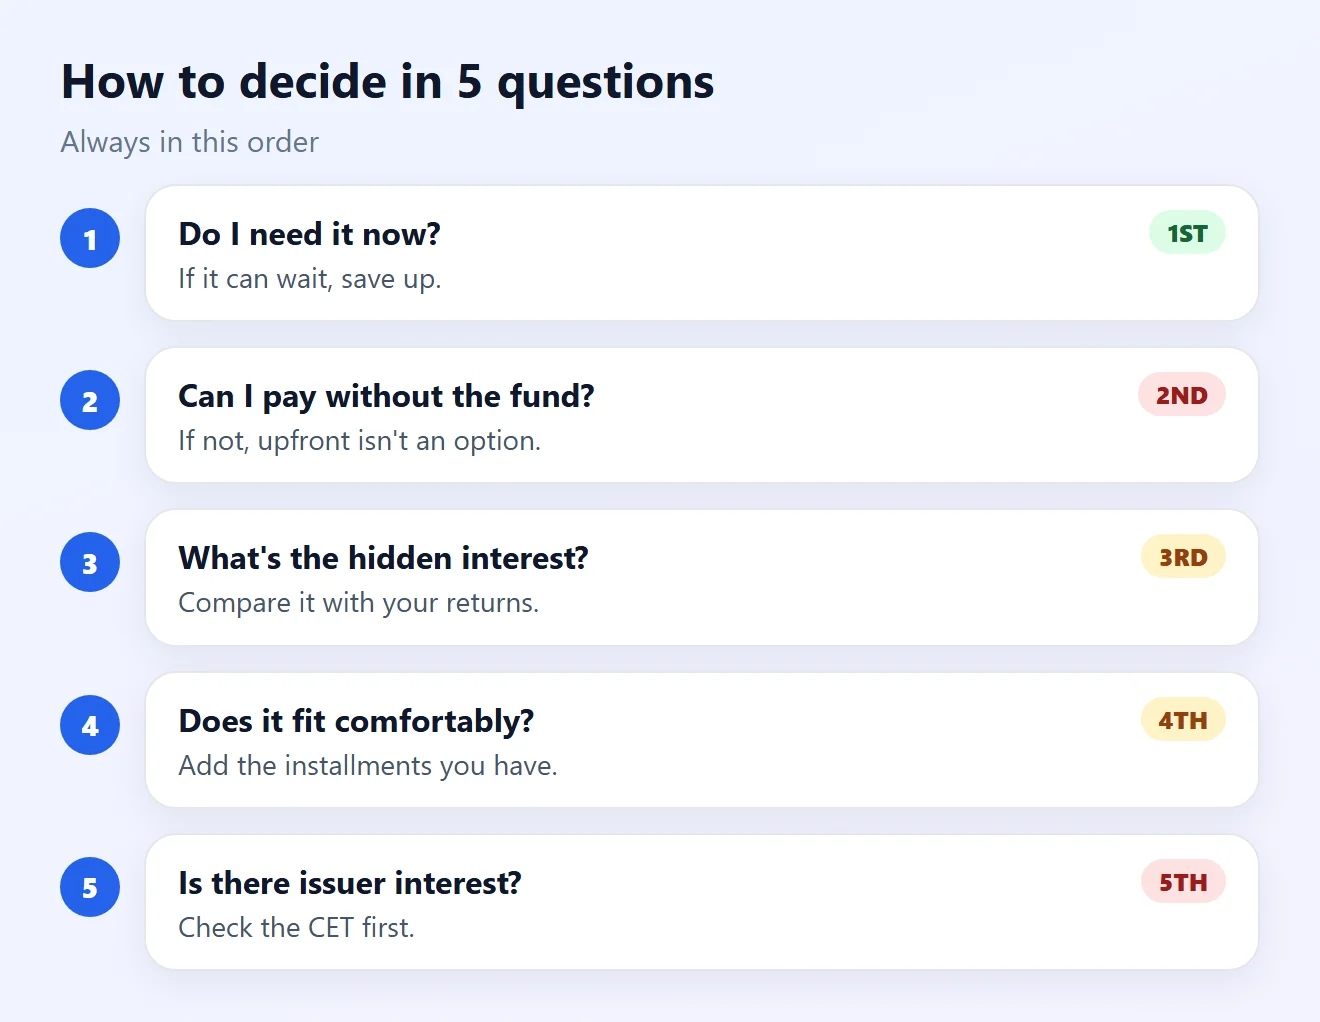
- Add up all open installments on your card bill and payment books, plus the new one. Many small installments become a big bill.
- Make sure there's money left for essential bills (housing, food, transport) in every month of the plan.
- Choose the fewest installments that fit your budget: you're debt-free sooner.
7On a card: “interest-free” versus “issuer interest”
- Interest-free installments (from the store): the total is split equally across your bills.
- Installments with interest (from the issuer): it's a loan from your card's bank. Before accepting, check the interest rate and the Total Effective Cost (CET), which combines interest, fees and taxes.
- Installments usually take up your limit for the full amount, freeing it gradually as you pay.
- Buying right after your bill closing date gives you more time until the first payment.
8Store credit or financing: demand the information first
- Under the Consumer Defense Code (art. 52), the store must disclose beforehand: price in reais, late interest, effective annual interest rate, additional charges, number and frequency of installments and the total, with and without financing.
- The late fee can't exceed 2% of the installment.
- Read the contract and ask for a copy. Be wary of insurance or extended warranties added without asking.
9Extra money? Pay installments early with a discount
- The Consumer Defense Code (art. 52, §2) guarantees early repayment, in full or in part, with a proportional reduction of interest and other charges.
- It applies to purchases with interest, such as store credit, financing and card issuer installments. Ask for the updated payoff amount.
- Paying the last installments early usually gives the biggest interest discount.
10Never let the purchase become revolving credit
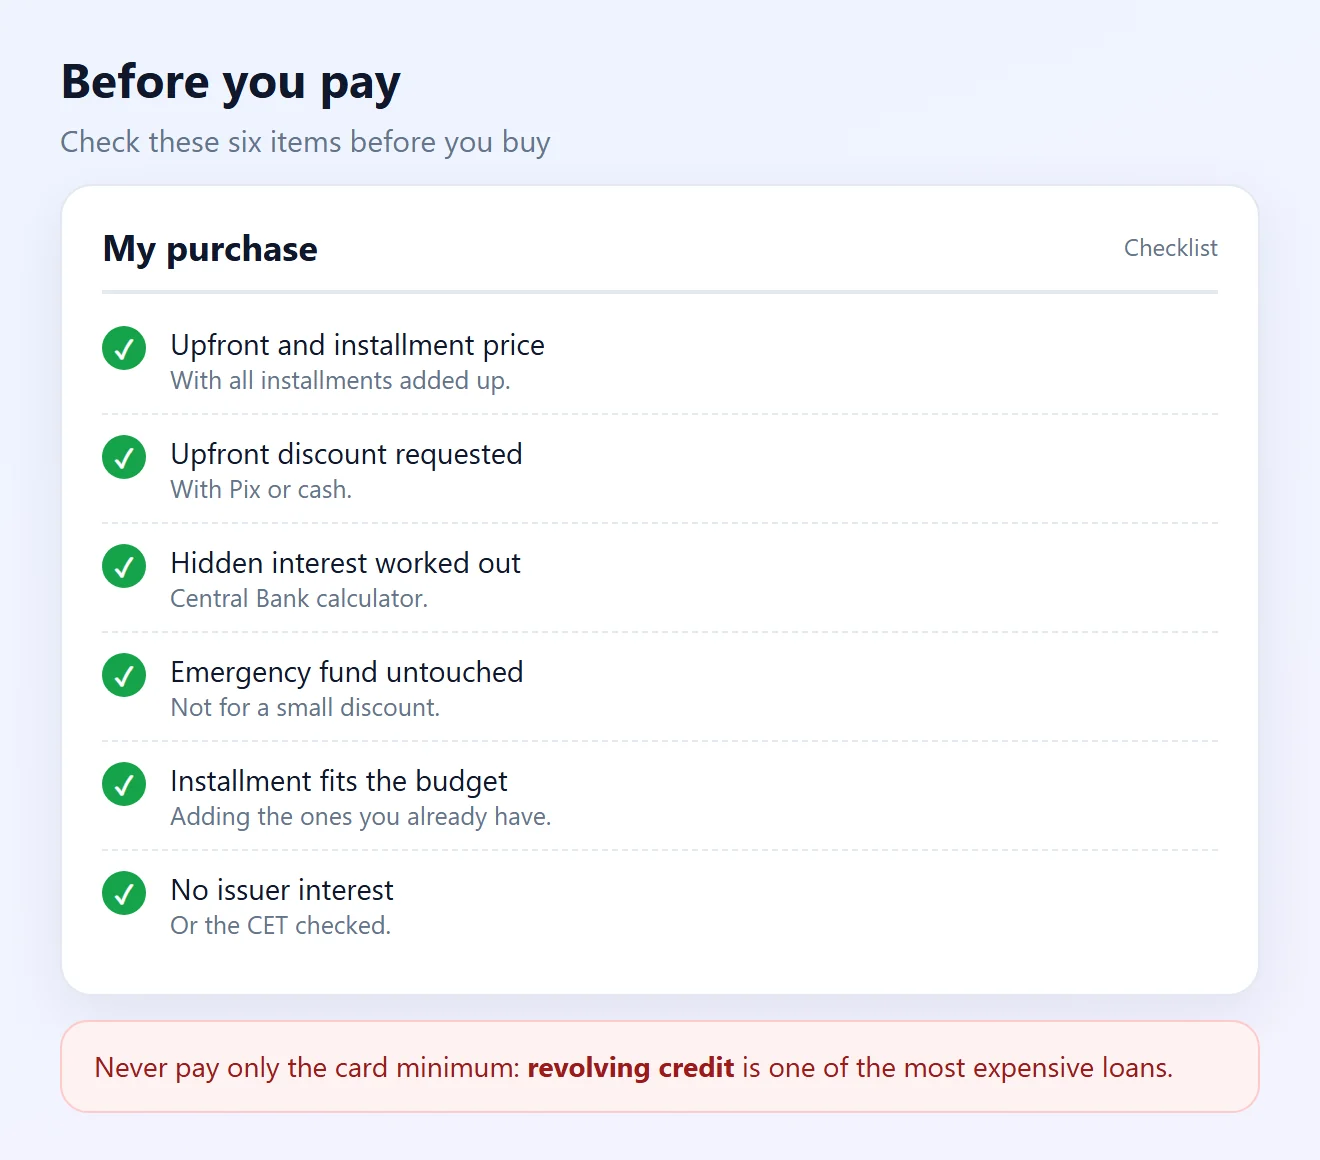
- Paying only the bill's minimum pushes the rest into revolving credit, one of the most expensive loans in Brazil.
- Under Law 14,690/2023, interest and charges on revolving credit and bill installment plans can't exceed the original debt. Even so, the debt can double.
- If the bill doesn't fit, talk to your bank to negotiate before the due date.
Situation and what to do
| Situation | Best choice | Why |
|---|---|---|
| Good upfront discount and money saved | Upfront | Hidden interest beats your returns (steps 3 and 4) |
| Same price upfront or in installments | Interest-free installments | Your money earns while you pay (step 4) |
| Upfront only by using the fund | Wait or split interest-free | The fund is for emergencies (step 5) |
| Installment doesn't fit the budget | Postpone the purchase | Risk of late payment and revolving credit (steps 6 and 10) |
| Installments with issuer interest | Compare the CET | It's a loan (step 7) |
| Store credit | Demand the rate and total | Consumer Code right (step 8) |
Frequently asked questions
Is it better to pay in full or in installments?
It depends. With an upfront discount and money saved outside your emergency fund, paying upfront is usually cheaper. Without a discount, interest-free installments can be worth it if they fit your budget.
Can a store charge different prices for Pix and card?
Yes. Law 13,455/2017 allows different prices depending on the payment term or method, and the discount must be shown in a visible place.
Do interest-free installments have interest?
If there's an upfront discount, yes: the difference is hidden interest. You can work it out with the Central Bank's Calculadora do Cidadão.
How do I work out the hidden interest?
In the Calculadora do Cidadão (Financiamento com prestações fixas), enter the number of months, the installment and the upfront price as the financed amount, and leave the rate blank.
How big a discount is worth it?
It's worth it when the hidden interest is higher than your money's net monthly return. Over 10 installments, a 10% discount equals almost 2% a month.
Should I use my emergency fund to pay upfront?
Not for a small discount. The fund is for emergencies. If it would be emptied, it's better to wait or split it interest-free.
What must a store disclose for store credit?
Under art. 52 of the Consumer Defense Code: price in reais, late interest, effective annual interest rate, additional charges, number and frequency of installments and the total, with and without financing.
Can I pay installments early with a discount?
Yes. The Consumer Defense Code guarantees early repayment, in full or in part, with a proportional reduction of interest and other charges.
What's the fee for a late installment?
In consumer credit, the late fee can't exceed 2% of the installment, plus late interest.
Do card installments use up my whole limit?
Usually, yes: the full purchase amount is held against your limit and freed as the installments are paid.
Related content
More practical solutions in Financial budget.
How to Cancel Forgotten Subscriptions and Save Money
Find recurring subscriptions that may be consuming your budget and learn how to identify automatic charges and cancel services you no longer use.
 10 minutes
Credit Score: How It Works and What Influences Your Score
Understand what a credit score is, which factors may influence it, and how to maintain a more organized financial history.
10 minutes
How to Cut Unnecessary Expenses Without Giving Up Everything
Learn how to identify low-value spending, reduce waste, and save money without unnecessarily sacrificing your quality of life or essential needs.
30 minutes
Sources consulted
- Planalto: Consumer Defense Code, art. 52 (in Portuguese)
- Planalto: Law 13,455/2017, different prices by payment method (in Portuguese)
- Planalto: Law 14,690/2023, revolving credit interest limit, art. 28 (in Portuguese)
- Central Bank of Brazil: Calculadora do Cidadão, fixed installment financing (in Portuguese)
The images on this page are illustrations created by Fixfy. Amounts are examples.