

 Credit card
 10 steps
Quick answer: how to control your credit card limit in Brazil
- Your limit is the bank's credit, not income. Set a personal cap based on what you can pay in full on the bill.
- You can ask to lower your limit at any time, and the bank has up to 2 business days to do it.
- The bank can't raise your limit without your yes, given for each increase.
- If the bank lowers it on its own, it must give 30 days' notice, unless your credit risk has worsened.
- Installment purchases usually take up the limit for the full amount and free it up gradually as installments are paid.
What's your case?
Credit card limit: 10 steps to control and adjust it
1Understand what the limit is
- The limit is the maximum credit the bank makes available on the card. It's borrowed money that comes back on the bill.
- The app shows the total limit and the available limit. The difference is what's already used: purchases, future installments and withdrawals.
- Under Central Bank rules, the limit must be compatible with your risk profile and ability to pay.
2Set your personal cap based on income
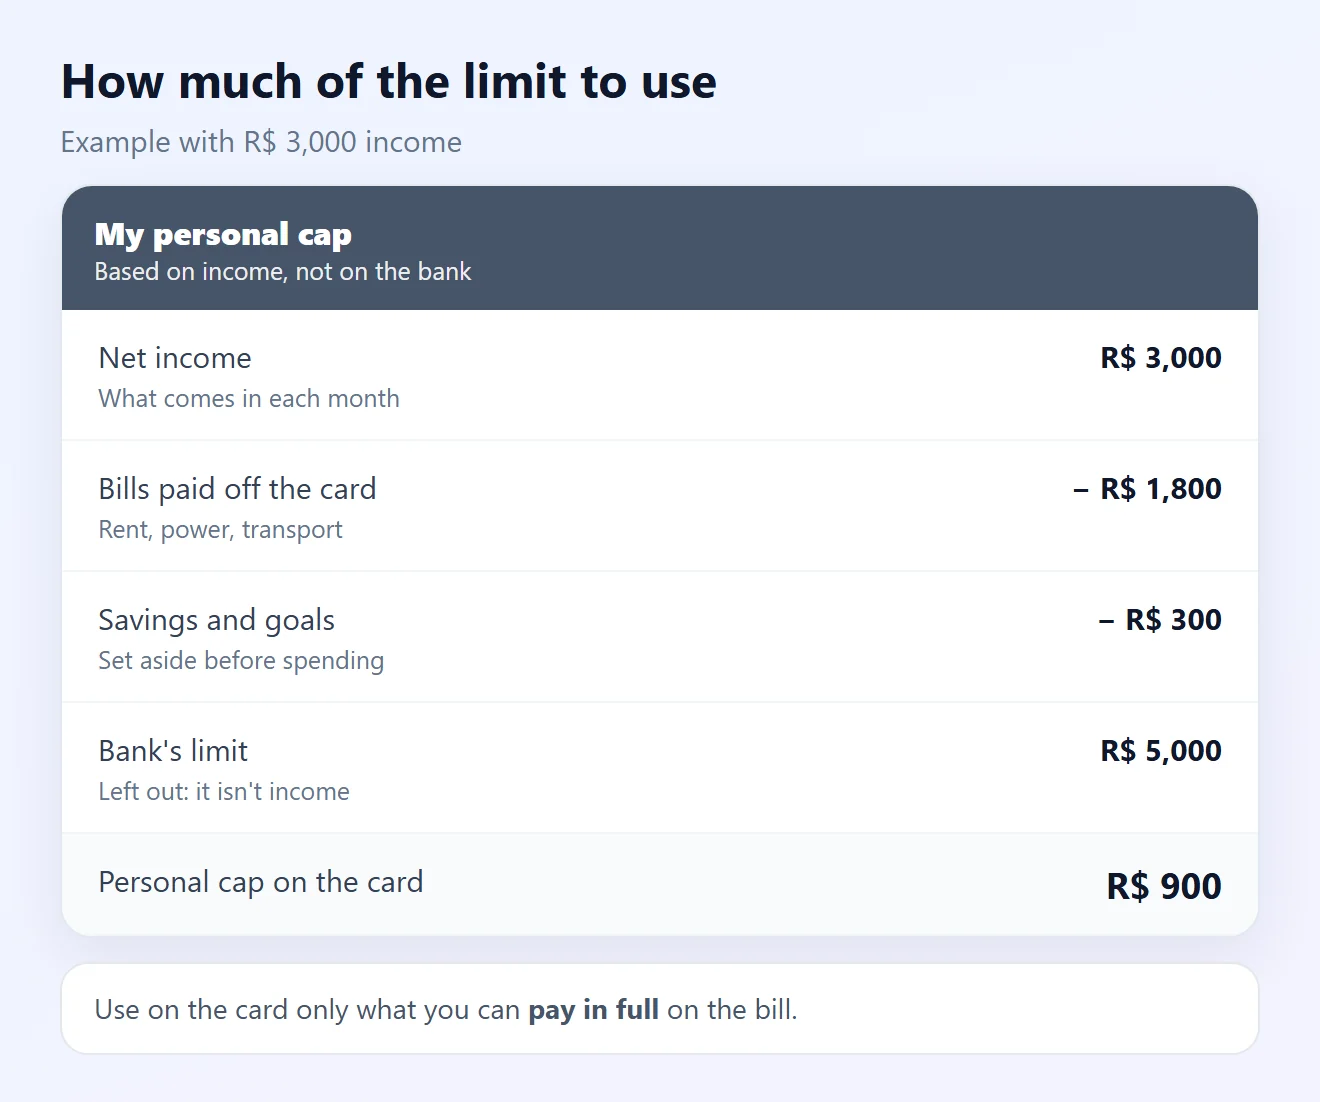
- Start from your net income, then subtract bills paid off the card and what goes to savings and goals.
- What's left is the most you should spend on the card each month, including installments already coming.
- The bank's limit doesn't go into this math: it can be much higher than what you can pay.
3Lower the limit in the app
- Most apps have an "adjust limit" option. Keep the limit close to your personal cap.
- You can ask for a lower limit at any time, and the bank must do it within 2 business days.
- Can't find the option? Ask via chat or customer service and write down the ticket number.
4Increases only with your yes
- When the bank takes the initiative, a limit increase requires your prior consent.
- Since July 2024, that consent must be given for each increase, and the bank must notify you by the time of the change.
- Limit went up without your consent? Ask to go back to the previous amount in the app or customer service. No solution? Complain on consumidor.gov.br.
5Bank lowered your limit? Know the rule
- A reduction you didn't request requires at least 30 days' notice.
- The exception is a worsening of your credit risk under the bank's criteria, such as late payments. In that case, notice can come by the time of the reduction.
- No notice and no reason? Ask for a written explanation and complain on consumidor.gov.br.
6Understand how installments use the limit
- On most cards, an installment purchase takes up the full amount of the limit right away.
- The limit comes back gradually as you pay each bill. That's why it seems to "not come back" after you pay.
- The bill must show the used and available limit and the total balance of future obligations, including installments.
7Know what happens over the limit
- As a rule, a purchase above the available limit is declined.
- The bank may charge an emergency credit assessment fee to approve a purchase above the limit, but only if you ask, and at most once every 30 days.
- If you didn't ask, don't accept the charge: dispute it on the bill.
8Control additional and virtual cards
- Additional cards usually share the cardholder's limit. Check in the app whether you can set a separate limit for each one.
- Virtual cards for online shopping also use the limit. Delete the ones you no longer use.
9Need a higher limit? Ask the right way
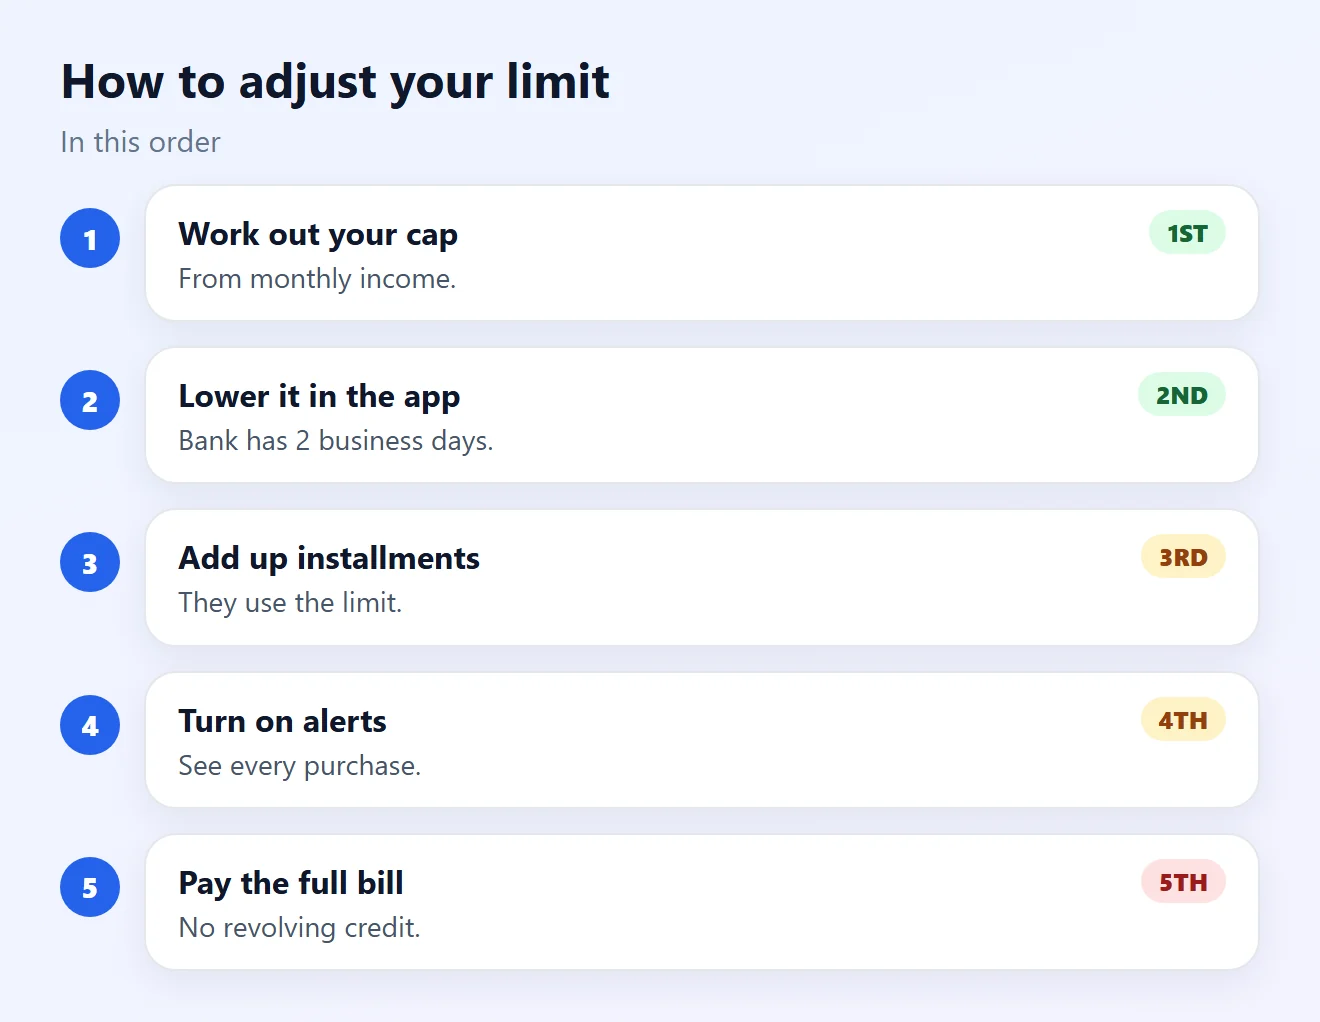
- Before asking, check that the expense fits your personal cap. A higher limit doesn't raise your income.
- Ask in the app. The bank looks at income, payment history and other debts, including at other banks.
- Keeping your income up to date in the app and paying bills on time helps.
10Check your limit every month
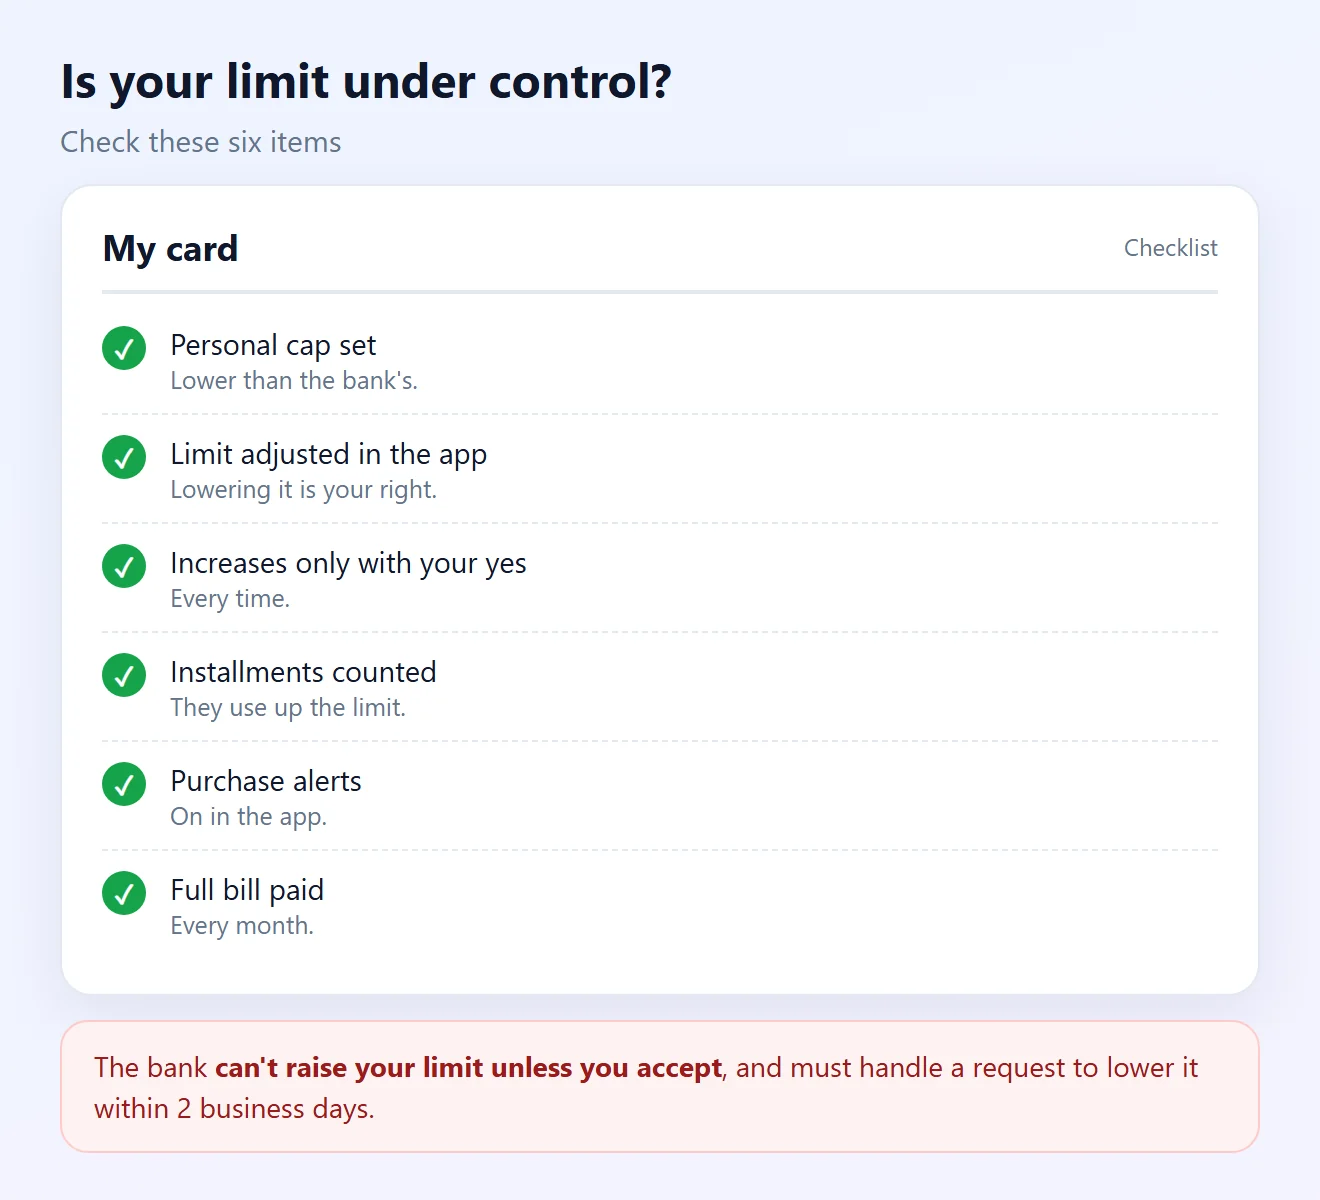
- Turn on purchase alerts in the app to see every charge right away.
- Pay the full bill. Whatever is left goes into revolving credit and keeps using up the limit.
- Check the Central Bank's Registrato to see your debts and commitments at all banks and which banks you have a relationship with.
See what to do about a high bill and how to get out of credit card debt.
Problem and fix
| Problem | Likely cause | Fix |
|---|---|---|
| I spend more than I can pay | Limit above income | Personal cap and lower it in the app (steps 2 and 3) |
| Limit went up on its own | Increase without consent | Ask to revert and complain (step 4) |
| Limit cut with no notice | Reduction by the bank | Demand the 30-day notice (step 5) |
| Paid, but the limit didn't return | Future installments | Add up installments (step 6) |
| Fee for going over the limit | Emergency assessment | Dispute it if you didn't ask (step 7) |
| Increase request denied | Income or history | Update income and pay on time (step 9) |
Frequently asked questions
Can the bank raise my limit without asking me?
No. An increase on the bank's initiative requires your prior consent, which since July 2024 must be given for each increase.
Can the bank lower my limit?
Yes, but it must give at least 30 days' notice. If your credit risk worsens, notice can come by the time of the reduction.
How long does the bank have to lower my limit when I ask?
Up to 2 business days. You can ask for a lower limit at any time.
Why didn't my limit come back after I paid the bill?
On most cards, an installment purchase takes up the full amount of the limit, which comes back gradually as installments are paid. Release can also take a little time after payment.
Can I go over my card limit?
As a rule, the purchase is declined. If you ask for an emergency credit assessment, the bank may approve it and charge a fee, at most once every 30 days.
How much of the limit should I use?
Only what you can pay in full on the bill. Work it out from net income minus fixed bills and savings, not from the bank's limit.
Do additional cards have their own limit?
They usually share the cardholder's limit. Some apps let you set a limit for each additional card.
How do I get a limit increase?
Ask in the app, keep your income up to date and pay bills on time. The bank looks at income, history and other debts.
Does lowering my limit hurt my credit score?
No official rule says so. Paying on time matters most. Check with the credit bureau you use.
Where can I see all my card debts?
In the Central Bank's Registrato, which shows your debts and commitments with all banks and institutions. Each card's limit shows in the app and on the bill.
Related content
More practical solutions in Credit card.
Credit card debt: first steps
Learn how to lidar with debt in the card of credit, reduce interest, negociar with the administradora and recuperar the controle of the finanças without comprometer the budget.
 15 minutes
High Credit Card Bill: How to Reduce It and Regain Financial Control
Learn how to reduce a high credit card bill, identify excessive spending, cancel unnecessary charges, and prevent new debt.
15 minutes
Sources
- BCB Resolution 96/2021, arts. 9 and 10: the bill and rules for raising and lowering the limit (in Portuguese)
- CMN Resolution 3,919/2010: emergency credit assessment fee, consolidated text (in Portuguese)
- Central Bank of Brazil: Registrato (in Portuguese)
- gov.br: new credit card rules in 2024 (in Portuguese)
- consumidor.gov.br: complaints against companies (in Portuguese)
The images on this page are illustrations created by Fixfy. Amounts are examples.