

 Financial budget
 10 steps
Quick answer: how to improve your credit score in Brazil
- Check your score for free on the credit bureau's site or app (Serasa, Boa Vista, SPC). The law guarantees free access.
- Check your loans on the Central Bank's Registrato and dispute any wrong data: the bureau has up to 10 days to fix it.
- Settle negative records and pay bills and installments on time: in the Serasa Score, payments weigh 29%.
- Avoid applying for credit in several places at once.
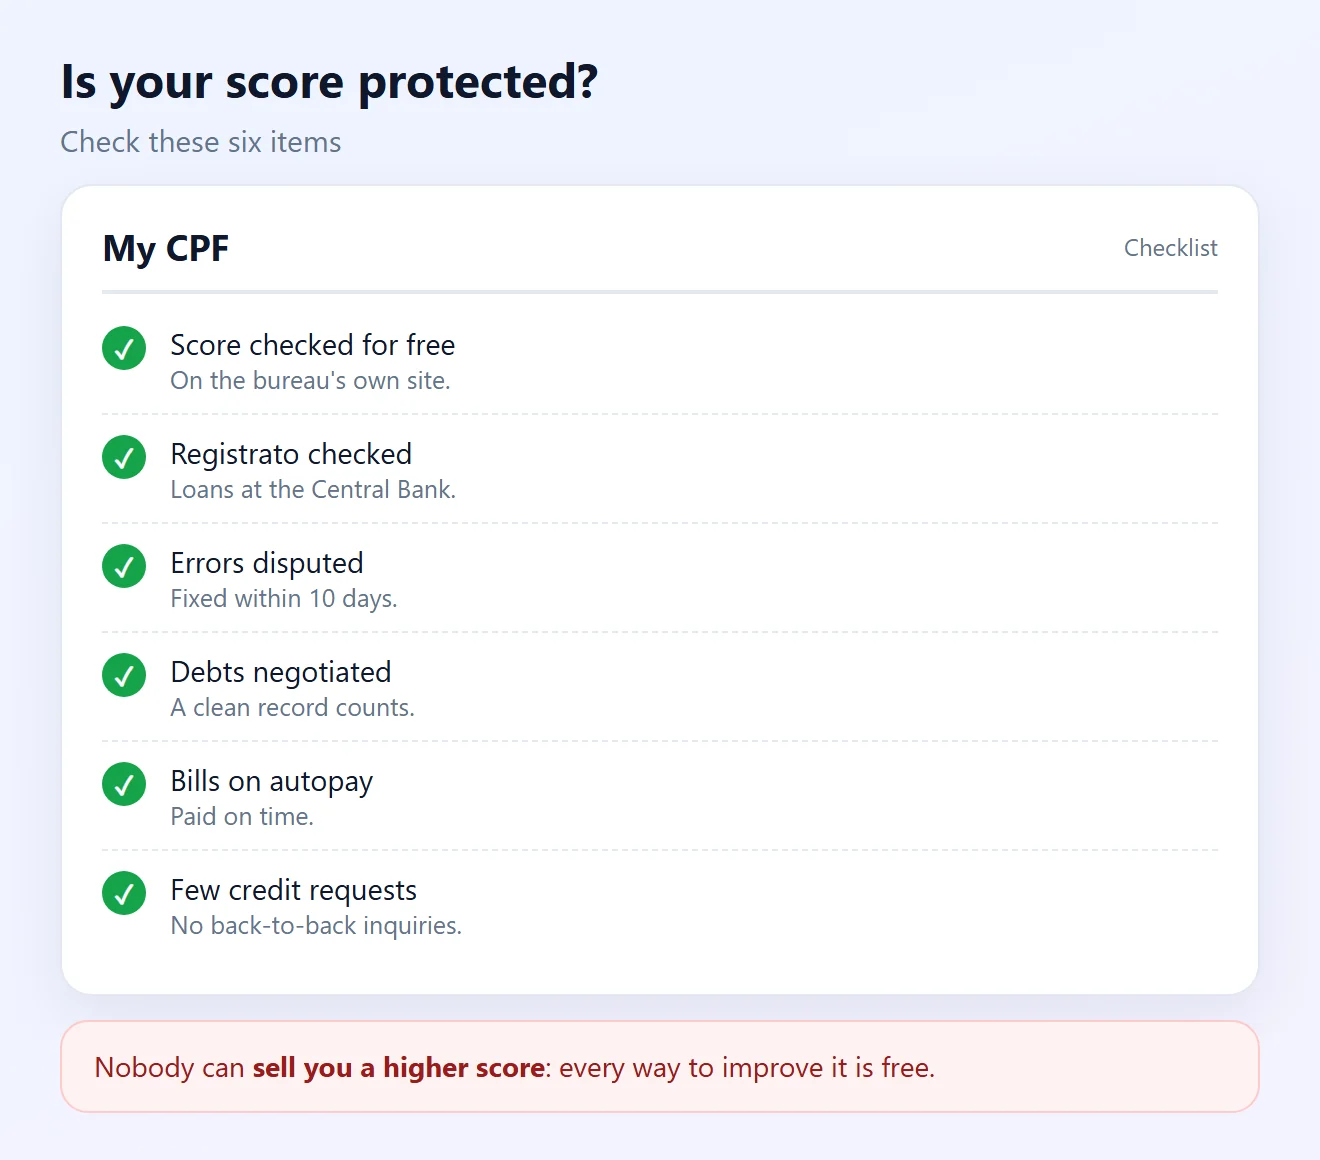
- Nobody can sell you a higher score: every way to improve it is free.
What's your case?
How to improve your credit score: 10 steps
1Check your score for free
- The score is a rating, usually from 0 to 1,000, that estimates how likely you are to pay bills on time. Each Brazilian credit bureau calculates its own: Serasa, Boa Vista (SCPC) and SPC Brasil.
- Check it directly on the bureau's official site or app, with your CPF and a free account.
- Brazil's Positive Credit Record Law guarantees free access, with no justification needed, to your score and history.
- On Serasa's scale, 501 to 700 is considered good and above 700, excellent. But the lender always makes the final credit decision.
2Check your loans on Registrato
- Registrato is a free Central Bank of Brazil system. Among other things, it shows a loans and financing (SCR) report and a bounced checks report.
- To sign in, use a silver or gold gov.br account with two-step verification turned on.
- Look for loans, cards or financing you didn't take out. If something is wrong, contact the institution that reported it.
3Dispute any wrong data
- A debt that isn't yours, already paid or with the wrong amount? File a dispute with the bureau itself, by site, app or phone.
- Under the Positive Credit Record Law, wrong information must be corrected or removed within 10 days in every database that shared it.
- Brazil's Consumer Protection Code also guarantees correction and requires those who received the wrong data to be notified within 5 business days.
- No solution? File a complaint on consumidor.gov.br or with Procon.
4Settle negative records
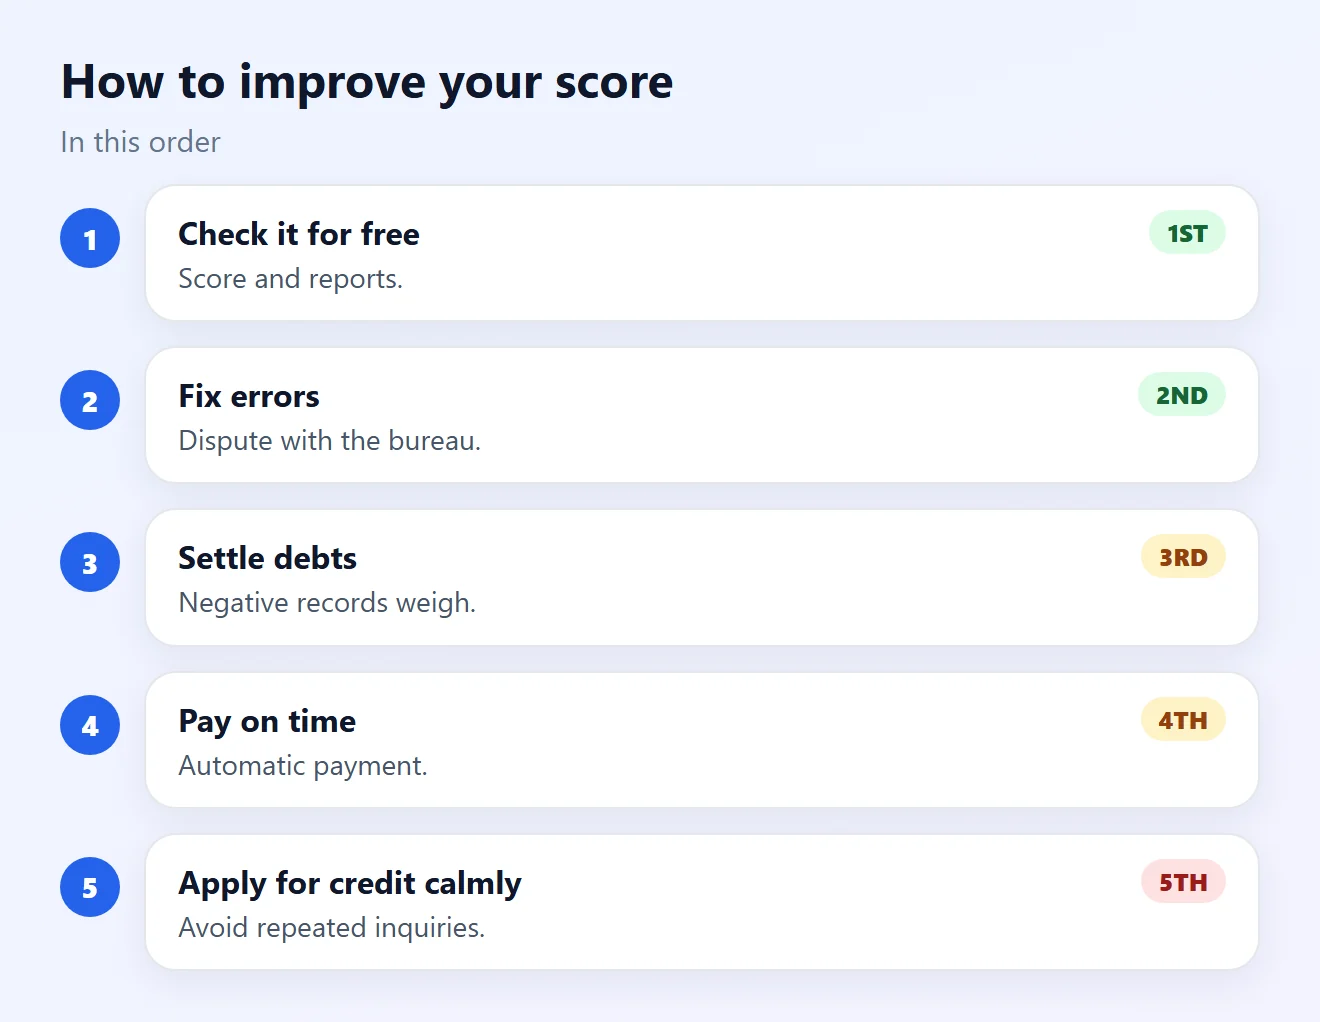
- A negative record is one of the factors that hurts your score most. Negotiate directly with the creditor or through the bureau's official channels.
- Only agree to an installment that fits your budget: a broken agreement counts against you again.
- According to Serasa, paying the agreement by Pix can make your score rise faster, when the creditor accepts Pix.
- Under the Consumer Protection Code, negative information can't stay on record for more than 5 years.
See what to do about a negative credit record and how to negotiate bank debt.
5Pay bills and installments on time
- Paying on time counts most: electricity, water, phone, credit card bill, installments and financing.
- Put fixed bills on automatic payment or schedule them so you don't forget.
- On your credit card bill, pay the full amount whenever possible. Paying only the minimum leads to revolving credit, with high interest.
6Understand what weighs on your score
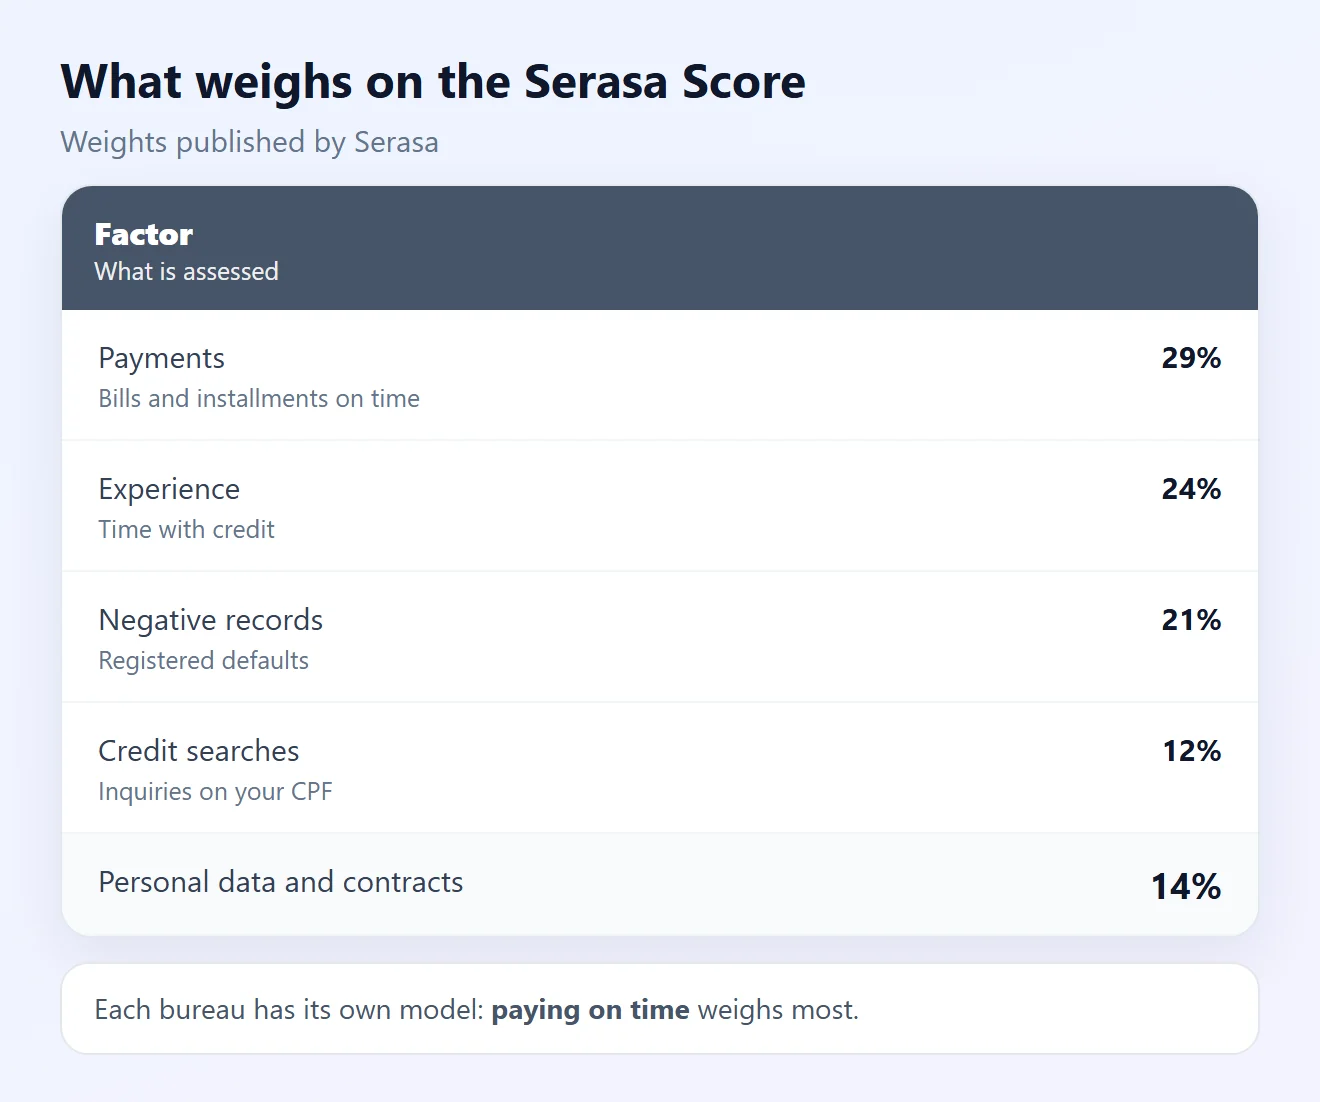
- Serasa publishes the weights of its model: payments 29%, market experience 24%, negative records 21%, credit searches 12%, personal data 8% and contracts 6%.
- Boa Vista and SPC have their own models, but paying on time and having no negative records count in all of them.
- The law gives you the right to know the main criteria used in the risk analysis. Ask the bureau if you want to understand your score.
7Keep your Positive Credit Record active
- The Positive Credit Record (Cadastro Positivo) collects your history of bills paid on time. It is opened automatically, and you must be notified within 30 days.
- You can cancel or reopen it for free, at any bureau. The request applies to all of them within 2 business days.
- Note: with the record canceled, your history of good payments is no longer used in the calculation. If you pay on time, keeping it active usually helps.
- The law forbids recording sensitive information, such as health, religion or sexual orientation.
8Apply for credit calmly
- Each credit application triggers an inquiry on your CPF. Many inquiries in a short time can signal financial strain and lower your score.
- Compare offers first and apply only where you're more likely to be approved.
- Credit denied? The lender may use its own criteria. If the decision was purely automated, the law lets you ask the lender for a review.
9Update your personal details
- In the bureau's app, check your address, phone, email and income.
- Outdated details can hurt the analysis and make you miss collection or negative-record notices.
10Track it patiently and avoid scams
- Your score changes gradually. According to Serasa, fluctuations of up to 100 points within the same range are normal.
- Check once a month, always in the same app, to compare.
- Score boost scam: nobody can “raise your score” for a fee. Every way to improve it is free.
Problem and fix
| Problem | Likely cause | Fix |
|---|---|---|
| Very low score | Negative record | Negotiate and pay the agreement (step 4) |
| Debt I don't recognize | Error or fraud | Dispute with the bureau, fixed within 10 days (step 3) |
| Loan I didn't take out | Misuse of your CPF | Check Registrato and contact the institution (step 2) |
| Score dropped a little | Normal fluctuation | Track it for a few months (step 10) |
| Credit denied | Lender's criteria or many inquiries | Ask for a review and wait before applying again (step 8) |
| Short history | Little credit experience | Keep the Positive Credit Record active and pay on time (step 7) |
Frequently asked questions
Is checking my score free?
Yes. Brazil's Positive Credit Record Law guarantees free access to your score and history, with no need to justify the request.
Does checking my own score lower it?
No. What weighs is credit searches, when companies check your CPF because you applied for credit.
What is a good score?
On Serasa's scale, 501 to 700 is good and above 700 is excellent. Each bureau has its own scale, and the final decision always belongs to the lender.
How long does a negative record last?
Under Brazil's Consumer Protection Code, negative information can't stay on record for more than 5 years.
After paying the debt, does my score go up right away?
It depends on the bureau and the creditor. Serasa says agreements paid by Pix may update faster. In general, the improvement is gradual.
Can I pay to raise my score?
No. Anyone charging to “raise your score” or “clear your name” is running a scam. The ways to improve it are free.
Should I cancel my Positive Credit Record?
You can, for free. But once it's canceled, your history of on-time payments no longer counts toward your score.
How do I dispute wrong information?
File a dispute with the bureau itself. By law, it must be corrected within 10 days. If not, complain on consumidor.gov.br or to Procon.
What is Registrato?
It's a free Central Bank of Brazil system with reports about you, such as loans and financing, Pix keys and bounced checks. You sign in with a silver or gold gov.br account.
Why was I denied even with a high score?
The score is only one criterion. The lender may consider income, debts and its own policies. If the decision was automated, you can ask for a review.
Related content
More practical solutions in Financial budget.
How to Cancel Forgotten Subscriptions and Save Money
Find recurring subscriptions that may be consuming your budget and learn how to identify automatic charges and cancel services you no longer use.
 10 minutes
How to Cut Unnecessary Expenses Without Giving Up Everything
Learn how to identify low-value spending, reduce waste, and save money without unnecessarily sacrificing your quality of life or essential needs.
30 minutes
How to Organize Your Monthly Budget in 8 Practical Steps
Learn how to organize your monthly budget, understand where your money is going, reduce unnecessary spending, control expenses, and make room for financial goals without compromising essential needs.
15 minutes
Sources
- Law 12,414/2011 (Positive Credit Record Law), arts. 3, 4, 5 and 14 (in Portuguese)
- Consumer Protection Code (Law 8,078/1990), art. 43 (in Portuguese)
- Central Bank of Brazil: Registrato (in Portuguese)
- Central Bank of Brazil: Registrato reports (in Portuguese)
- Serasa: Serasa Score and score manual, weights and ranges (in Portuguese)
- consumidor.gov.br: complaints against companies (in Portuguese)
The images on this page are illustrations created by Fixfy. Weights and ranges are those published by Serasa for the Serasa Score; other bureaus use their own models.