

 Loans
 15 minutes
 10 steps
Quick answer: what to check before a payroll loan in Brazil
- Use a payroll loan (consignado) to replace expensive debt (overdraft, revolving credit) or for an emergency, not for everyday spending.
- Check your margin: at INSS, up to 40% of the benefit (30% for the loan); in the Worker's Credit program (formal employees), up to 35% of your salary.
- Compare the CET (total effective cost) of at least 3 offers on Meu INSS, the Digital Work Card or the Central Bank ranking.
- Choose the shortest term with an installment that fits your month: a long term can nearly double what you pay.
- INSS does not offer loans and never asks for passwords or codes. An offer by phone or WhatsApp is a scam warning sign.
What's your case?
Payroll loan: 10 steps before you sign
1Check whether you really need it
- In a payroll loan, the installment is deducted directly from your salary or benefit before the money reaches you. That's why interest is usually lower.
- Good use: replacing more expensive debt, such as overdraft, credit card revolving credit or a personal loan, or covering an emergency.
- Bad use: paying monthly bills. The installment will cut your income for years and the gap comes back.
Compare with a personal loan.
2Check which type applies to you
- INSS: retirees, pensioners and BPC recipients. The deduction comes out of the benefit.
- Worker's Credit (Crédito do Trabalhador): employees with a formal work card, domestic and rural workers and employees of MEIs. You apply through the Digital Work Card (Carteira de Trabalho Digital) or the app of an authorized bank, and the deduction goes through payroll via eSocial.
- Public servants: follow their own agency's rules. Check with HR.
3Work out your payroll margin
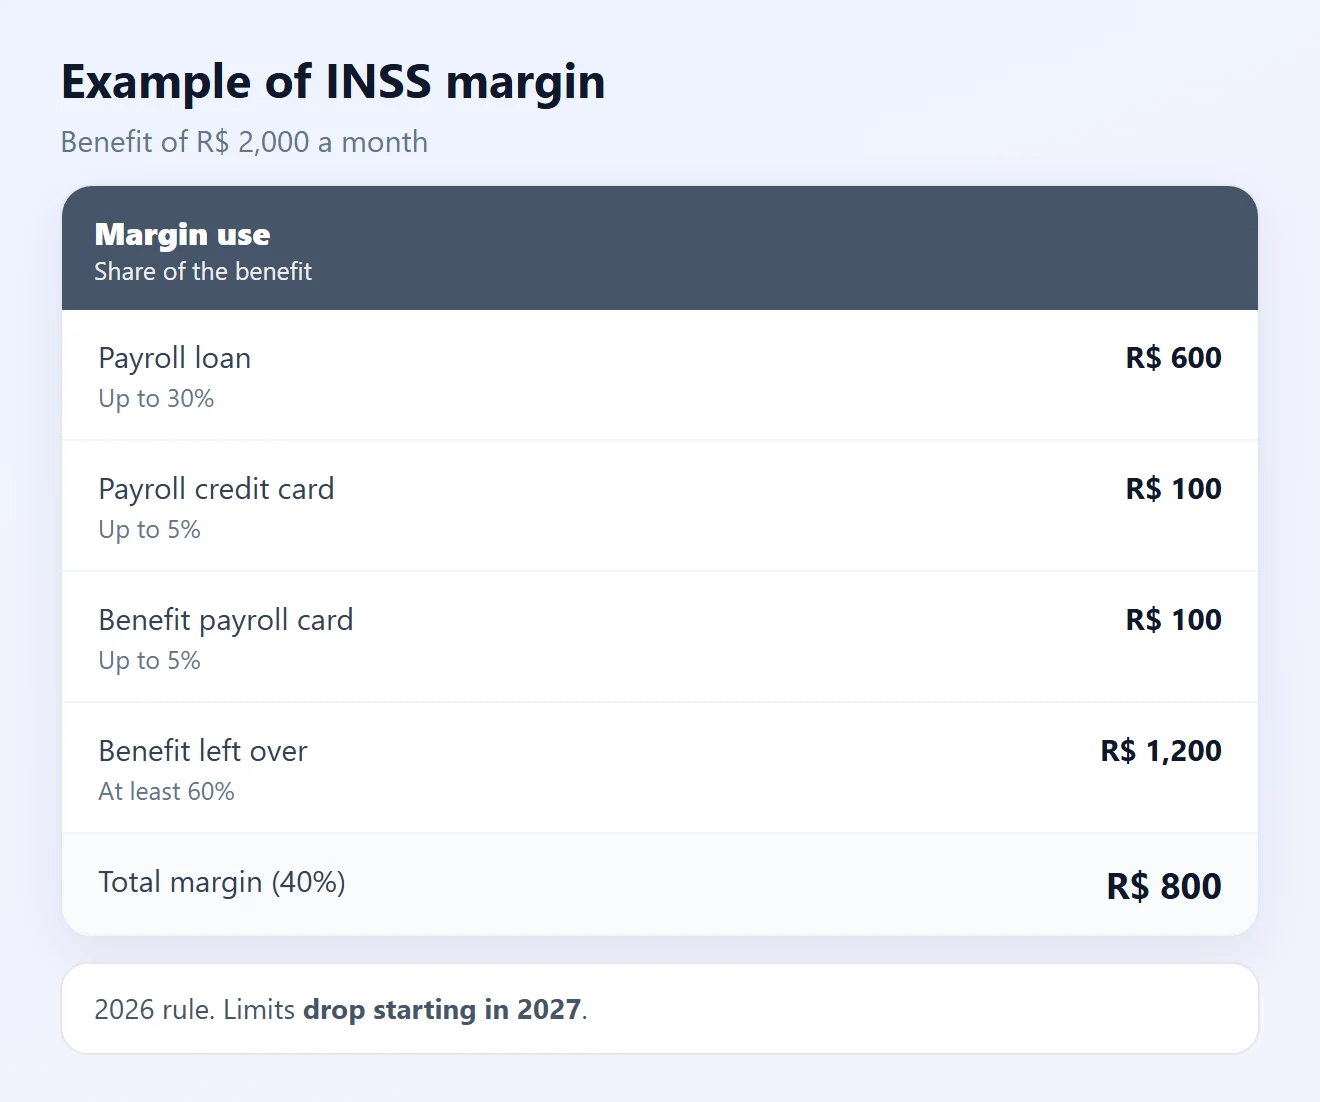
- INSS retirees and pensioners: up to 40% of the benefit. Of that, up to 5% is for the payroll credit card and 5% for the benefit payroll card, leaving 30% for the loan.
- BPC: up to 35% of the benefit, with up to 5% for cards.
- Starting in 2027, the law gradually lowers these limits to 30%. Contracts already signed don't change.
- Worker's Credit: up to 35% of your salary, not counting variable income such as overtime.
- The margin is a maximum, not a target. Ideally, the installment shouldn't squeeze your basic bills.
4Compare the CET of at least 3 offers
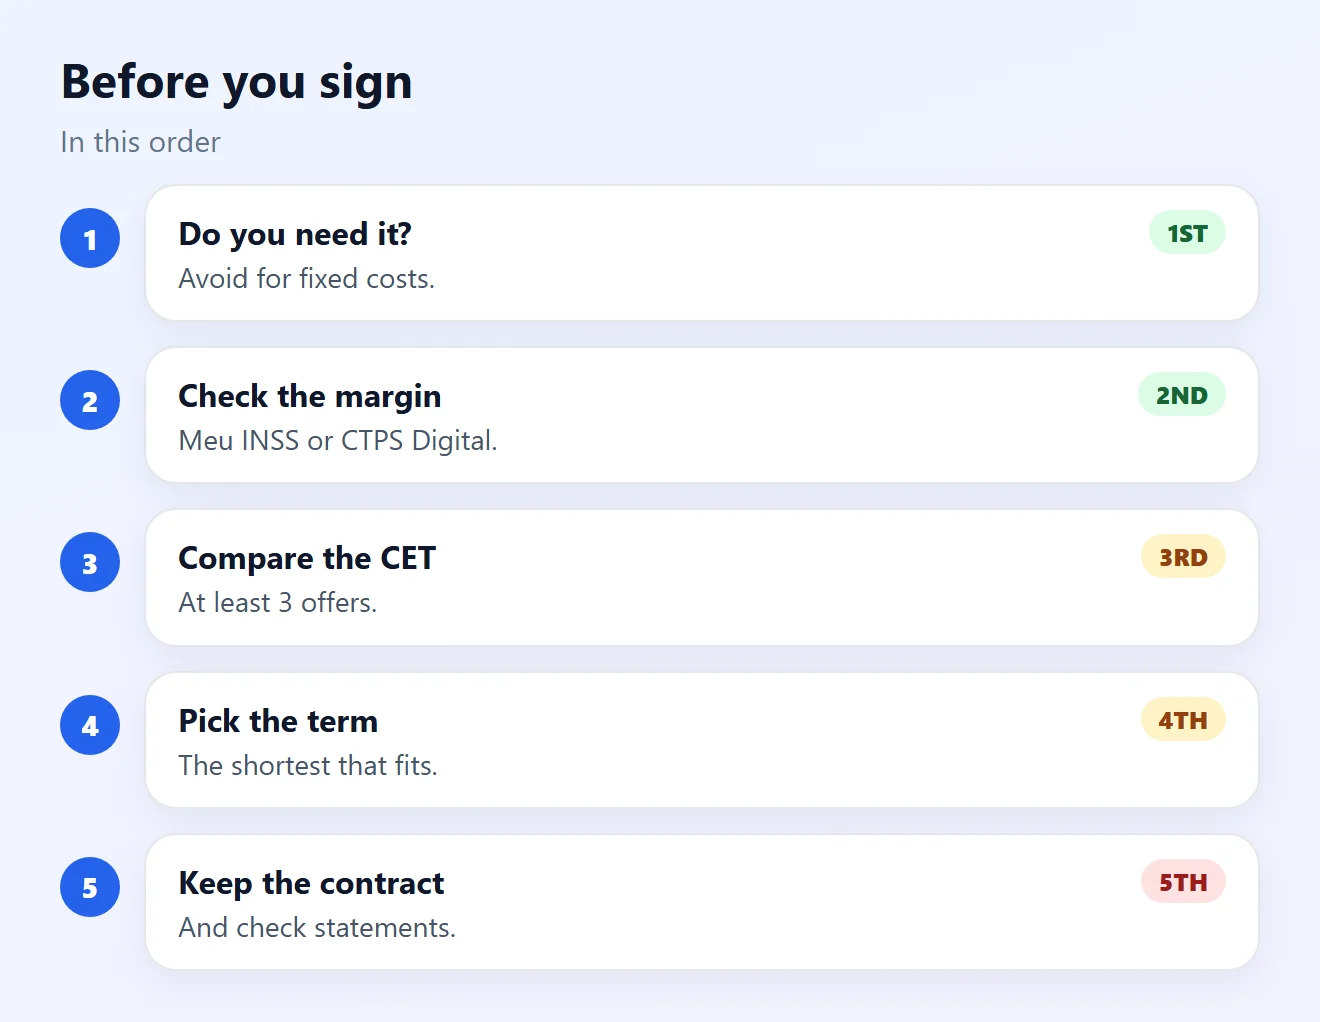
- The CET (Custo Efetivo Total, total effective cost) adds up interest, fees, insurance and taxes. It shows which offer is cheaper, not just the interest rate.
- For INSS, rates show up on Meu INSS, and there is an interest cap set by the National Social Security Council.
- For Worker's Credit, the Digital Work Card shows offers from several banks.
- The Central Bank of Brazil publishes each institution's average rates for INSS, private-sector and public-sector payroll loans.
- Turn down insurance or add-ons you didn't ask for.
5Choose the shortest term that fits your month
- Example with R$ 5,000 at 1.8% a month: over 24 installments, about R$ 258 a month and R$ 6,202 in total. Over 84 installments, about R$ 116 a month, but R$ 9,735 in total.
- For INSS, the contract can have at most 108 installments. The maximum term is almost never the best choice.
- Simulate at least two terms and choose the shortest one where the installment still fits.
6Sign only through official channels
- INSS: new benefits are blocked for payroll loans for the first 90 days. After that, you unblock it on Meu INSS, under “Bloqueio/Desbloqueio de Benefício para Empréstimo”.
- Authorization is done by facial biometrics in the Meu INSS app or, without registered biometrics, by gov.br login with bank details verification.
- Worker's Credit: apply through the Digital Work Card or the official app of a bank authorized by the Ministry of Labor.
- Read the contract and keep a copy with the CET, number of installments and total amount.
7Know how to cancel
- With Worker's Credit, you can cancel within 7 calendar days of receiving the money by returning the full amount to the bank.
- For other types, ask the bank before signing what the deadline is and how to cancel.
- Canceled? Make the request in writing and keep the protocol number.
8Understand what happens if you leave your job
- With Worker's Credit, you can pledge up to 10% of your FGTS balance and up to 100% of the severance fine as collateral, or pledge nothing.
- If you're dismissed, the collateral pays down the debt. Any remaining balance you pay yourself, renegotiate with the bank, or it is deducted at your next job.
- If you resign, the debt remains and the FGTS can't be used to pay it.
9Use portability and early payoff
- Portability: you can move your payroll loan to a bank with lower interest. Ask the destination bank.
- For INSS, portability is authorized on Meu INSS, and the original bank has up to 20 days to confirm. Portability is not a new loan: be wary if they offer you extra cash.
- Paying off early: under Brazil's Consumer Protection Code, early payment entitles you to a proportional reduction of interest.
10Check your statement and dispute what you don't recognize
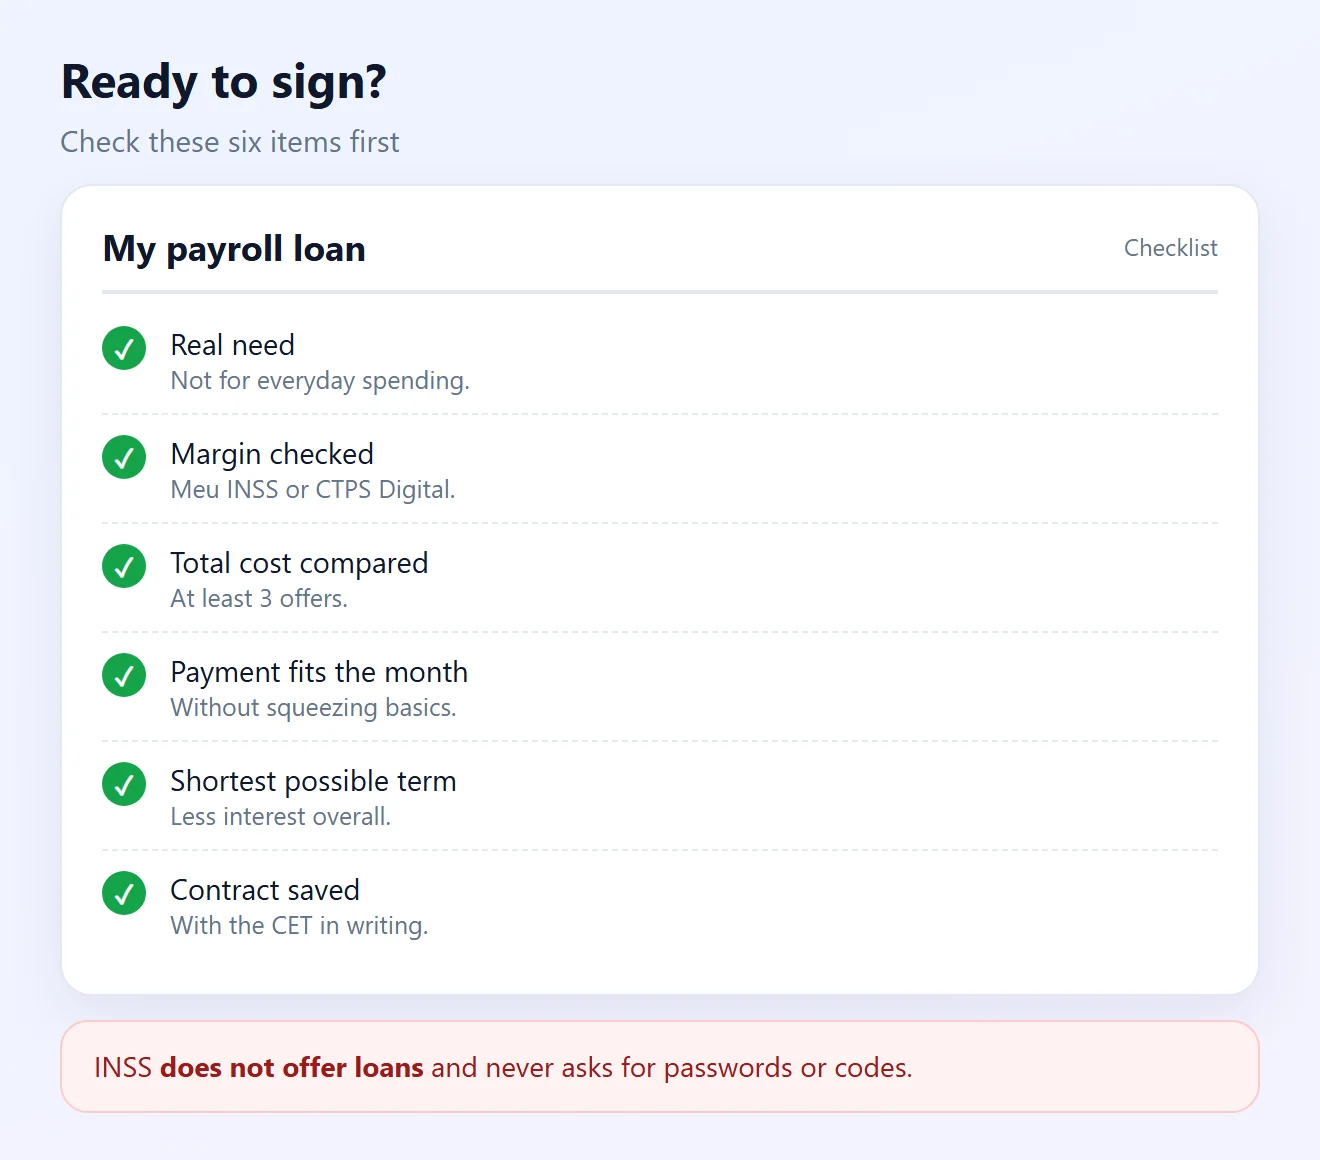
- For INSS, check the Payroll Loan Statement on Meu INSS. If you're not borrowing, keep the benefit blocked.
- A loan you didn't take out? Contact the bank and ask for cancellation and a refund. File a complaint on consumidor.gov.br or with Procon and keep the protocol numbers.
- INSS does not offer, broker or recommend loans. Nobody needs a middleman to block or unblock the benefit.
Installments taking most of your income? See what to do about over-indebtedness.
Problem and fix
| Problem | Likely cause | Fix |
|---|---|---|
| Can't borrow through INSS | Benefit blocked or under 90 days old | Unblock on Meu INSS (step 6) |
| Not enough margin | Other deductions already use it | Lower the amount or pay off contracts (step 3) |
| Interest higher than another bank's | Offer not compared | Portability (step 9) |
| Total cost too high | Long term | Shorter term or early payoff (steps 5 and 9) |
| Deduction I don't recognize | Fraud or unauthorized contract | Bank, consumidor.gov.br and Procon (step 10) |
| Dismissed with a payroll loan | Balance not covered by collateral | Pay, renegotiate or carry it to the next job (step 8) |
Frequently asked questions
What is a payroll loan (consignado)?
It's a loan whose installments are deducted directly from your salary, INSS benefit or public servant pay, with your authorization.
What is the INSS payroll margin?
Up to 40% of the benefit for retirees and pensioners, with up to 5% for the payroll credit card and 5% for the benefit payroll card. For BPC, up to 35%. The limits drop gradually starting in 2027.
What is the Worker's Credit margin?
Up to 35% of your salary, not counting variable income such as overtime.
How many installments can an INSS payroll loan have?
At most 108 monthly installments. The longer the term, the more interest you pay overall.
Does INSS offer loans?
No. INSS does not offer, broker or recommend loans, and never asks for a password, code or payment to release credit.
Can I cancel a payroll loan?
With Worker's Credit, yes, within 7 calendar days of receiving the money, by returning the full amount. For other types, confirm the deadline with the bank before signing.
What happens to my payroll loan if I'm dismissed?
FGTS collateral, if you pledged it, pays down the debt. Whatever is left you pay yourself, renegotiate, or it is deducted at your next job.
Can I move my payroll loan to another bank?
Yes, through portability. Ask the destination bank. For INSS, the operation is authorized on Meu INSS.
Does paying off early reduce interest?
Yes. Brazil's Consumer Protection Code guarantees a proportional reduction of interest and charges on early payoff.
A loan I didn't take out showed up. What do I do?
Contact the bank and ask for cancellation and a refund, file a complaint on consumidor.gov.br or with Procon, and keep all protocol numbers. For INSS, keep the benefit blocked.
Related content
More practical solutions in Loans.
Sources
- INSS: payroll deductions on benefits, rights and safety measures (in Portuguese)
- Ministry of Labor and Employment: Worker's Credit (in Portuguese)
- Ministry of Labor and Employment: Worker's Credit FAQ (in Portuguese)
- Central Bank of Brazil: interest rates by institution (in Portuguese)
- Consumer Protection Code (Law 8,078/1990), art. 52 (in Portuguese)
- consumidor.gov.br: complaints against companies (in Portuguese)
The images on this page are illustrations created by Fixfy. Amounts are examples; the 1.8% monthly rate is used only for the simulation.