

 Financial security
 10 steps
Quick answer: what to do about an unrecognized card purchase
- Check it isn't one of your own purchases under another name on the bill: the store's legal name, a subscription, an old installment or an additional card.
- Still don't recognize it? Block the card in your bank's app now.
- Dispute the purchase in the app or through customer service (SAC) and write down the protocol number. In Brazil the bank must suspend an undue charge within 48 hours.
- File a police report and tell the store where the purchase was made.
- No solution? Go to the bank's ombudsman, complain to the Central Bank, consumidor.gov.br or Procon.
What's your case?
Unrecognized card purchase: 10 steps to dispute it and get your money back
1Check whether the purchase is really unknown
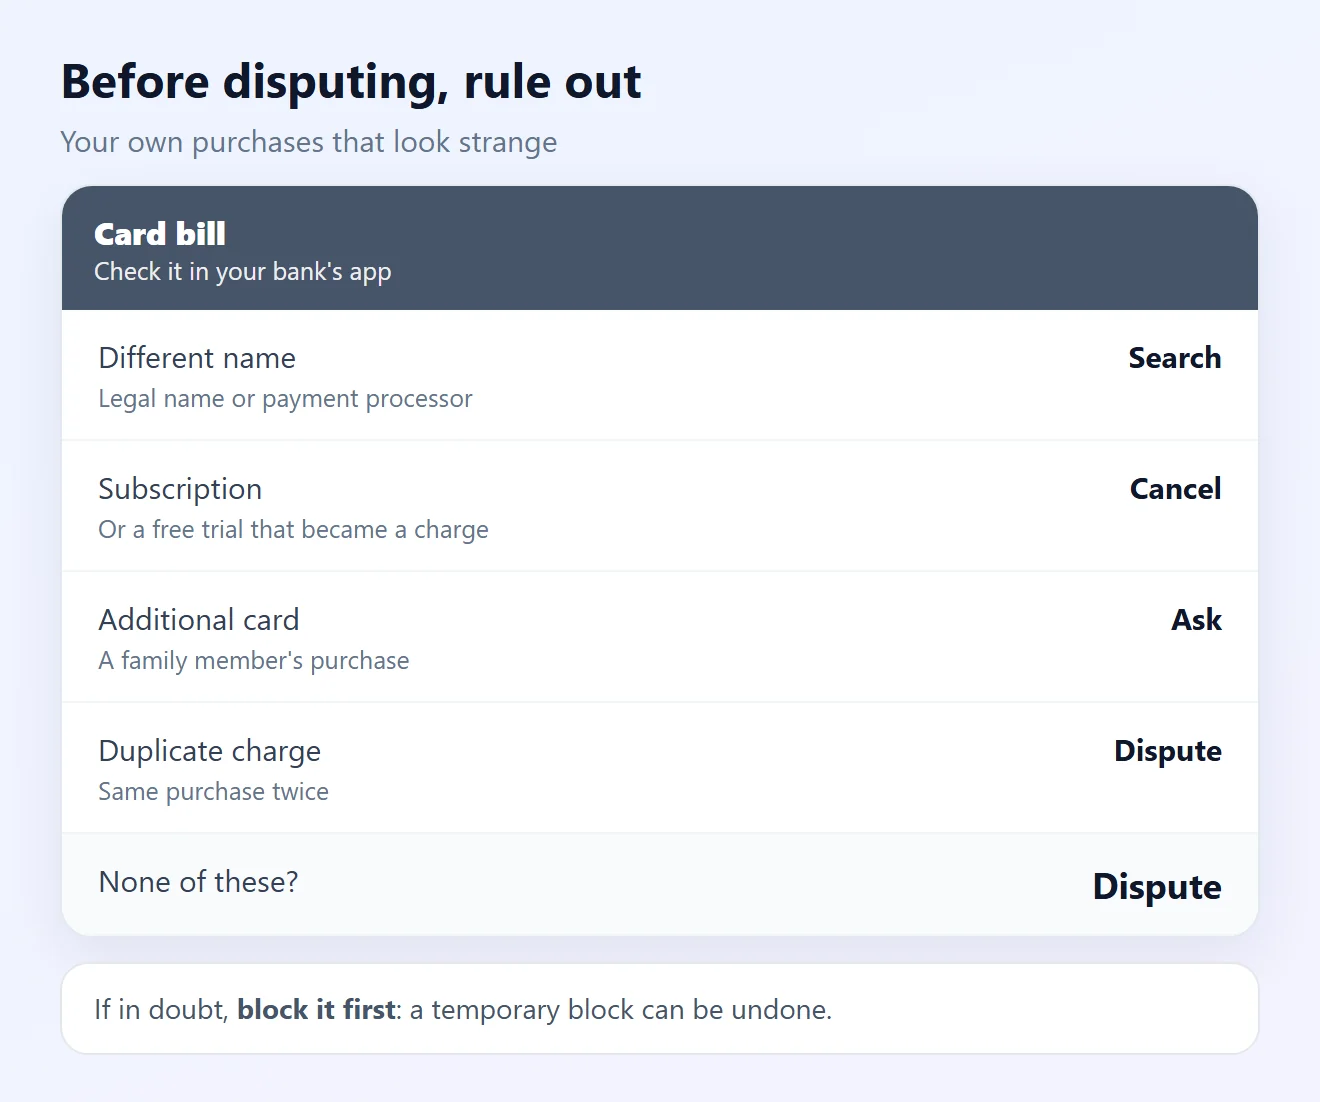
- Many stores show up on the bill under their legal company name or the name of the payment processor, not the brand you know. Search the name in your bank's app: many show the location and CNPJ of the purchase.
- Check it isn't a subscription (streaming, apps, gym), a free trial that became a charge, an installment of an old purchase or a purchase on an additional card.
- Purchases in dollars may show a different amount because of the exchange rate and IOF tax.
- If you still don't recognize it, go to step 2 without waiting.
2Block the card in your bank's app
- Use the block option in the app or call the number on the back of the card. It's the first step recommended by Brazil's Ministry of Justice.
- A temporary block works while you check. If fraud is confirmed, ask for cancellation and a new card with a different number.
- Also block your virtual cards and remove the card from digital wallets and websites where it was saved.
3Dispute the purchase and write down the protocol number
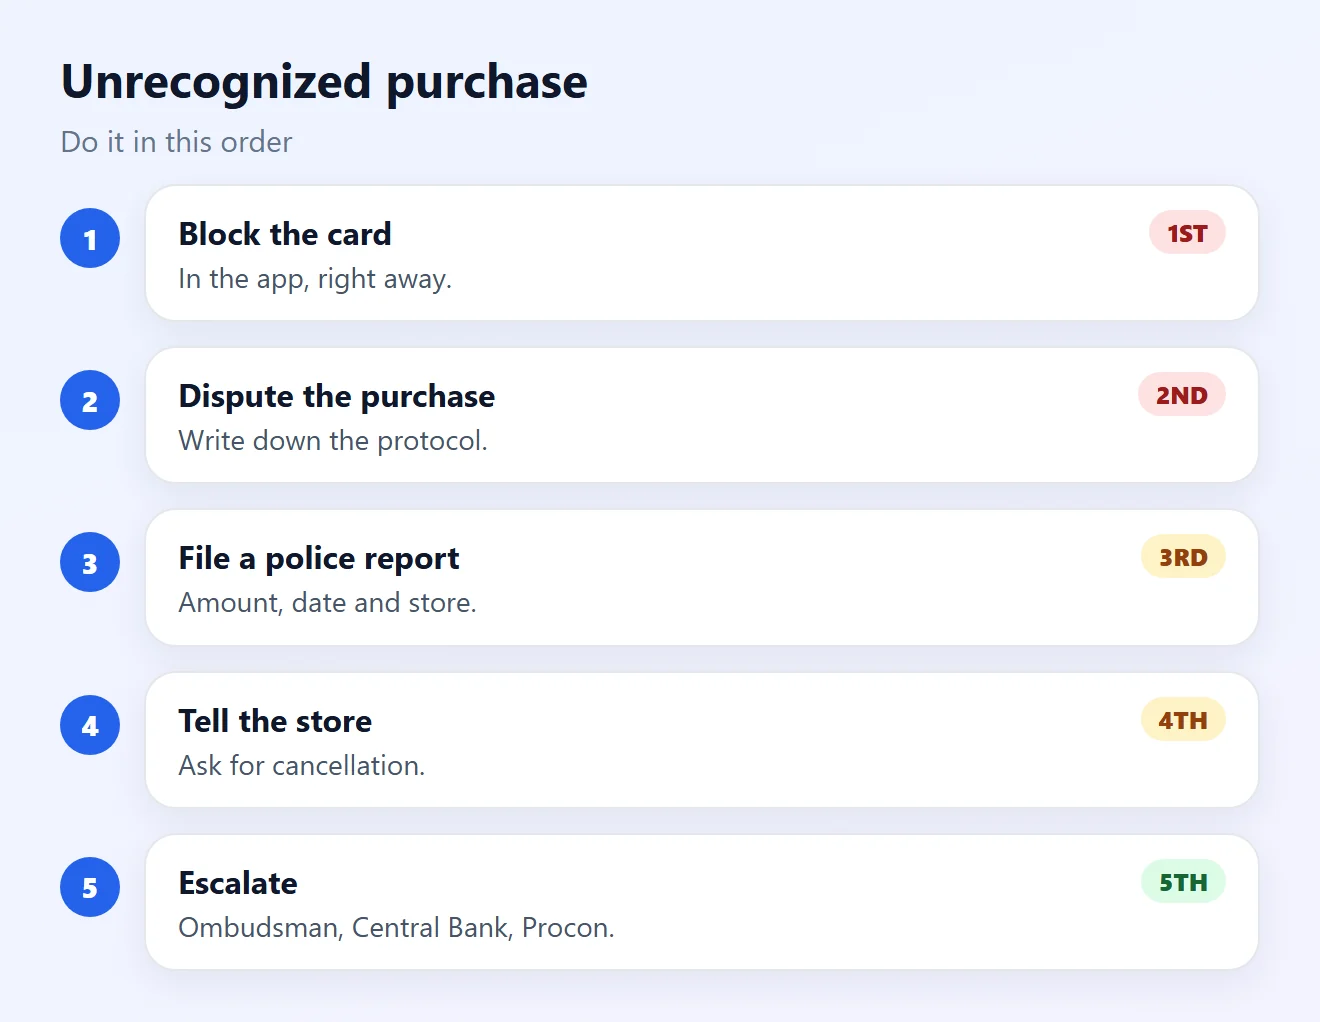
- In the app, look for "dispute purchase" or "I don't recognize this purchase" on the bill. If there's no such option, use customer service (SAC).
- Give the date, amount and name shown on the bill and say you didn't make the purchase. Ask for the protocol number.
- Under Brazil's new customer service decree (Decree 13,135/2026), for an undue charge the bank must suspend it within 48 hours and answer the request within 7 calendar days.
4Dispute it as soon as possible
- Each bank and card network has a deadline to accept a dispute. It appears in the app or in the card contract. After it, the request may be refused.
- Check the bill and notifications every week. Fraud often starts with small purchases to test the card.
- Found more than one strange purchase? Dispute all of them in the same request.
5Know what to do with the bill
- Ask the bank whether the disputed purchase will be suspended or reversed on the bill and get written confirmation in the app or by email.
- Pay the rest of the bill on time. Leaving it all unpaid triggers revolving credit interest on what you do owe.
- If you pay the undue charge, you can ask for it back. Under Brazil's Consumer Protection Code (art. 42), whoever charged you unduly must refund double the amount, with adjustment, unless the error is justifiable. Brazil's Superior Court of Justice (STJ) holds that bad faith doesn't have to be proven.
See also how to understand a credit card bill that's higher than usual.
6File a police report
- File the report (boletim de ocorrência) online or in person, with your state's police.
- Include the amount, date and merchant, the last 4 digits of the card and the issuing bank, as the Ministry of Justice recommends.
- Attach screenshots of the bill, the notifications and the dispute protocol.
7Tell the store or platform where the purchase was made
- If you know where the purchase was made, contact the store through its official channel.
- Explain that the purchase is fraud and ask for the order to be cancelled and for proof.
- If the purchase showed up in an account of yours in an app or online store, change the password and turn on two-step verification.
8Was it debit or Pix? Act the same way
- A debit purchase takes the money from your account right away. Block the card and dispute it the same way, asking for a refund to the account.
- If the money left by Pix, the route is different: ask your bank for the Special Return Mechanism (MED) as soon as possible.
- Be wary of anyone who calls claiming to be from the bank to "cancel the purchase" and asks for a password, code or Pix. Banks don't ask for that.
9If the bank says no, escalate
- With the SAC protocol number, go to the bank's ombudsman (ouvidoria). It has up to 10 business days to answer (CMN Resolution 4,860).
- File a complaint with the Central Bank of Brazil. You need a silver or gold gov.br account. The Central Bank doesn't settle individual cases, but the bank has up to 10 business days to answer and the complaint feeds its supervision.
- Also complain on consumidor.gov.br or to Procon. As a last resort, go to the Small Claims Court. Under STJ Precedent 479, banks are liable for fraud linked to banking operations.
10Protect the card so it doesn't happen again
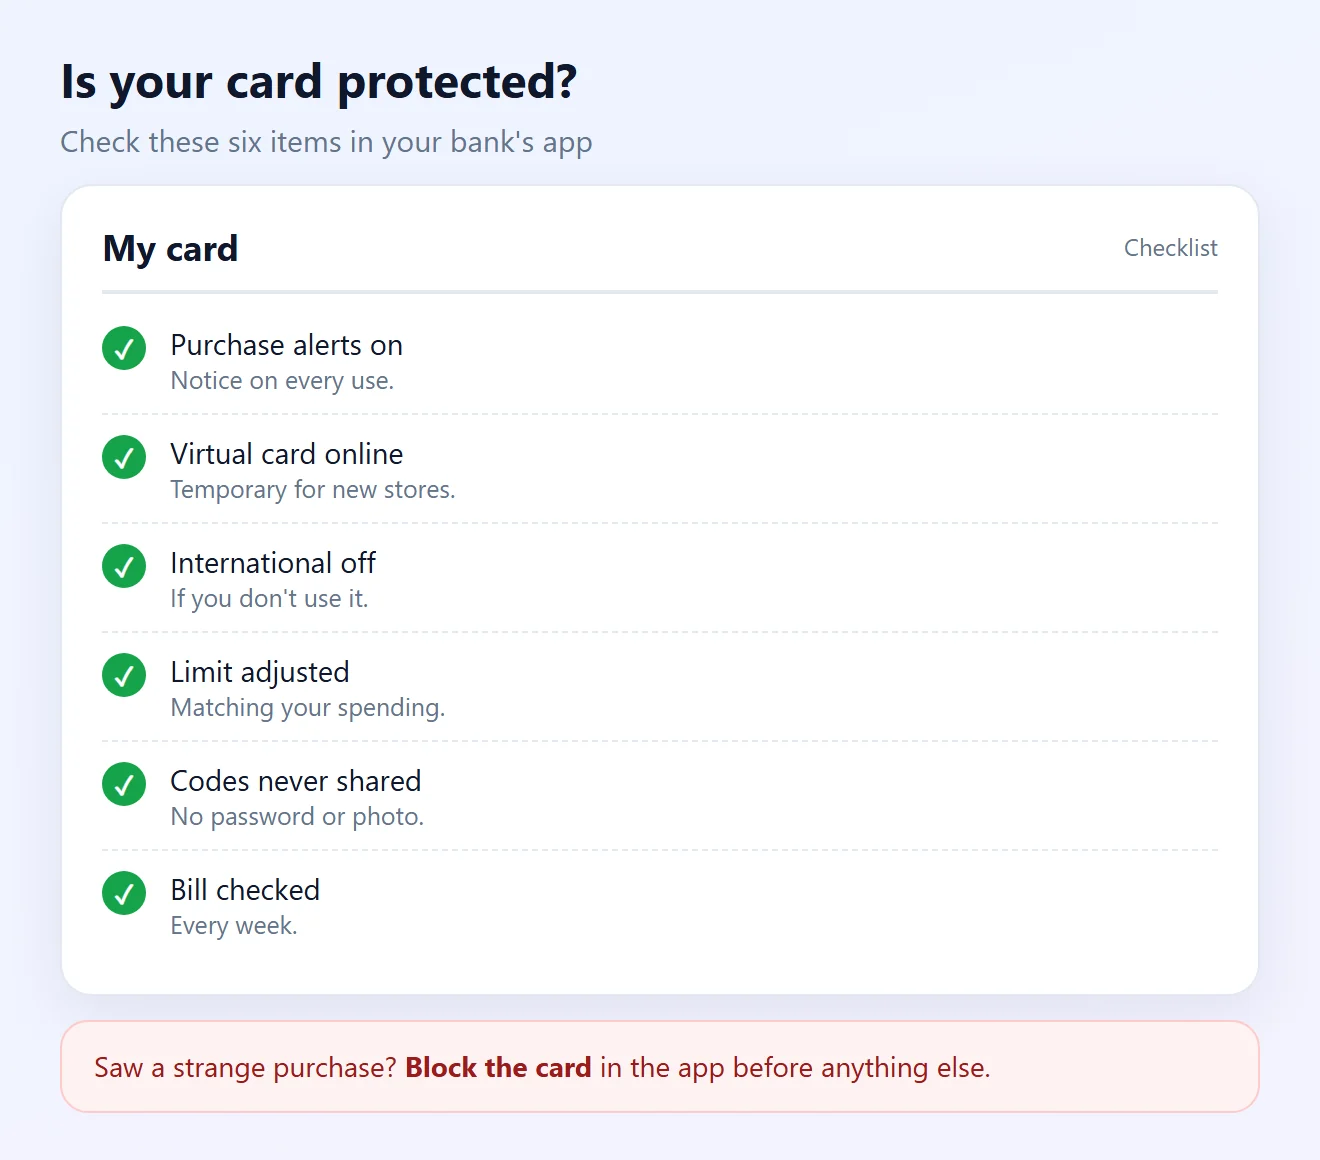
- Turn on purchase alerts in the app: you see every card use right away.
- Use a virtual card for online purchases, ideally a temporary one for new stores.
- Turn off international or online purchases in the app when you don't use them and set the limit to what you actually spend.
- Never share a verification code, password or photo of the card by phone or message.
See also how to make your digital bank account safer and how to create a secure bank password.
Common situations and what to do
| Situation | What it may be | What to do |
|---|---|---|
| Strange name on the bill | Store's legal name or payment processor | Check in the app before disputing (step 1) |
| Several small purchases in a row | Cloned card being tested | Block and dispute all of them (steps 2 and 4) |
| Monthly charge you don't remember | Subscription or free trial | Cancel with the store and dispute if you didn't sign up (steps 1 and 7) |
| Same purchase twice | Duplicate charge | Dispute the copy (step 3) |
| Debit purchase | Leaked card or data | Block and ask for a refund to the account (step 8) |
| Bank rejected the dispute | Incomplete review | Ombudsman, Central Bank and Procon (step 9) |
Frequently asked questions
What should I do first when I see a purchase I don't recognize?
Check it isn't one of your own purchases under another name on the bill. If it isn't, block the card in the app and dispute the purchase the same day.
How do I dispute a card purchase?
In your bank's app, using the option to dispute or not recognize the purchase, or through customer service (SAC). Give the date, amount and name of the purchase and write down the protocol number.
How long does the bank have to solve it?
Under Decree 13,135/2026, the bank must suspend an undue charge within 48 hours and answer the SAC request within 7 calendar days. The ombudsman has up to 10 business days.
Do I have to pay the bill with the disputed purchase on it?
Ask the bank whether the amount will be suspended and get written confirmation. Pay the rest of the bill on time to avoid revolving credit.
I paid the undue charge. Do I get it back?
If the dispute is accepted, yes. Under art. 42 of Brazil's Consumer Protection Code, an amount paid for an undue charge is refunded double, unless the error is justifiable.
Do I need to file a police report?
It's recommended. Include the amount, date, merchant, the last 4 digits of the card and screenshots of the bill. It helps with the dispute and with any complaint.
The card was with me. How was it used?
Online purchases only need the card details, which can leak through fake websites, scam messages or hacked databases. That's why you should ask for a new card with a different number.
Can a debit purchase be disputed too?
Yes. Block the card, dispute it with the bank and ask for a refund to the account. If the money left by Pix, ask for the MED.
The bank said no. What now?
Go to the ombudsman with the protocol number, file a complaint with the Central Bank and on consumidor.gov.br or with Procon. As a last resort, the Small Claims Court.
How do I avoid new undue purchases?
Turn on purchase alerts, use a virtual card online, turn off international purchases when you don't use them and never share codes or passwords.
Related content
More practical solutions in Financial security.
Fake Payment Slip: How to Identify It Before Paying
Learn the recognize sinais of fake payment slip, check data of the payee and avoid golpes financial before concluir a payment.
 10 minutes
 Pix
Pix Transfer Not Received: How to Check Delays and Resolve the Problem
Pix transfer not received? Learn how to check the transaction status, how long to wait, and what steps to take when the money does not appear.
10 to 15 minutes
Pix Scam: How to Act Quickly and Protect Your Money
Learn what to do after a Pix scam, how to report the incident, contact your bank promptly, and protect your accounts.
Sources
- Ministry of Justice: someone made purchases with my card (in Portuguese)
- Decree 13,135/2026: customer service (SAC) rules, art. 21 (in Portuguese)
- Central Bank of Brazil: CMN Resolution 4,860, ombudsman offices (in Portuguese)
- Central Bank of Brazil: complaint against a financial institution (in Portuguese)
- Consumer Protection Code: art. 42 (in Portuguese)
- STJ: Precedent 479, bank liability for fraud (in Portuguese)
- consumidor.gov.br: complaints against companies (in Portuguese)
The images on this page are illustrations created by Fixfy.